Construction Equipment Financing: What Contractors Need Before Buying Machinery
Construction equipment financing can help a contractor evaluate a major machinery purchase without treating the entire project as a generic business loan request. Funding providers may review both the equipment being purchased and the financial profile of the company.
If you already have a quote for an excavator, loader, truck or other business equipment, submit the purchase price and current business profile through the EIN Business Funding Quick Lead Pre-Qualification.
What Do Equipment Financing Providers Evaluate?
The EIN Business Funding guidance identifies equipment financing as a business funding category. It also notes that lenders commonly consider personal credit, business credit if established, time in business, annual revenue, cash flow, existing debt, industry, collateral for some financing and personal guarantees.
What Should a Contractor Prepare?
Have the equipment quotation, purchase price, requested financing amount, business entity information, EIN, formation date, ownership percentage, annual revenue, banking information and current Experian FICO score ready.
Existing business credit cards, lines of credit and loans should also be organized with the lender name, credit limit, balance and open date.
Why Does the Equipment Use Matter?
A clear use of funds helps the provider understand the financing request. Explain whether the machinery is replacing an existing asset, expanding capacity, supporting a new project or adding a new operating capability.
Could SBA 504 Be Relevant for Large Equipment?
For qualifying long-term fixed assets, SBA 504 may also be worth evaluating. The funding guidance identifies large equipment as a primary SBA 504 use and lists demonstrated repayment ability and a typical down-payment range of approximately 10% to 20% among common requirements.
Does Equipment Financing Have One Universal Credit Score?
No. The EIN Business Funding source does not establish one universal credit threshold for all equipment-financing providers. Actual requirements depend on the provider, equipment and borrower profile.
If your construction or infrastructure business is actively purchasing equipment, complete the EIN Business Funding pre-qualification with the asset cost and financing need.
FAQs
Can contractors finance construction equipment?
Potentially. Equipment financing is a recognized business funding category, with eligibility depending on the provider, asset and borrower profile.
What should I prepare before seeking construction equipment financing?
Prepare the equipment quote, financing amount, credit profile, annual revenue, business history, banking information and existing debt.
Can SBA 504 financing be used for large construction equipment?
SBA 504 is designed for qualifying long-term fixed assets, including large equipment, subject to program and lender requirements.
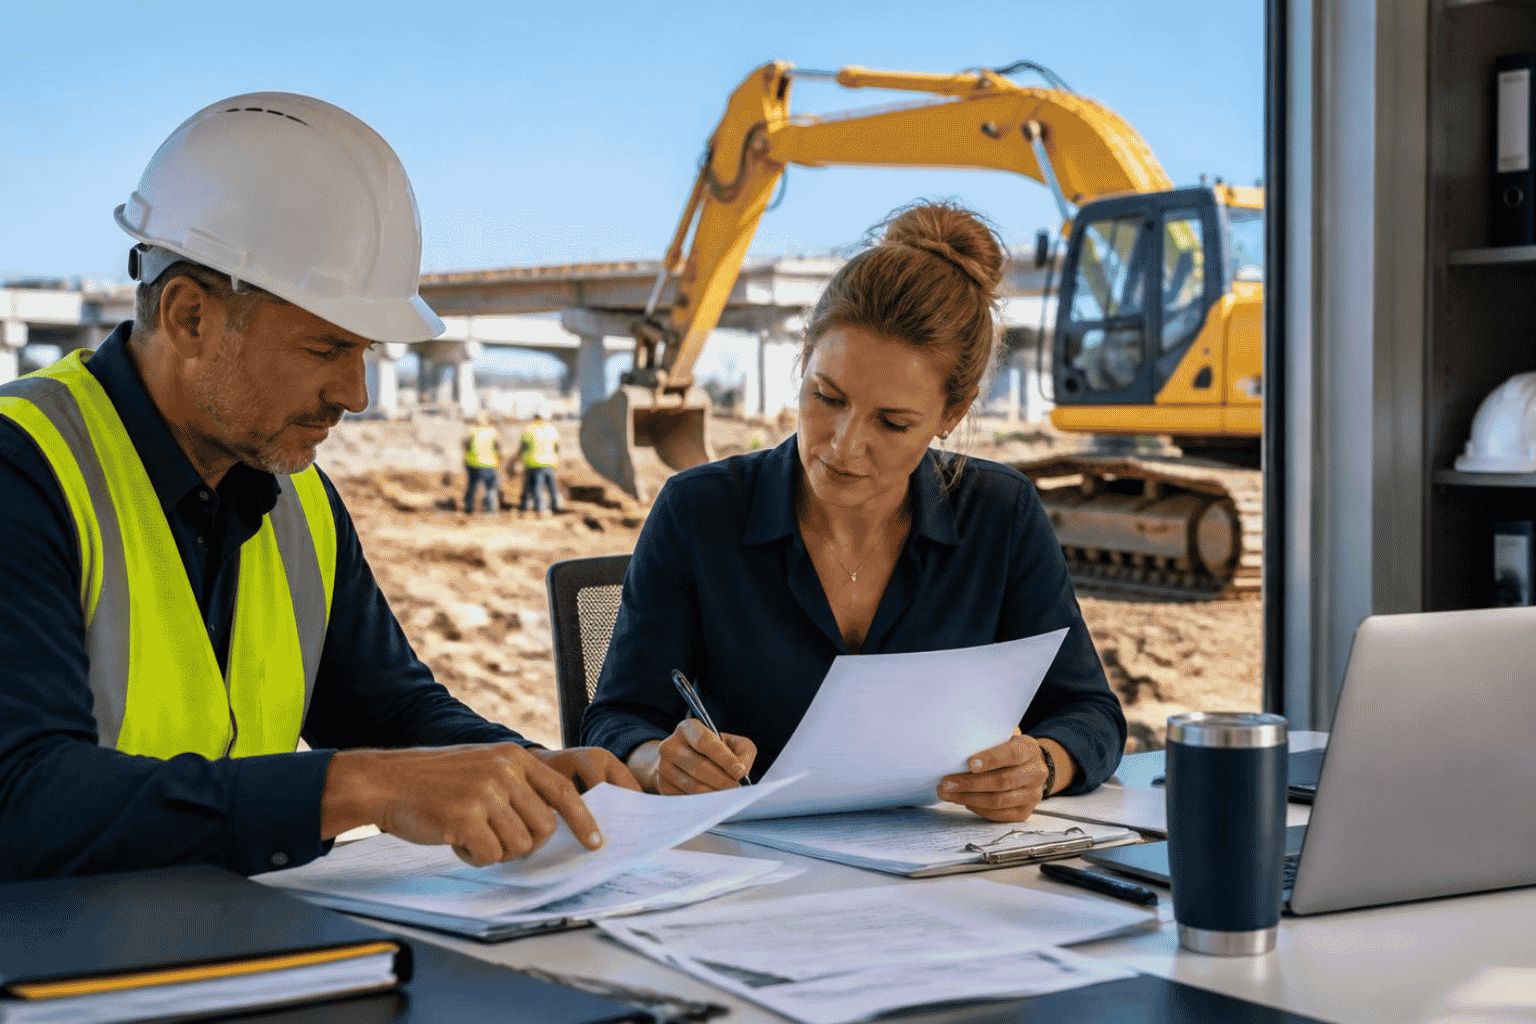 Contractors should prepare equipment cost, credit, revenue, banking and debt information before seeking machinery financing.