Business Funding Application: Match the Financing to Your Use of Funds Before You Apply
A business funding application becomes much more useful when the owner can clearly answer one question: what exactly will the money be used for?
If your business needs capital now, complete the EIN Business Funding Quick Lead Pre-Qualification with the requested amount and specific use of funds.
Need Money for Short-Term Operating Expenses?
Working-capital financing may be worth evaluating for qualifying short-term business needs. Typical benchmarks in the EIN Business Funding guidance include approximately 600+ personal credit, six to twelve months in business and around $50,000 to $100,000 in annual revenue.
Buying Machinery or Business Equipment?
Equipment financing may be more directly aligned with a qualifying asset purchase than a general-purpose loan. Have the equipment quotation and purchase price ready when requesting a funding review.
Funding a Defined Expansion Project?
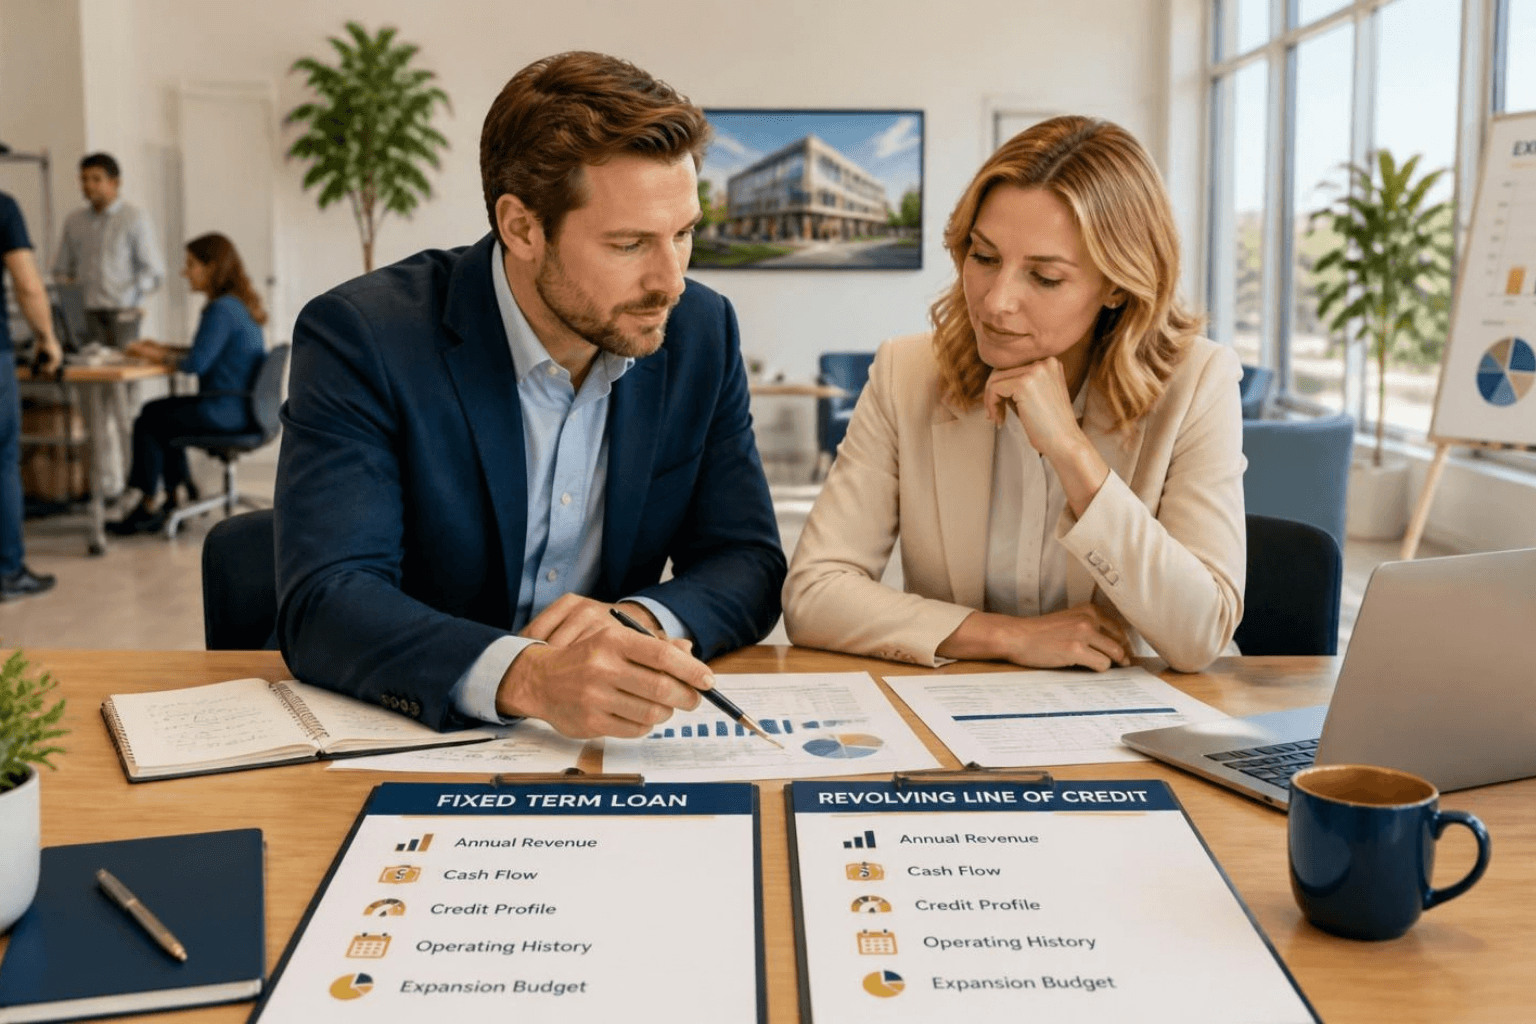
A term loan may be worth evaluating when the business has a specific expansion requirement. Common term-loan benchmarks include approximately 600 to 680+ credit, one or more years in business, around $100,000+ annual revenue and positive cash flow.
Need Recurring Access to Business Capital?
A traditional business line of credit may fit certain established businesses needing revolving access to capital. Typical benchmarks are stricter, commonly including approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ annual revenue and positive cash flow.
Buying Another Business?
An acquisition requires a transaction-specific review. Purchase price, buyer contribution, target-company cash flow, existing debt and post-closing funding requirements can all matter.
What Information Should Every Funding Application Include?
- Requested funding amount
- Specific use of funds
- Current credit profile
- Time in business
- Annual business revenue
- Business banking information
- Existing business debt
The client-profile information used in funding discussions also includes the entity type, formation date, EIN, ownership percentage, banking institution and details of open credit cards, lines of credit and business loans.
If you know what the capital is for, complete the EIN Business Funding pre-qualification so the request can be reviewed against financing categories that may better fit the need.
Questions Business Owners Ask
Why does the use of funds matter on a business funding application?
Different financing products are designed for different business needs, so a clear purpose helps narrow the relevant funding categories.
Should I apply for every type of business financing?
Not necessarily. Understanding the current borrower profile and use of funds can help avoid unnecessary applications.
What information should I prepare before applying?
Prepare your funding amount, use of funds, credit, time in business, revenue, banking information and existing debt.
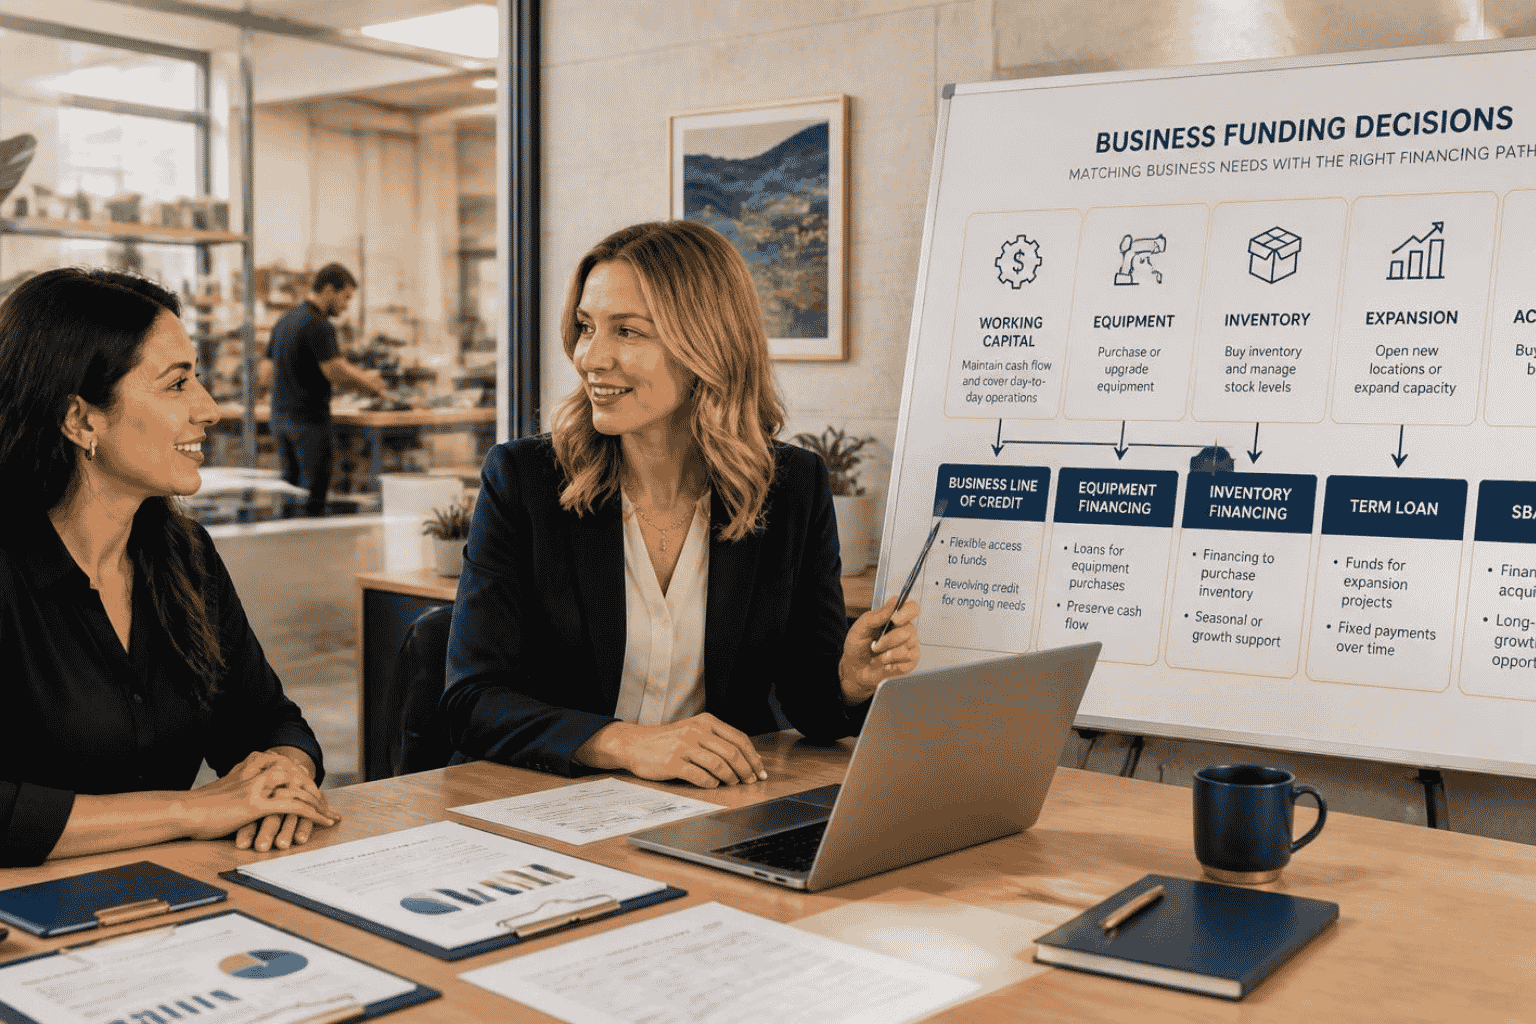 A clearer use of funds can help determine which business-financing categories are worth evaluating.