SBA 7(a) Business Loan With EIN: What Government-Backed Lending Still Requires
An SBA 7(a) loan is often described as government-backed business financing, but that description can create confusion. The government does not simply issue funding to a company because it has an EIN. Participating lenders make the loans while following applicable SBA program requirements.
That distinction matters for business owners searching for an “SBA loan with EIN” or similar terms.
Does an EIN Qualify a Business for an SBA 7(a) Loan?
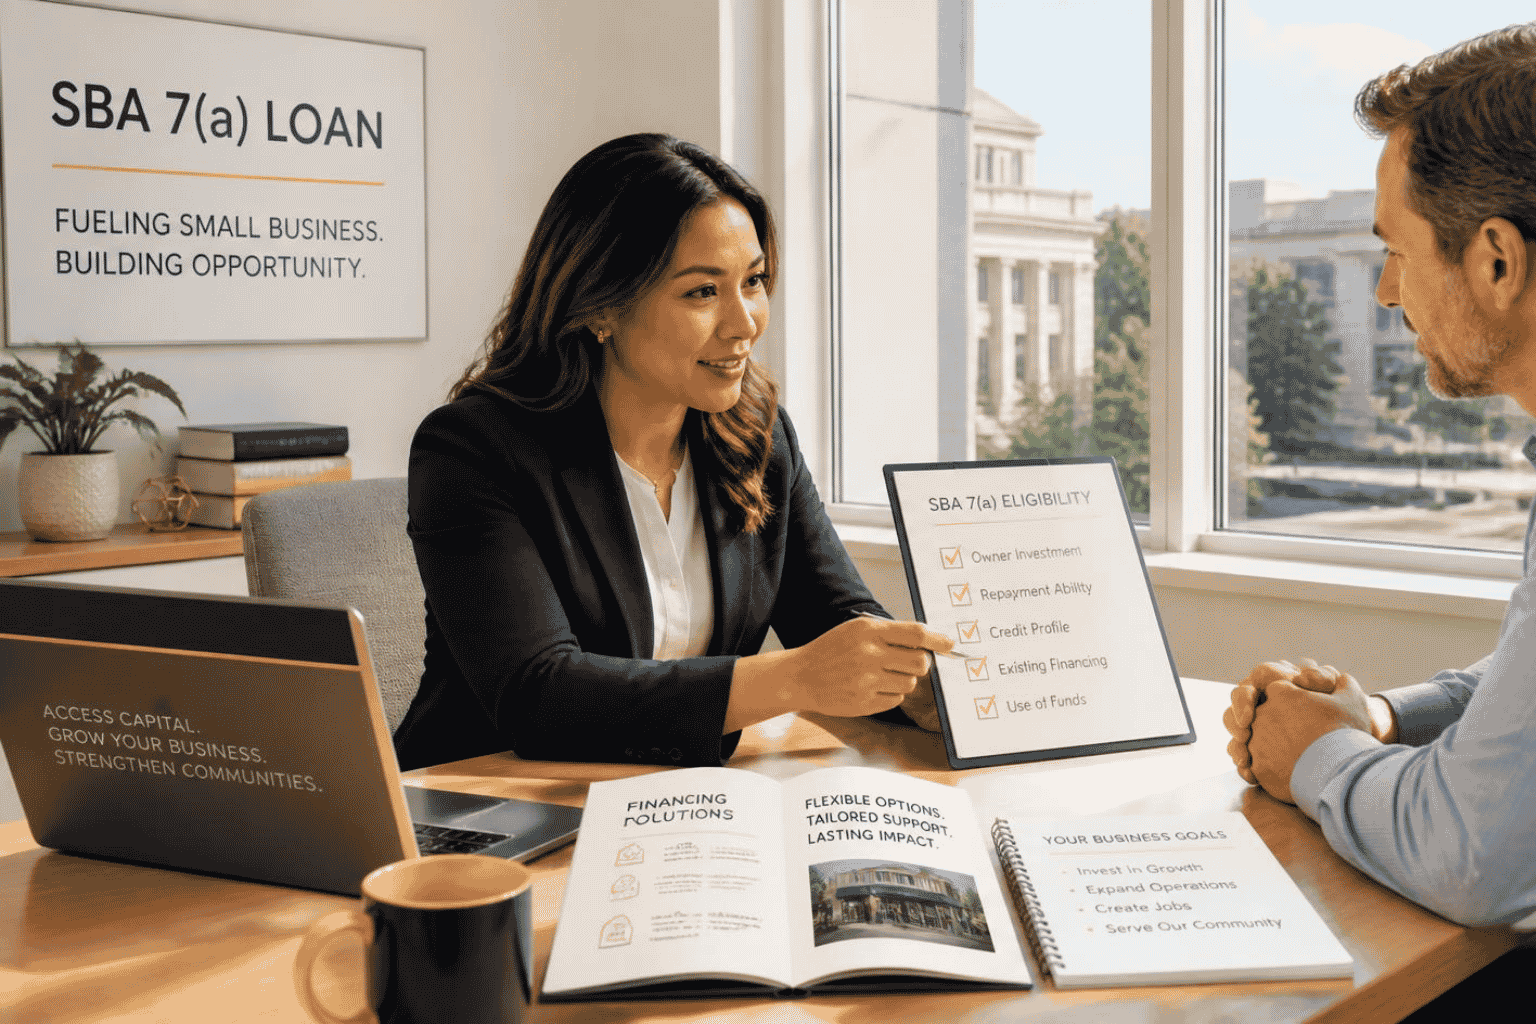
No. An EIN identifies the business, but the EIN Business Funding guidance identifies additional SBA 7(a) considerations including for-profit U.S. business status, applicable size standards, reasonable owner equity investment, demonstrated ability to repay and good personal credit.
What Personal Credit Is Commonly Associated With SBA 7(a)?
The funding guidance identifies approximately 680 to 700+ personal credit as a common benchmark, while also noting that lender requirements vary.
Credit is only one part of the review. Revenue, cash flow, business history and the requested use of funds may also be important.
Why Does Owner Equity Matter?
Reasonable owner equity investment is identified among the typical SBA 7(a) considerations in the funding guidance. The exact amount or structure depends on the transaction and lender requirements.
What Happens When Several People Own the Business?
Ownership percentages should be clear before the application begins. The EIN Business Funding guidance notes that owners with 20% or more ownership generally provide a personal guarantee for SBA 7(a) financing.
Can Collateral Be Required?
Potentially. The guidance notes that a lender may require collateral for larger SBA 7(a) loans.
What Does “Credit Elsewhere” Mean?
The guidance also notes that the borrower generally cannot obtain similar financing on reasonable terms elsewhere. This is one of the reasons government-backed financing should not be treated as identical to every conventional business loan.
What Business Information Should Be Ready?
- Legal business name and EIN
- Entity type and formation date
- State of organization
- Ownership percentages
- Annual business revenue
- Business banking information
- Current personal credit profile
- Existing business debt
- Requested financing amount
- Specific use of funds
Does SBA Backing Mean Approval Is Easier?
Not automatically. SBA-related financing has its own eligibility and underwriting requirements. Government backing does not remove the need to demonstrate repayment ability.
When Should a Business Explore SBA 7(a)?
The appropriate funding path depends on the purpose of the capital, business profile, requested amount and lender. Owners should avoid assuming that SBA financing is automatically the best or only option simply because the company has an EIN.
If you are actively seeking business capital and believe SBA-related financing may fit your need, complete the EIN Business Funding Quick Lead Pre-Qualification using your actual ownership, revenue, credit and funding information.
FAQs
Can I get an SBA 7(a) loan with an EIN?
An EIN is part of the business information, but SBA 7(a) financing also involves borrower, business, repayment and program eligibility requirements.
What credit score is commonly associated with SBA 7(a)?
The EIN Business Funding guidance identifies personal credit around 680 to 700+ as a common benchmark, although actual lender requirements vary.
Do 20% owners usually provide a personal guarantee?
The funding guidance states that owners with 20% or more ownership generally provide a personal guarantee for SBA 7(a) financing.
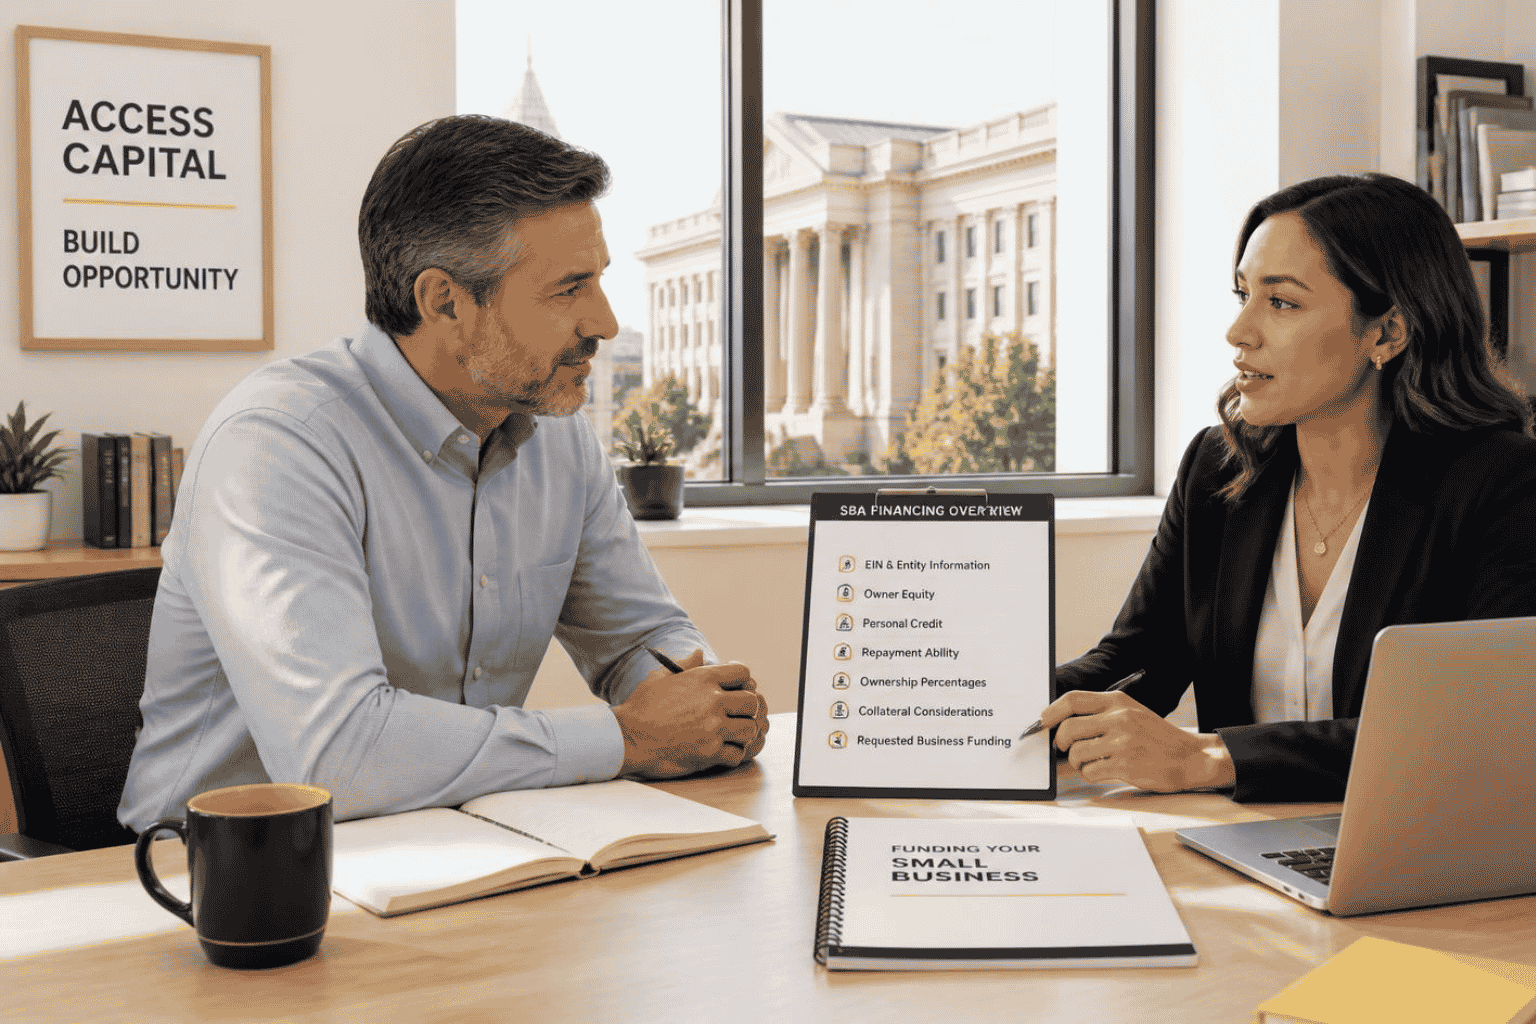 An EIN identifies the business, while SBA 7(a) eligibility can also involve owner equity, credit, guarantees and repayment ability.