CNC Machine Financing With EIN: What Manufacturers Should Prepare Before Buying Equipment
A CNC machine can increase production capacity, reduce bottlenecks or allow a manufacturer to bring work in-house, but the equipment purchase can also represent a substantial capital commitment.
Manufacturers searching for CNC machine financing with an EIN should prepare more than the company’s tax ID. A funding provider may need to understand the equipment transaction and the financial strength of the business purchasing it.
Start With the Actual CNC Machine Quote
Have a current written quotation showing the equipment being purchased and the purchase price. If tooling, delivery, installation, electrical work or training are separate, identify those costs individually.
Why Should Installation Costs Be Separated?
The CNC machine itself is a physical business asset, while electrical work, facility changes, software, tooling or professional services may represent different project expenses.
Separating the costs helps a provider understand exactly what the requested capital will finance.
Does Having an EIN Make the Equipment Loan EIN-Only?
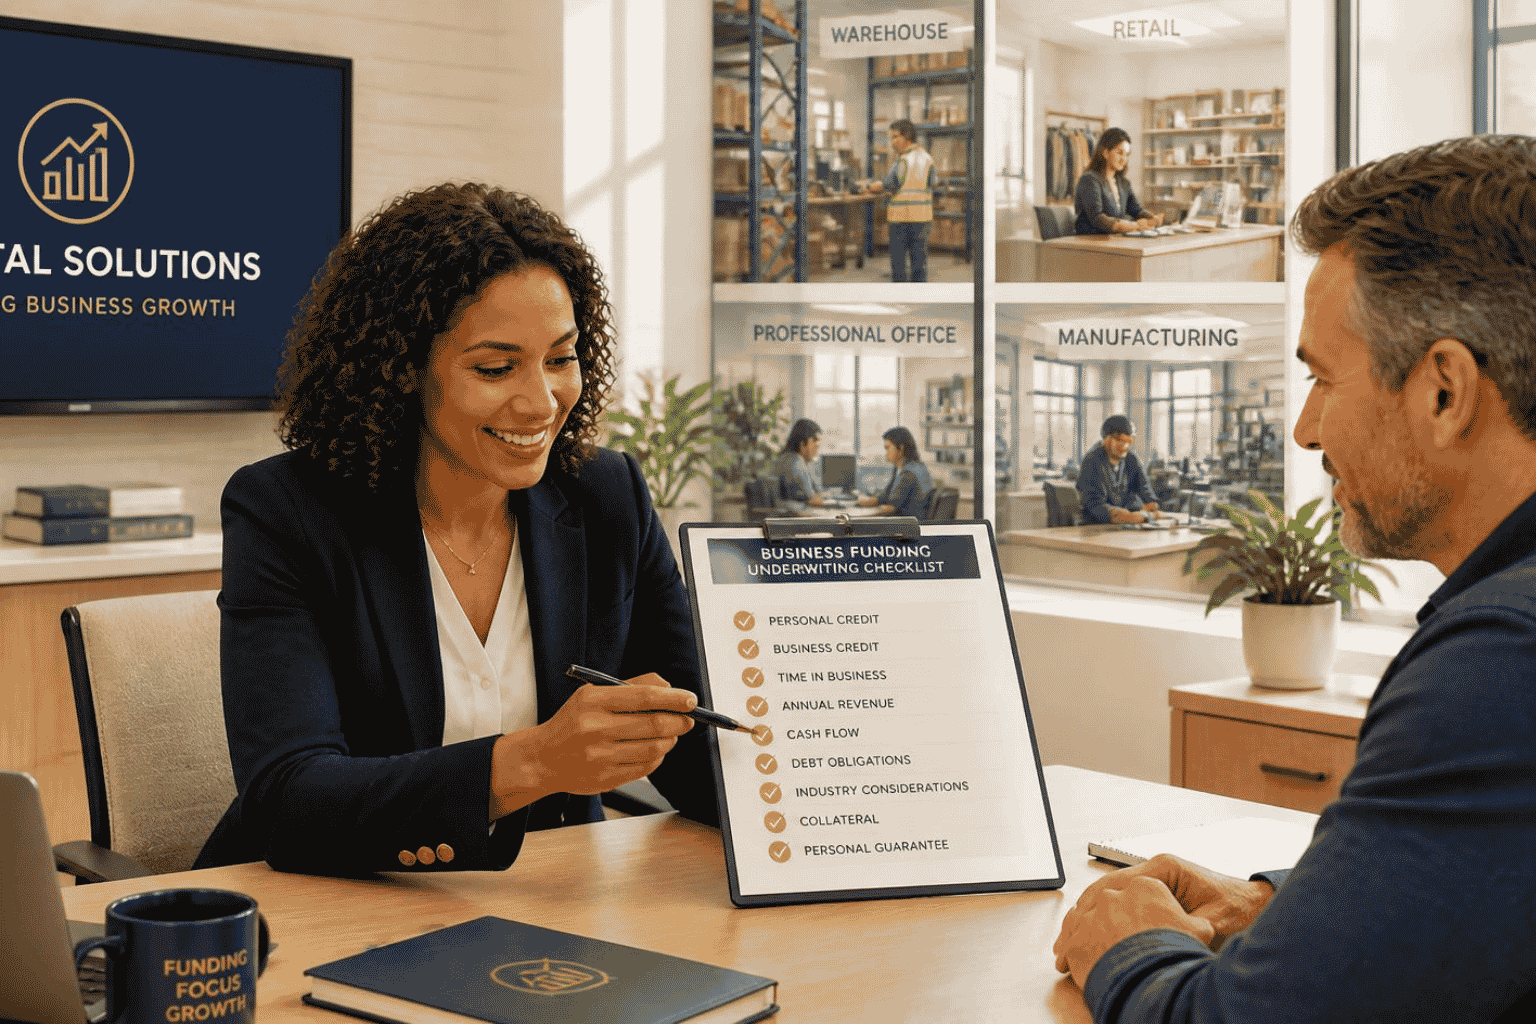
No. An EIN identifies the business, but business-financing providers may also review personal credit, business credit if established, time in business, annual revenue, cash flow, debt obligations and industry.
Why Does Existing Equipment Debt Matter?
A manufacturer may already have loans or leases tied to machinery, vehicles or other assets. Those obligations can affect the company’s overall repayment profile.
Prepare the lender name, balance, open date and applicable credit limit for existing business obligations.
What Does a Stronger Funding Profile Look Like?
The EIN Business Funding guidance describes a generally competitive borrower profile as approximately 700+ personal credit, two or more years in business, $250,000+ in annual revenue and positive, consistent cash flow.
That does not mean every CNC purchase requires those exact benchmarks, and meeting them does not guarantee approval. Equipment financing is a distinct category and individual providers may use different underwriting standards.
Could a Term Loan Be Considered for a Broader Manufacturing Project?
If the project includes more than the machine itself, a term-loan structure may also be worth evaluating depending on the provider and permitted use of funds.
Common term-loan benchmarks in the funding guidance include approximately 600 to 680+ credit, one or more years in business, $100,000+ annual revenue and positive cash flow.
Could SBA 504 Be Relevant to a Large Equipment Purchase?
Potentially. SBA 504 is designed primarily for qualifying commercial real estate, large equipment and other long-term fixed assets.
The funding guidance identifies demonstrated repayment ability and a typical down-payment range of approximately 10% to 20%, although actual requirements vary.
Do Not Hide the Working-Capital Requirement Inside the Equipment Request
A manufacturer may need more inventory, raw materials or payroll after adding production capacity. Those operating expenses should be identified separately from the CNC machine purchase.
What Should You Prepare Before Seeking CNC Financing?
- CNC machine quotation
- Tooling and accessory costs
- Delivery and installation budget
- Total amount requested
- Business formation date and EIN
- Annual business revenue
- Current credit profile
- Business bank information
- Existing business and equipment debt
- Separate working-capital requirement, if any
If your CNC purchase is moving from research to an actual equipment order, complete the EIN Business Funding Quick Lead Pre-Qualification using the equipment quote and your current business information.
FAQs
Can a manufacturer seek CNC machine financing with an EIN?
Potentially. An EIN is part of the business profile, but providers may also evaluate credit, revenue, business history, cash flow, debt and the equipment purchase.
Should installation and tooling be separated from the CNC machine price?
Yes. Separating machinery, tooling, installation and other project expenses makes the use of funds clearer.
Can SBA 504 potentially finance large manufacturing equipment?
Potentially. Large equipment is among the long-term fixed-asset uses identified for SBA 504 financing, subject to applicable lender and program requirements.
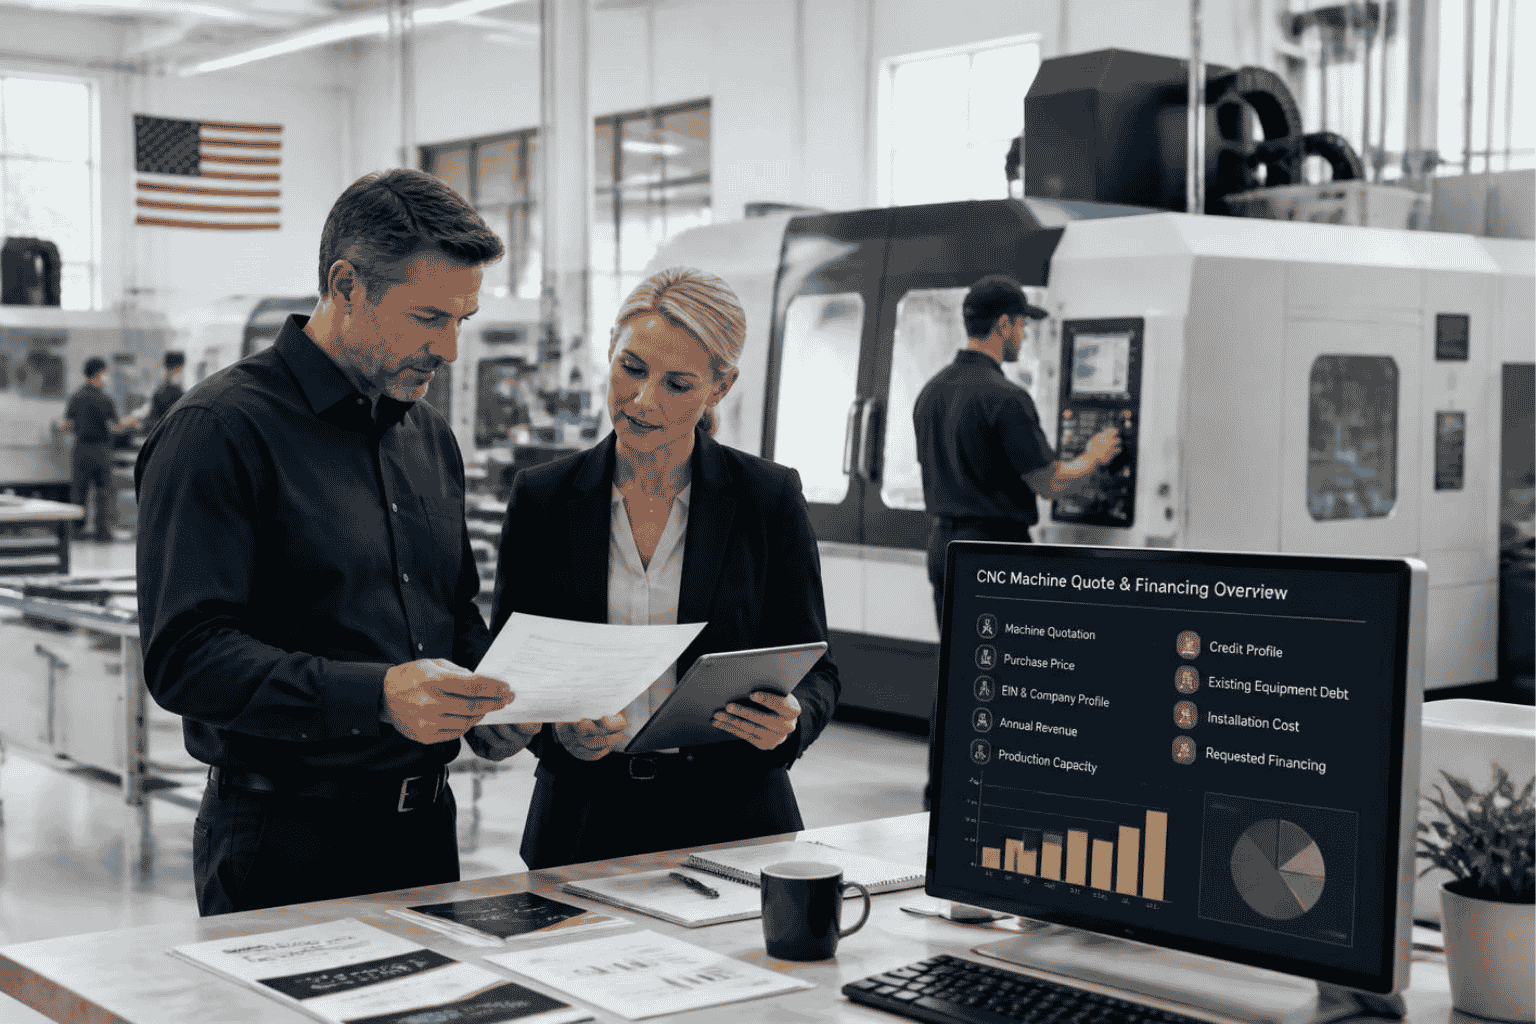 A CNC financing request should identify the machine, installed cost, borrower profile and any separate working-capital requirement.