Franchise Financing for a Second Restaurant Location: What 6+ Months and $10K Monthly Sales May Mean
Opening a second franchise location is different from financing the first one. The owner may already have operating history, actual monthly sales, employees, bank statements and a record of running the existing unit.
That existing business can make the funding discussion more concrete, but the expansion still needs a clear capital plan.
If you already operate a franchise and have identified the next location, complete the EIN Business Funding Quick Lead Pre-Qualification with your existing-location revenue and the capital required for expansion.
What Can Franchise Financing Cover?
Depending on the financing product and provider, franchise-related capital can potentially support several business needs, including franchise fees, equipment, inventory, working capital and certain expansion expenses.
The important step is to separate those costs rather than treating the entire expansion as one undifferentiated request.
Start With the Total Second-Location Budget
- Franchise or development fee
- Lease deposit or property-related expense
- Build-out and improvements
- Commercial kitchen equipment
- Furniture and fixtures
- Opening inventory
- Pre-opening payroll and training
- Initial working-capital reserve
Once these figures are clear, the owner can see which expenses may fit equipment financing, a broader business loan or working-capital financing.
Can Six Months in Business Be Enough?
Some current alternative franchise-financing programs consider businesses with approximately six months of operating history.
For an owner financing an additional location, the existing franchise’s operating history may be particularly relevant because it provides actual revenue and business-performance information.
Provider requirements vary, so six months should be viewed as a screening benchmark rather than an approval rule.
Why Does $10,000 in Monthly Sales Matter?
Current alternative-marketplace criteria for some franchise-financing options identify approximately $10,000 in monthly gross sales, or $120,000 annually, as a minimum revenue benchmark.
That does not mean a business at exactly $10,000 a month automatically qualifies. Providers may also evaluate profitability, bank activity, debt and the overall expansion plan.
What If the Owner Has Lower Credit?
Franchise financing can include several different products rather than one universal loan. Some current alternative programs state that they have options across a wide range of credit profiles.
That should not be interpreted as guaranteed financing or as evidence that credit is irrelevant. The full business and borrower profile still determines which options may be available and at what cost.
Separate Kitchen Equipment From Working Capital
A new oven, refrigeration system or other physical kitchen equipment may fit equipment financing differently from pre-opening payroll, food inventory and marketing.
Combining every cost into one category can make it harder to identify the most appropriate capital structure.
What Existing Business Numbers Should Be Ready?
The existing location can provide useful evidence of operating performance. Prepare:
- Monthly and annual revenue
- Business bank statements
- Current cash flow
- Existing loans and credit lines
- Current credit profile
- Time in business
- Existing franchise performance
How Much Working Capital Should the New Location Have?
Do not assume the new unit will reach the existing location’s revenue immediately. Payroll, food inventory, utilities and other operating expenses can begin before the new restaurant reaches normal sales volume.
A realistic opening reserve can prevent an otherwise well-financed build-out from turning into a post-opening cash problem.
Do Not Use the Maximum Available as the Expansion Budget
The expansion budget should determine the funding request—not the other way around.
Know exactly what the second location needs, which costs can be paid from owner capital and what amount remains to be financed.
Why an Existing Franchise Can Strengthen the Funding Story
An operating location gives the financing provider real numbers to review rather than relying entirely on projections. It can demonstrate whether the owner has experience managing the concept, employees, inventory and customer demand.
That operating record does not guarantee financing, but it can make the second-location request more measurable.
FAQs
Can a franchise owner seek financing for a second location?
Potentially. Existing operating history, revenue, cash flow, credit, debt and the expansion budget can all affect the financing options worth evaluating.
Can franchise financing cover equipment and working capital?
Depending on the product and provider, franchise-related financing may support equipment, inventory, working capital, franchise fees and other qualifying expansion costs.
Is six months in business and $10,000 in monthly sales enough to guarantee financing?
No. Some current alternative programs use those figures as minimum screening benchmarks, but approval and terms depend on the complete business and borrower profile.
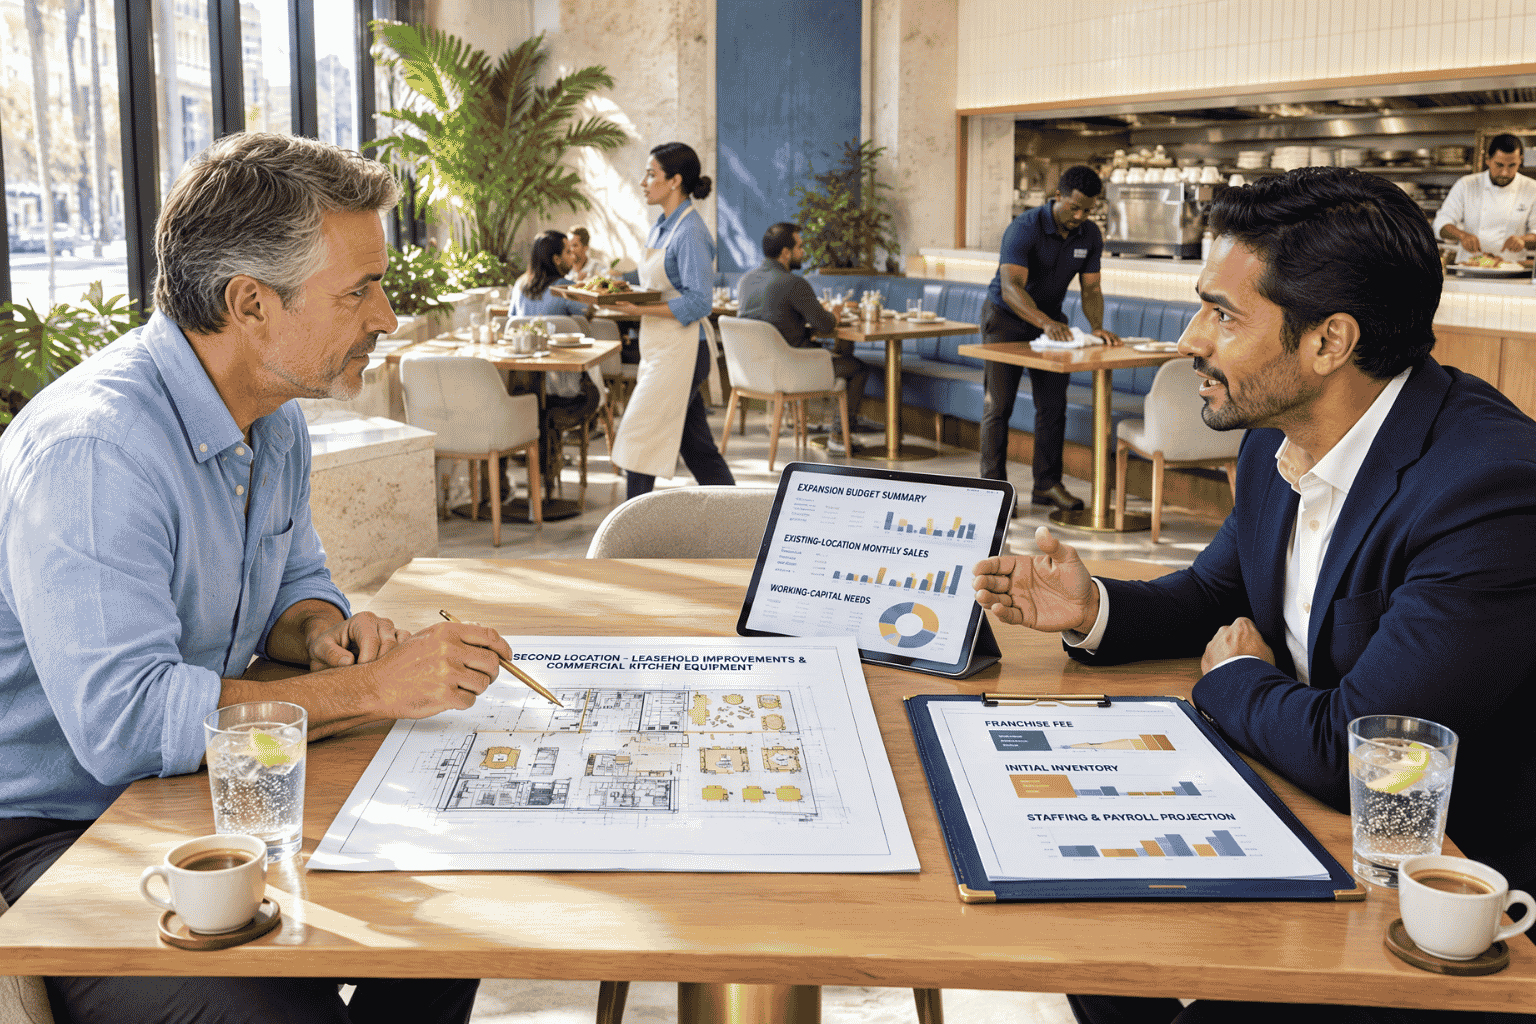 An existing restaurant's operating history can help make a second-location financing request more measurable.