SBA 7(a) Business Acquisition Loan in 2026: What Buyers Should Prepare Before Lender Review
Buyers searching for a business acquisition loan often focus first on the purchase price. A lender has a different question: can the complete transaction support repayment after ownership changes?
The SBA currently lists complete or partial changes of ownership among eligible uses of 7(a) financing. SBA’s current lending procedures also moved to SOP 50 10 8.1 effective October 1, 2026, making it particularly important for buyers to work from current lender requirements rather than assumptions based on an older transaction.
If you have already identified a business and know the approximate purchase price, buyer contribution and amount you need to finance, complete the EIN Business Funding Quick Lead Pre-Qualification.
Can SBA 7(a) Financing Be Used to Buy a Business?
Potentially. SBA identifies changes of ownership as an eligible 7(a) use of proceeds. The program can also support working capital, machinery and equipment, certain real estate needs and other qualifying business purposes.
That flexibility does not mean every acquisition qualifies. The operating business, borrower, transaction structure and ability to repay still matter.
Start With the Full Purchase Price
Know the agreed or expected purchase price before trying to determine the financing structure. Buyers should then separate the major sources of capital:
- Buyer cash contribution
- Any seller-financed portion
- Outside acquisition financing requested
- Additional post-closing working capital
This calculation reveals the real funding gap instead of treating the purchase price as the only capital requirement.
Why Does Target-Company Cash Flow Matter?
Acquisition financing ultimately has to be repaid. A business can have attractive revenue and still produce insufficient cash after operating expenses and existing obligations.
Buyers should understand historical revenue, profitability, existing debt and the cash available to support both normal operations and the proposed financing.
What Does SBA Currently Require at a High Level?
SBA states that a 7(a) borrower generally must be an operating, for-profit business located in the United States, meet applicable size requirements, be creditworthy and demonstrate a reasonable ability to repay.
SBA-backed does not mean automatic approval. The borrower works with a participating lender, and the lender determines the required application documents based on the transaction and processing method.
How Much Can a 7(a) Loan Provide?
SBA currently lists the maximum 7(a) loan amount as $5 million. The amount available for a specific acquisition can be substantially lower depending on the borrower, business cash flow, transaction and lender underwriting.
Buyers should therefore avoid structuring an offer around the program maximum.
Prepare the Buyer’s Financial Profile Too
A strong target company does not eliminate the need to evaluate the buyer. Be ready with current credit information, ownership details, available contribution, other obligations and relevant financial information.
The EIN Business Funding intake process also considers the business entity, formation information, EIN, ownership percentage, annual revenue, business banking, existing business debt and use of funds.
Do Not Forget Existing Business Debt
Identify open business loans, credit lines and business credit-card obligations associated with the target company. Understand which obligations will be satisfied at closing, refinanced, remain with the business or otherwise affect the transaction.
Existing debt can change both the purchase structure and the amount of cash flow available after closing.
Calculate the First 90 Days After Closing
A buyer can successfully finance the acquisition price and still create a liquidity problem on day one.
Payroll, inventory, supplier payments, insurance, rent, repairs and normal operating expenses continue immediately after the ownership transfer. Include a realistic post-closing cash requirement when determining the total funding need.
What Should Be Ready Before Lender Review?
- Purchase price
- Buyer contribution
- Any seller-financed amount
- Outside financing required
- Target-company revenue and cash flow
- Existing business debt
- Buyer credit profile
- Ownership structure
- Post-closing working-capital requirement
- Clear use of funds
A Financeable Deal Is More Than a Business With Good Revenue
The lender is evaluating the complete repayment picture. A realistic purchase price, adequate borrower contribution, documented business performance and sufficient post-closing liquidity can matter more than a compelling seller presentation.
For buyers, the best time to identify a funding problem is before it becomes a closing problem.
FAQs
Can an SBA 7(a) loan be used to buy an existing business?
Potentially. SBA currently lists complete or partial changes of ownership among eligible uses of 7(a) financing, subject to program and lender requirements.
What should a buyer prepare before seeking acquisition financing?
Prepare the purchase price, buyer contribution, target-company revenue and cash flow, existing debt, borrower profile, requested financing amount and post-closing working-capital requirement.
Does SBA backing guarantee that the entire purchase price can be financed?
No. The lender still evaluates the borrower, business, transaction structure and ability to repay, and the amount available depends on the complete underwriting review.
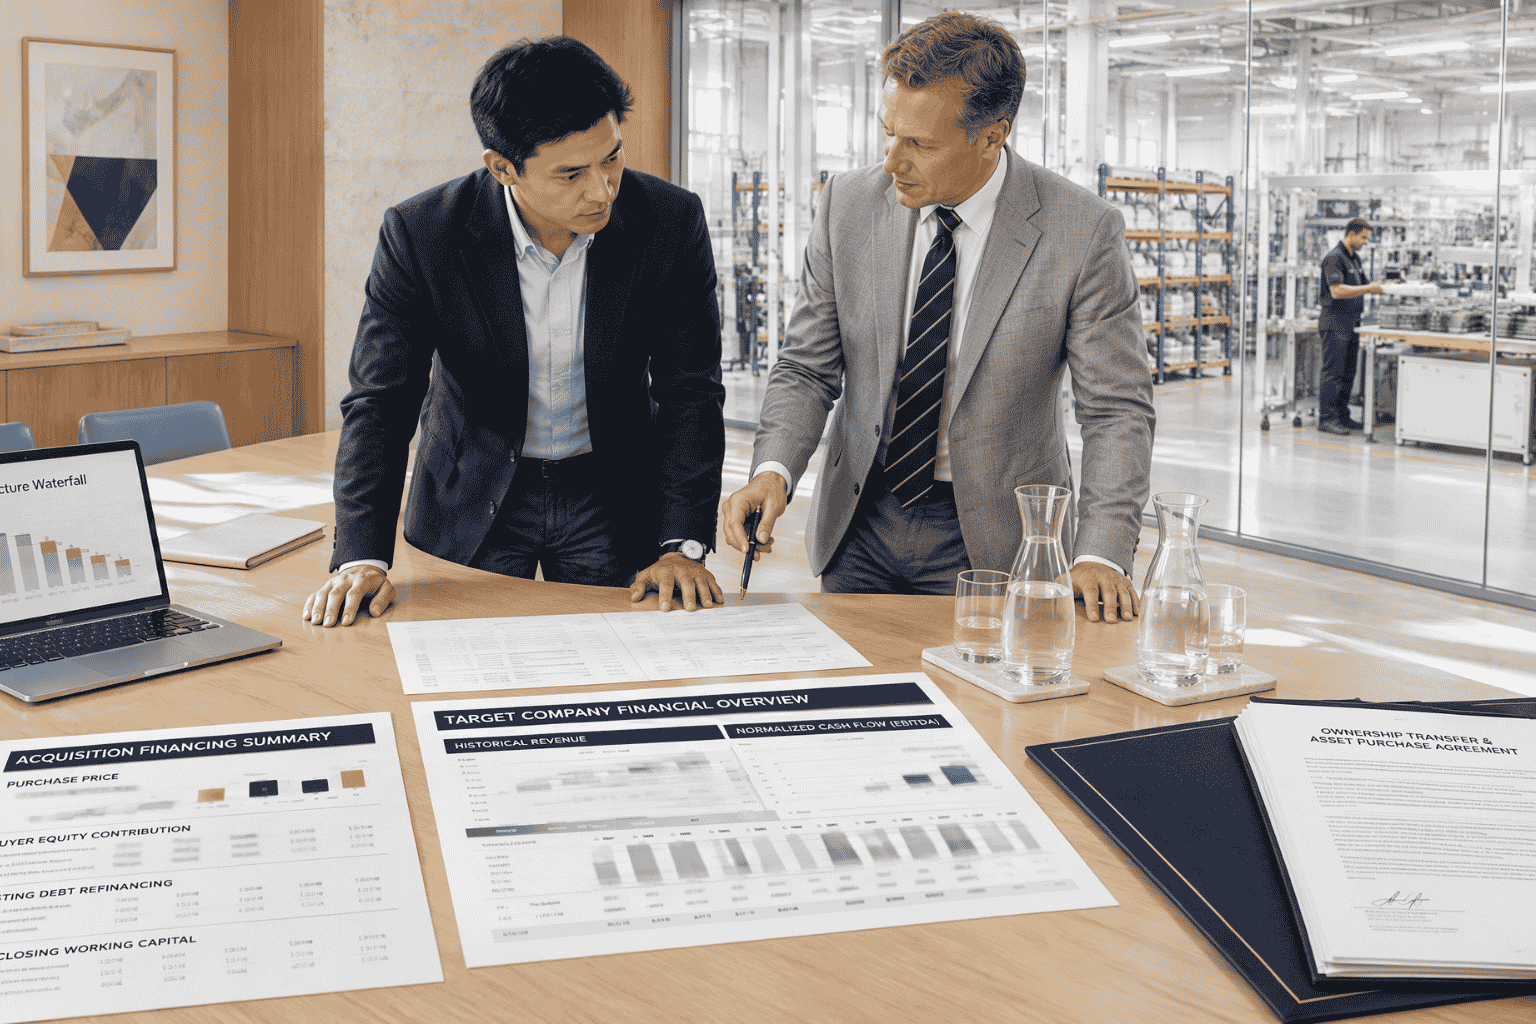 A bright U.S. acquisition setting showing a prospective buyer and funding specialist reviewing purchase price, contribution, business cash flow, existing debt and post-closing funding needs.