Business Loans With EIN: Which Funding Options Can a Small Business Qualify For?
Business owners frequently search for business loans with EIN, EIN business loans, or EIN financing because they want to borrow through the company rather than use a personal consumer loan.
An Employer Identification Number is an important part of the company’s identity.
But an EIN alone does not establish borrowing capacity.
The right financing path depends on the business, the owner, operating history, revenue, cash flow, credit, existing debt, available assets, and what the capital will be used for.
Can a Small Business Get Financing With an EIN?
Potentially.
The business can apply under its legal name and EIN, but providers may also evaluate:
- Personal credit
- Business credit
- Time in business
- Annual revenue
- Monthly bank deposits
- Cash flow
- Existing debt
- Industry
- Collateral
- Use of funds
Does “Business Loan With EIN” Mean EIN-Only Financing?
Not necessarily.
Many business loans are made to the business entity while still requiring owner information, personal credit review, or a personal guarantee.
True financing based primarily on established business credit without meaningful owner support is available in narrower circumstances.
Option 1: Equipment Financing With EIN
Equipment financing can be appropriate when the business needs:
- Commercial vehicles
- Machinery
- Construction equipment
- Medical equipment
- Restaurant equipment
- Technology hardware
The equipment itself may support the financing structure.
Providers can evaluate the asset, purchase price, business use, borrower credit, operating history, revenue, and available down payment.
Option 2: Working Capital Loan With EIN
A working capital loan may support shorter-term operating needs such as:
- Inventory
- Payroll
- Marketing
- Seasonal expenses
- Vendor payments
Qualification may depend heavily on revenue, banking activity, cash flow, credit, and existing obligations.
Option 3: Business Line of Credit With EIN
A business line of credit may be useful when the company has recurring rather than one-time capital needs.
Possible uses can include:
- Inventory purchases
- Short-term cash-flow gaps
- Seasonality
- Customer payment timing
- Operating expenses
Unlike a fixed loan, revolving credit may allow the business to draw, repay, and potentially reuse available credit subject to provider terms.
Option 4: Term Loan With EIN
A business term loan can provide a defined amount repaid according to an agreed schedule.
Potential uses can include:
- Expansion
- Renovation
- Longer-term working capital
- Major business investment
The company should compare the repayment term with the expected life and return of the investment.
Option 5: SBA Loan With EIN
SBA-backed financing may potentially support eligible:
- Working capital
- Equipment
- Business acquisitions
- Commercial real estate
- Expansion
- Certain refinancing
SBA financing generally requires detailed documentation and lender underwriting in addition to program eligibility.
Option 6: Invoice Financing With EIN
B2B businesses waiting for customers to pay completed invoices may consider receivables-related financing.
Providers can evaluate:
- Invoice amount
- Invoice age
- Customer quality
- Underlying documentation
- Existing liens
The receivable itself is important to the financing analysis.
Option 7: Acquisition Financing With EIN
Entrepreneurs and existing companies buying another business may need financing for:
- Purchase price
- Working capital
- Equipment
- Transaction expenses
The lender may evaluate both the buyer and the target company’s historical cash flow.
What Do Providers Review Besides the EIN?
The EIN confirms the business identity. It does not explain whether the company can repay debt.
Providers may look closely at:
- Annual and monthly revenue
- Business bank deposits
- Average balances
- Existing loan payments
- Credit history
- Time in business
- Industry risk
Why Time in Business Matters
An established business provides historical evidence of revenue and operating performance.
A startup may have fewer options because it has little or no business track record.
Startup funding may therefore place greater emphasis on owner credit, experience, collateral, equity contribution, or other financial strength.
Why Business Bank Statements Matter
Recent bank statements can help show:
- Deposit consistency
- Seasonality
- Average balances
- Overdrafts
- Existing financing withdrawals
Why Existing Debt Matters
A company with substantial current debt may have less room for another payment even if revenue appears strong.
Prepare a schedule of current:
- Term loans
- Lines of credit
- Credit cards
- Equipment financing
- Other business obligations
What If Your Credit Is Not Perfect?
A lower personal credit score does not automatically mean every financing option is unavailable.
Some providers also consider revenue, bank deposits, operating history, collateral, receivables, and the purpose of the funding.
However, weaker credit can affect eligibility, pricing, amount, and repayment terms.
What If You Have Strong Credit but a New Business?
Strong owner credit can help with certain products, but business loans generally still need a realistic repayment source.
The options available to a startup differ from those available to an established company with consistent revenue.
Do Not Apply for Every Product at Once
The best financing product should match the funding purpose.
Examples:
- Equipment purchase → equipment financing
- Recurring operating needs → business line of credit
- Specific working-capital requirement → working capital or term financing
- Unpaid B2B invoices → invoice financing
- Business purchase → acquisition financing
Start With Pre-Qualification, Not Random Applications
A useful pre-qualification review can organize:
- Legal business name
- EIN
- Industry
- Time in business
- Annual revenue
- Credit profile
- Recent banking activity
- Existing debt
- Requested amount
- Use of funds
This makes it easier to identify financing categories that fit the actual borrower rather than applying to products designed for a different profile.
Choose the Financing Structure Around the Business Need
The goal is not simply to obtain an approval.
The business should compare amount, term, payment frequency, financing cost, collateral, guarantees, and expected economic return before accepting capital.
EIN Business Funding can begin with the complete borrower profile and intended use of funds before potential funding paths are evaluated.
Start with your credit, time in business, annual revenue, recent bank activity, existing debt, requested amount, and exact use of funds.
Start EIN Business Funding Pre-Qualification →
Frequently Asked Questions
Can I get a business loan with only an EIN?
An EIN identifies the business, but many financing providers also evaluate owner information, credit, revenue, operating history, bank activity, cash flow, existing debt, collateral, and may require a personal guarantee.
What types of financing can a business seek using its EIN?
Depending on eligibility and business need, potential categories can include equipment financing, working capital, business lines of credit, term financing, SBA-backed financing, invoice financing, and acquisition financing.
What information should I prepare before business funding pre-qualification?
Prepare the legal business name and EIN, industry, time in business, annual revenue, credit profile, recent business bank activity, existing debt, requested amount, and a specific use of funds.
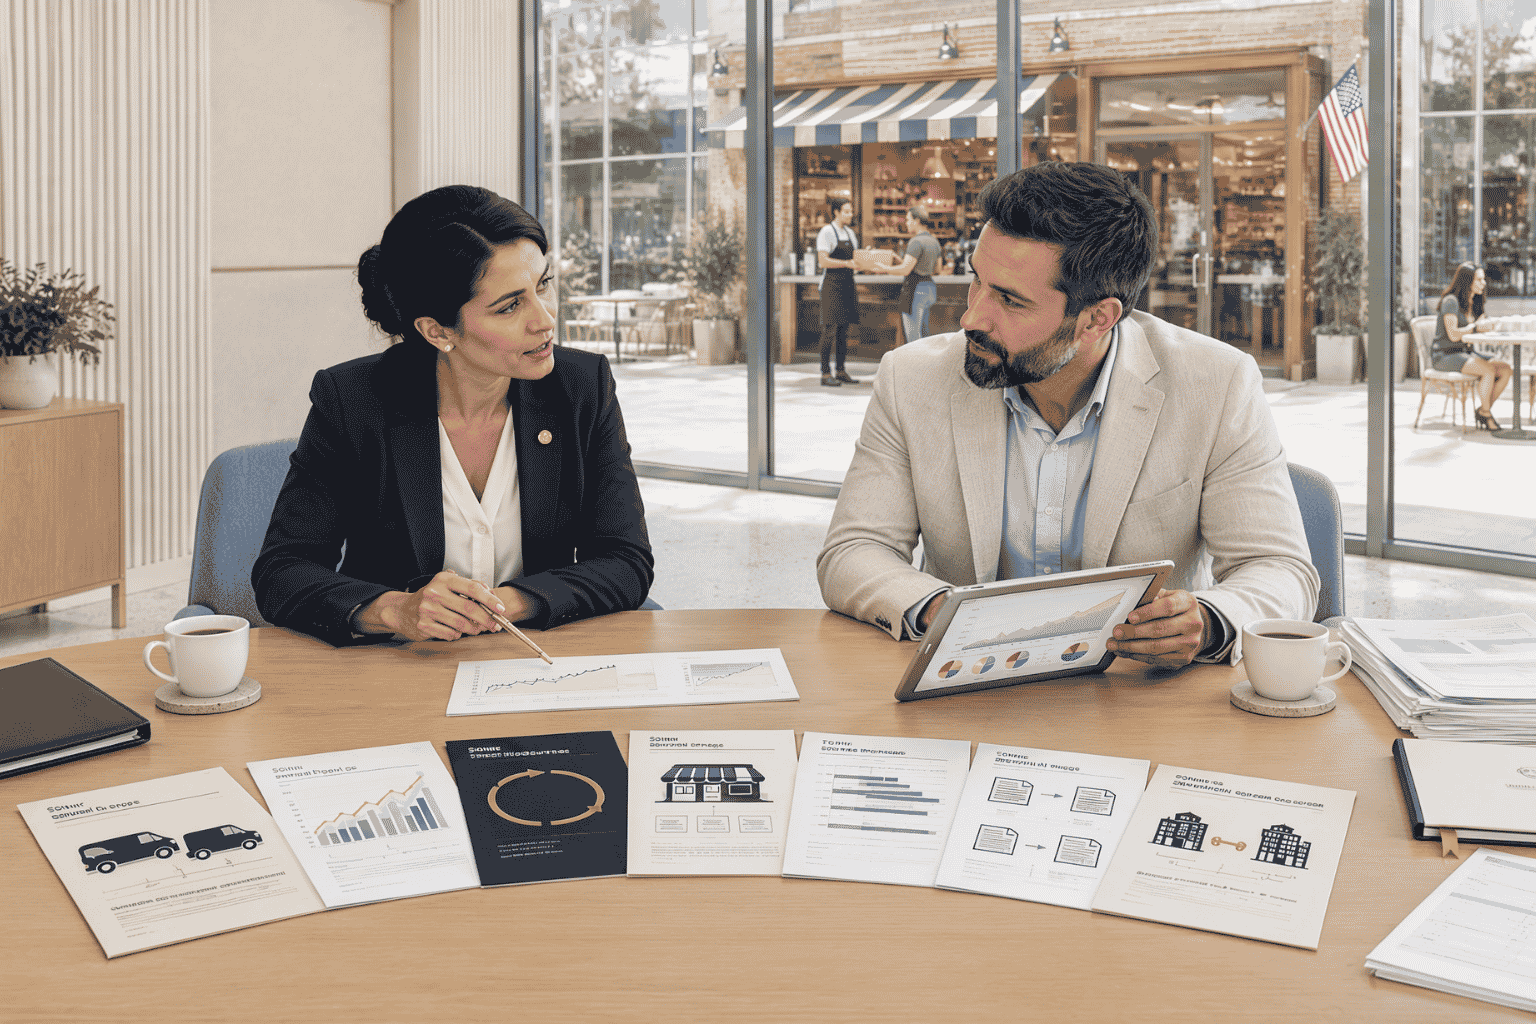 An EIN identifies the business, while funding qualification can also depend on credit, revenue, time in business, bank activity, debt, cash flow, collateral, and use of funds.