Prequalified for Business Funding? Understand What May Still Happen Before Approval
Prequalified for business funding?
That can be an encouraging step.
But it is important to understand what it does—and does not—mean.
A prequalification or initial review may suggest that the business appears to meet some preliminary criteria.
It does not necessarily mean the financing has received final approval.
What Does Business Funding Prequalification Mean?
The meaning of “prequalified” varies by financing provider.
In general, an initial review may use limited information to determine whether a business appears potentially suitable for one or more financing options.
That information may include items such as:
- Time in business
- Annual revenue
- Requested funding amount
- Use of funds
- Credit information
- Industry
- Basic business details
The provider may then decide whether the request should move to a deeper review.
Why Is Prequalification Not Final Approval?
Early information may still need to be verified.
A provider may need to review supporting documents and confirm that the business information matches the financing request.
The exact process depends on the financing product and provider.
Financial Documents May Still Be Requested
Depending on the financing option, further review may involve documents such as:
- Business bank statements
- Profit-and-loss statements
- Business tax returns
- Personal tax returns for some products
- Other financial or business records
Not every provider requires the same documentation.
Some financing products may involve less documentation, while others can require a more detailed financial review.
The Provider May Review Existing Debt
A business may already have financial obligations.
These could include:
- Business loans
- Lines of credit
- Business credit cards
- Equipment financing
- Other outstanding obligations
A provider may consider those obligations when evaluating whether the company can reasonably support additional financing.
Cash Flow May Matter Beyond Revenue
Revenue can help describe the size of the business.
Cash flow helps show how money actually moves through it.
A company can generate substantial sales while still experiencing cash-flow pressure because of payroll, supplier payments, inventory, existing debt or customer payment timing.
Depending on the financing product, the provider may therefore look beyond annual revenue and evaluate cash-flow consistency or business bank activity.
Credit May Still Be Reviewed
Credit requirements vary among financing products.
Depending on the option, a provider may consider personal credit, business credit if established, or both.
An early indication of potential eligibility does not necessarily mean that every credit-related requirement has been fully evaluated.
Business Information Must Still Be Accurate
Prequalification information should accurately reflect the business.
If the full review shows materially different revenue, operating history, debt or other information, the potential financing outcome may change.
Business owners should therefore avoid treating an initial estimate or preliminary result as a guaranteed financing commitment.
Terms May Change During Review
Even when financing remains available after a deeper review, the final structure may differ from an early estimate.
Depending on the provider and financing product, differences could involve:
- Funding amount
- Repayment period
- Payment structure
- Financing cost
- Collateral requirements
- Personal-guarantee requirements
- Other conditions
Owners should review the actual terms offered rather than relying only on an early indication.
An Offer Still Needs to Be Evaluated
Final approval does not automatically mean that a financing option is right for the business.
Before accepting financing, understand:
- How much capital will be provided
- Total financing cost
- Payment amount and frequency
- Repayment term
- Guarantees or collateral where applicable
- How the payment fits existing cash flow
The objective is not simply to obtain financing.
It is to determine whether the financing fits the business need and financial circumstances.
What About Prequalification With an EIN?
Some business owners search for business financing or loans “with an EIN” because they want financing connected to the business entity.
An Employer Identification Number can help identify the company during the application process.
However, the EIN alone does not establish final financing eligibility.
Depending on the product, providers may also evaluate credit, revenue, time in business, cash flow, debt obligations, industry and supporting documentation.
Think of the Process in Stages
A simplified business funding process may look like:
- Initial business information
- Prequalification or preliminary review, where offered
- Supporting-document review
- Verification and underwriting
- Potential financing terms
- Final decision
- Acceptance and funding, if completed
The exact sequence varies considerably among financing providers.
Prequalification Is Progress—not a Guarantee
A preliminary result can help a business understand whether a financing path may be worth exploring.
But the process is not complete until the provider finishes its review and the business understands and accepts the final terms.
EIN Business Funding provides a starting point for U.S. business owners exploring potential funding options and navigating the financing process.
Funding availability, prequalification standards, eligibility, documentation requirements, limits, costs, guarantees and terms vary by provider and applicant circumstances. Prequalification, an application, an initial review or estimated terms do not guarantee financing.
Frequently Asked Questions
Does business funding prequalification mean I am approved?
No. Prequalification generally indicates only an initial potential fit. A provider may still need to verify information, review documents and complete its financing decision process.
Can financing terms change after prequalification?
Yes. Depending on the provider and review findings, the available amount, cost, repayment structure or other terms may differ from an early estimate.
What information may be reviewed after prequalification?
Requirements vary, but providers may evaluate business bank statements, financial statements, tax information, credit, revenue, cash flow, existing debt and other business information depending on the financing product.
Can I get final business funding approval with only an EIN?
An EIN identifies the business but generally does not determine financing eligibility by itself. Providers may consider multiple financial, credit and business factors before making a final decision.
Take the Next Step
Subscribe on YouTube:
https://www.youtube.com/@enterpriseindustrynetwork
Explore EIN Business Funding:
https://www.einbf.com/get-funded/
Exit. Acquire. Invest.
Explore Enterprise Industry Network
https://enterpriseindustrynetwork.com/
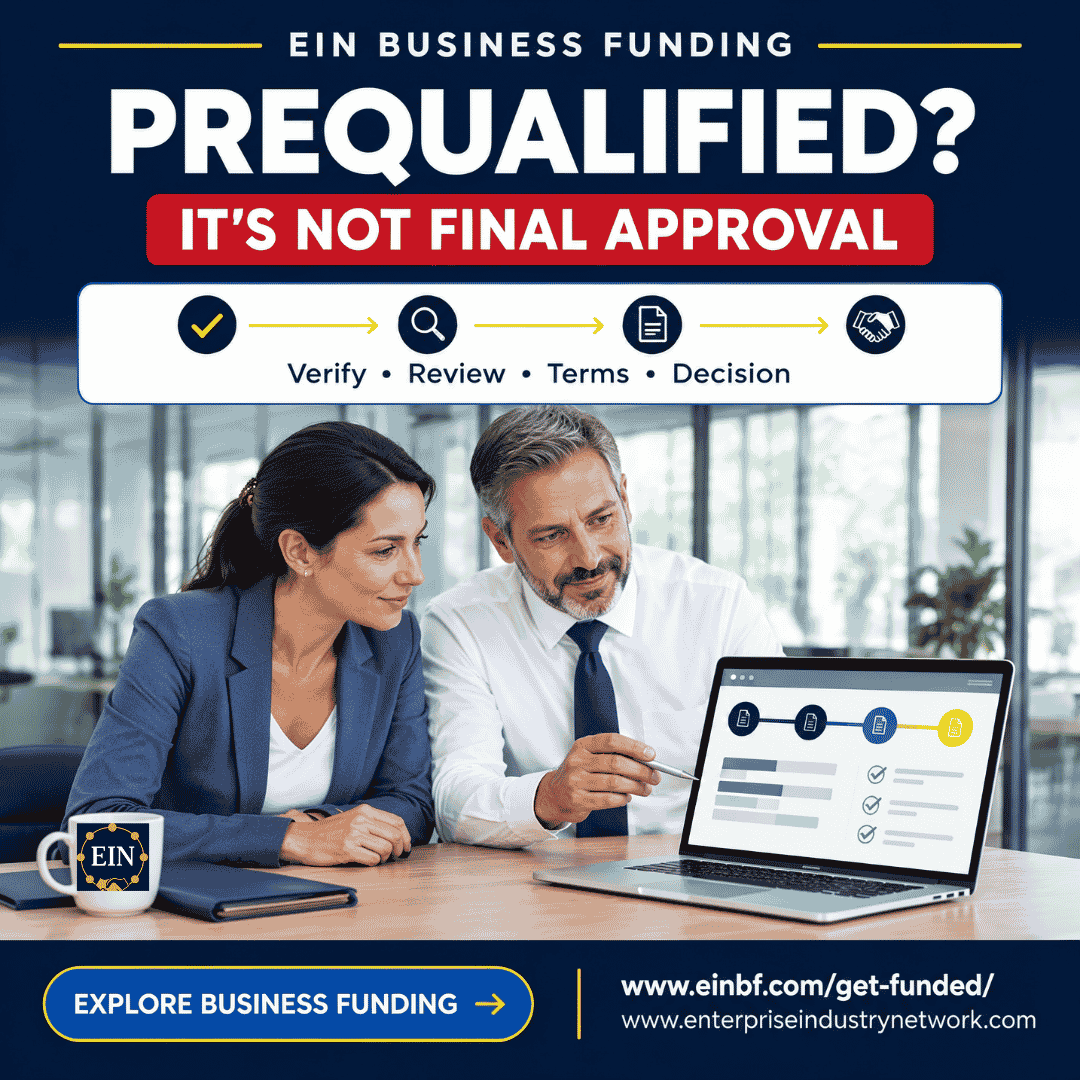 Business funding prequalification may indicate potential eligibility, but verification, underwriting and final terms may still remain.