Business Funding Readiness Scorecard: Which Financing Tier Does Your Company Fit Today?
If your business needs funding now, the fastest useful question is not “What is the best business loan?” It is “Which financing profile does my company fit today?”
If you already know your credit score, time in business, annual revenue and funding need, complete the EIN Business Funding Quick Lead Pre-Qualification.
Profile 1: New Business With Strong Personal Credit
Business credit cards may be one category to explore when the owner’s personal credit is strong. The EIN Business Funding guidance identifies approximately 740+ personal credit as a common benchmark, and established business revenue may not always be required.
Profile 2: 6–12 Months in Business With $50K+ Revenue
Working-capital financing may commonly consider approximately 600+ personal credit, six to twelve months in business and around $50,000 to $100,000 in annual revenue.
Online or alternative business loans may also consider businesses in this operating-history range, with typical credit around 600 to 680+ and approximately $50,000 to $250,000+ annual revenue.
Profile 3: 1+ Year in Business With $100K+ Revenue
A term loan may be worth evaluating when the company has approximately 600 to 680+ credit, at least one year in business, around $100,000+ annual revenue and positive cash flow.
Profile 4: Established Business With Stronger Credit
Traditional business lines of credit commonly use stricter benchmarks: approximately 720+ personal credit, one to two years in business, around $100,000 to $250,000+ annual revenue and positive cash flow.
Profile 5: Strong Overall Borrower
The funding guidance describes a generally competitive profile as approximately 700+ personal credit, two or more years in business, $250,000+ annual revenue and positive, consistent cash flow.
Organized financial statements, tax returns, an established business bank account and the absence of recent major credit problems can also strengthen the overall profile.
What Information Should You Have Ready?
Prepare your EIN, entity type, formation date, ownership percentage, annual revenue, business banking institution, current Experian FICO score, requested funding amount and use of funds.
Also list open business credit cards, lines of credit and loans with their limits, balances and open dates.
If you can identify which profile most closely resembles your business, complete the EIN Business Funding pre-qualification so the request can be reviewed against your actual numbers.
Questions Business Owners Ask
What are the most important numbers for business funding readiness?
Credit score, time in business, annual revenue, cash flow, existing debt and requested funding amount are among the most important starting points.
Do I need perfect credit to explore business funding?
No. Different financing categories use different credit benchmarks, although stronger credit generally broadens the options worth evaluating.
Does matching a funding profile guarantee approval?
No. These are general benchmarks. Final eligibility depends on the provider and complete underwriting review.
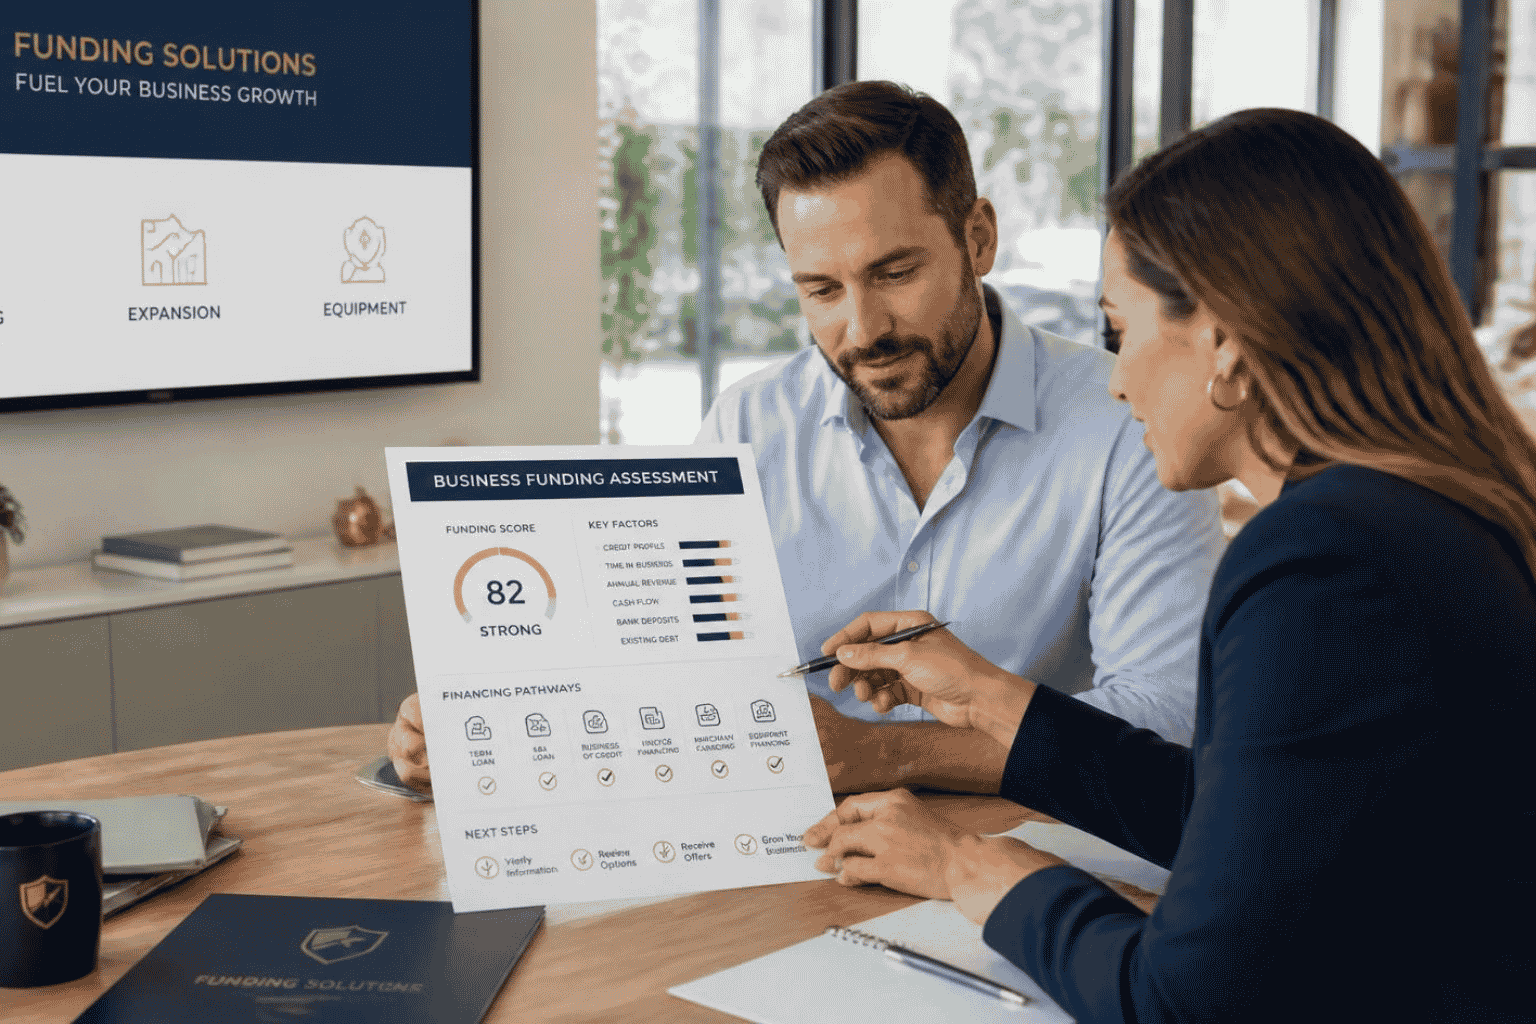 Business funding options can change significantly as credit, revenue and operating history improve.