Sales Are Growing but Cash Is Tight: What Lenders See in a Working-Capital Request
A business can report rising sales and still struggle to cover near-term expenses. That situation is common when revenue is recorded before cash is collected, inventory must be purchased ahead of demand or payroll increases before customer payments arrive.
For a funding provider, growing revenue is encouraging—but it is only one part of the financial picture.
Why Can Revenue Grow While Cash Gets Tighter?
Growth often changes the timing of cash movement. A company may need to spend more on labor, inventory, suppliers or fulfillment before it collects the corresponding customer revenue.
The result can be a temporary liquidity gap even when the underlying business is expanding.
What Will a Funding Provider Want to Understand?
Common underwriting factors include personal credit, business credit if established, time in business, annual revenue, cash flow, existing debt and industry.
For online or alternative financing, consistent deposits and bank statements can also be important.
Why Are Recent Deposits Important?
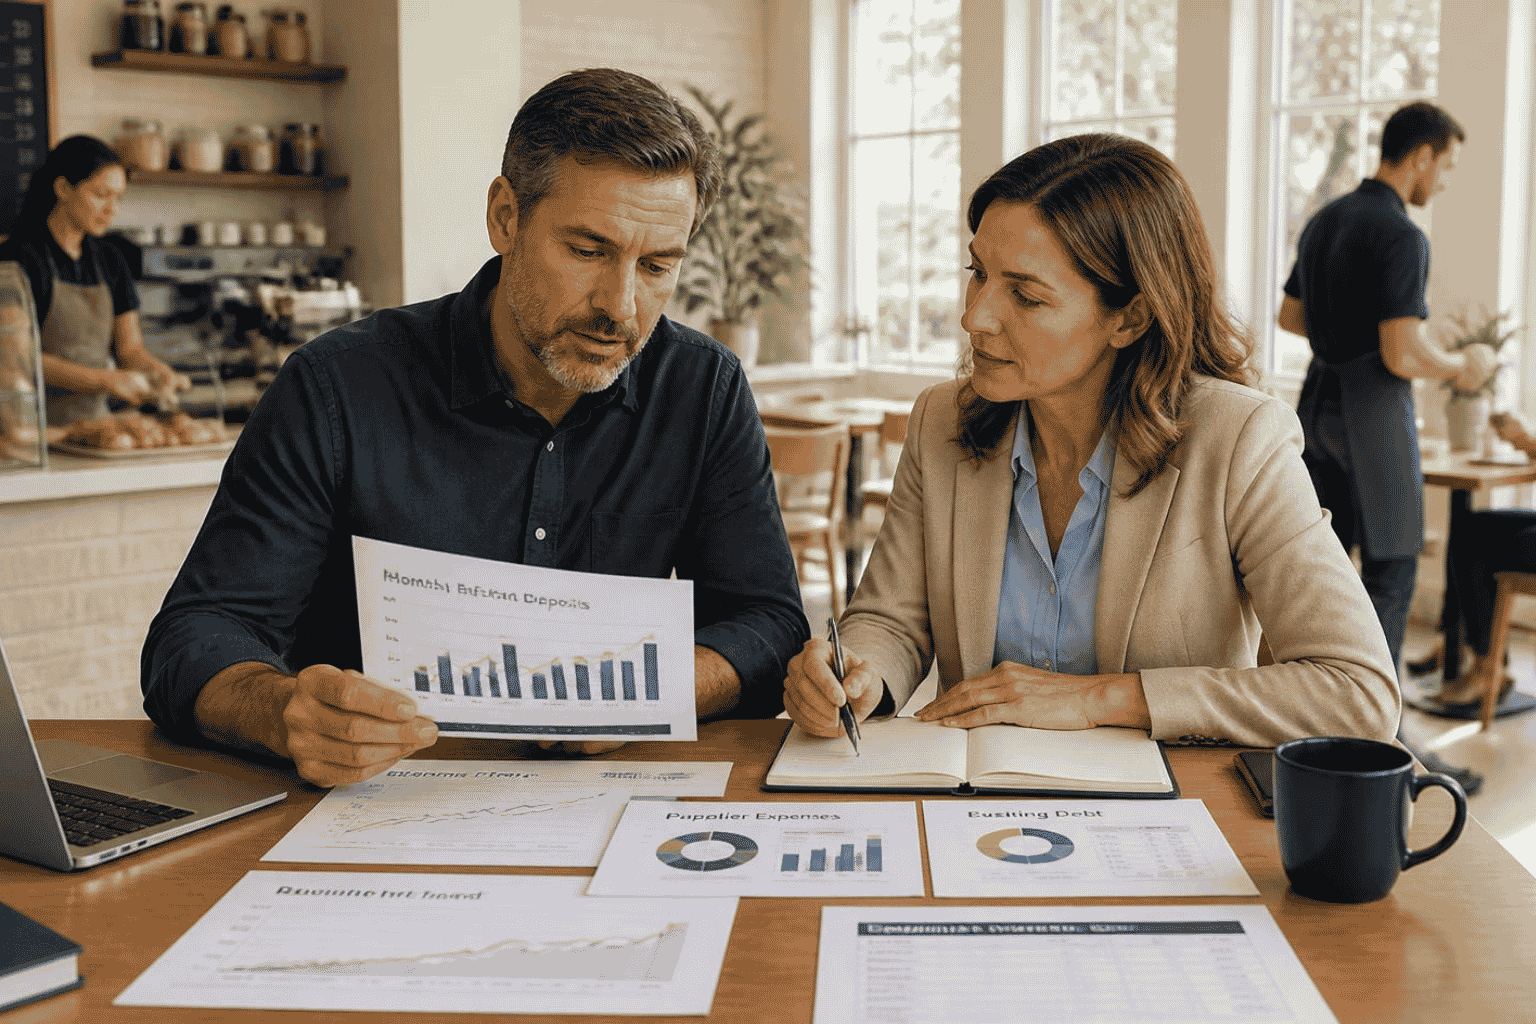
Annual revenue describes the business over a longer period. Recent deposits provide a more current view of how much cash is actually entering the business bank account.
If the company says sales are growing but recent deposits are declining, a provider may want to understand the reason.
Working Capital Should Solve a Defined Timing Problem
A stronger working-capital request explains the cash gap clearly. For example, the company may need to purchase inventory today and expects to collect customer revenue several weeks later.
The requested amount should relate to the operating requirement rather than simply reflect the maximum amount the owner hopes to obtain.
What Are Common Working-Capital Benchmarks?
The EIN Business Funding guidance identifies approximately 600+ personal credit, six to twelve months in business and around $50,000 to $100,000 in annual revenue as common working-capital benchmarks.
Different providers can apply different standards, and those benchmarks do not guarantee approval.
What If the Business Is Larger and More Established?
A more established company may have additional financing categories to evaluate.
Traditional business lines of credit commonly use stronger profiles, including approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ annual revenue and positive cash flow.
A revolving line may be relevant when the business expects recurring timing gaps rather than one isolated cash requirement.
Why Existing Debt Can Change the Decision
Even a growing company can become overextended. Existing loans, credit lines and credit-card obligations reduce the amount of cash available to support another repayment.
Prepare current balances and obligations before requesting additional capital.
What Should the Business Calculate?
- Current annual revenue
- Average recent business deposits
- Normal monthly operating expenses
- Payroll requirement
- Inventory or supplier requirement
- Existing debt payments
- Expected timing of customer receipts
- Exact working-capital gap
Do Not Confuse Growth With Unlimited Borrowing Capacity
Rapidly increasing sales can create confidence, but new financing still needs to be supported by the company’s overall repayment profile.
A useful funding request explains both why cash is temporarily tight and how normal business cash flow is expected to support repayment.
When Is Pre-Qualification Worth Considering?
If the business is generating real revenue, the cash gap is identifiable and the owner can provide current credit, banking and debt information, a focused funding review may be more useful than applying broadly to multiple unrelated products.
If growing sales are creating an active working-capital need today, complete the EIN Business Funding Quick Lead Pre-Qualification using current—not projected—business numbers.
 Growing revenue can still create a cash-flow gap when inventory, payroll and supplier costs are paid before customers pay the business.