Small Business Loan With EIN: What Changes After 1 Year in Business and $100K Revenue?
Reaching one year in business and approximately $100,000 in annual revenue can be an important funding milestone. The company now has more operating history, more banking activity and more financial information for a provider to evaluate than it did as a new startup.
For owners searching for a small business loan with an EIN, however, the important point remains the same: the EIN identifies the company, but it is not the only qualification factor.
What Changes After One Year in Business?
A longer operating history gives a funding provider more information about the company’s ability to generate revenue consistently, manage expenses and maintain business banking activity.
Some financing categories that may have been difficult to evaluate during the earliest startup period can become more relevant once actual operating history exists.
Why Is $100K in Annual Revenue a Useful Benchmark?
The EIN Business Funding guidance identifies $100,000+ annual revenue as a common benchmark for term loans, together with approximately 600 to 680+ personal credit, one or more years in business and positive cash flow.
That does not mean every business crossing $100,000 in revenue automatically qualifies. It means the profile may now align with a broader financing category than it did earlier.
Could an Online or Alternative Business Loan Also Be Relevant?
Potentially. Online or alternative small-business financing commonly uses approximately 600 to 680+ credit, six to twelve months in business and around $50,000 to $250,000+ in annual revenue as general benchmarks.
Consistent deposits and business bank statements may also be important.
What Does the EIN Contribute to the Application?
The EIN is part of the company’s legal and tax identity. It may be required or relevant during the application, but the funding provider can still evaluate the owner’s personal credit, business history, annual revenue, cash flow and current obligations.
Why Does Positive Cash Flow Matter?
Revenue and cash flow are not the same thing. A company may generate $100,000 or more in annual sales but still have limited repayment capacity if operating expenses consume most of the revenue.
Term-loan benchmarks in the funding guidance include positive cash flow because the company must support both normal operations and a new financing obligation.
What Existing Debt Should Be Prepared?
List all open business credit cards, lines of credit and business loans. Prepare the lender or card name, applicable limit, current balance and open date.
A provider may need to understand how much debt the business already carries before considering additional financing.
Could a Traditional Business Line of Credit Be Available at This Stage?
Possibly, but traditional lines generally use stronger profiles. The EIN Business Funding guidance identifies approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ annual revenue and positive cash flow as common traditional line-of-credit benchmarks.
A company at exactly one year may therefore be more competitive for some financing categories than others.
What Should a One-Year Business Have Ready?
- Legal business name and EIN
- Business formation date
- Annual business revenue
- Recent business deposits
- Business bank statements
- Current personal credit profile
- Existing business debt
- Requested funding amount
- Specific use of funds
Do Not Apply Based Only on the Revenue Milestone
The objective is to match the financing request to the complete profile. A business with $100,000 in revenue, positive cash flow and moderate debt may present differently from another business with the same revenue but inconsistent deposits or heavy existing obligations.
Use the milestone as a reason to reassess funding options—not as an assumption of approval.
If your company has reached approximately one year in business and $100,000 or more in revenue and now has an active capital need, complete the EIN Business Funding Quick Lead Pre-Qualification.
FAQs
Can a business with one year of history and $100K revenue seek a term loan?
Potentially. Those figures align with common term-loan benchmarks in the EIN Business Funding guidance, together with approximately 600 to 680+ credit and positive cash flow.
Does having an EIN and $100K revenue guarantee a business loan?
No. Providers may also evaluate credit, cash flow, deposits, debt, industry and other underwriting factors.
Can a one-year-old business qualify for a traditional line of credit?
Potentially, although traditional lines commonly use stronger profiles, including approximately 720+ personal credit, one to two years in business and $100,000 to $250,000+ annual revenue.
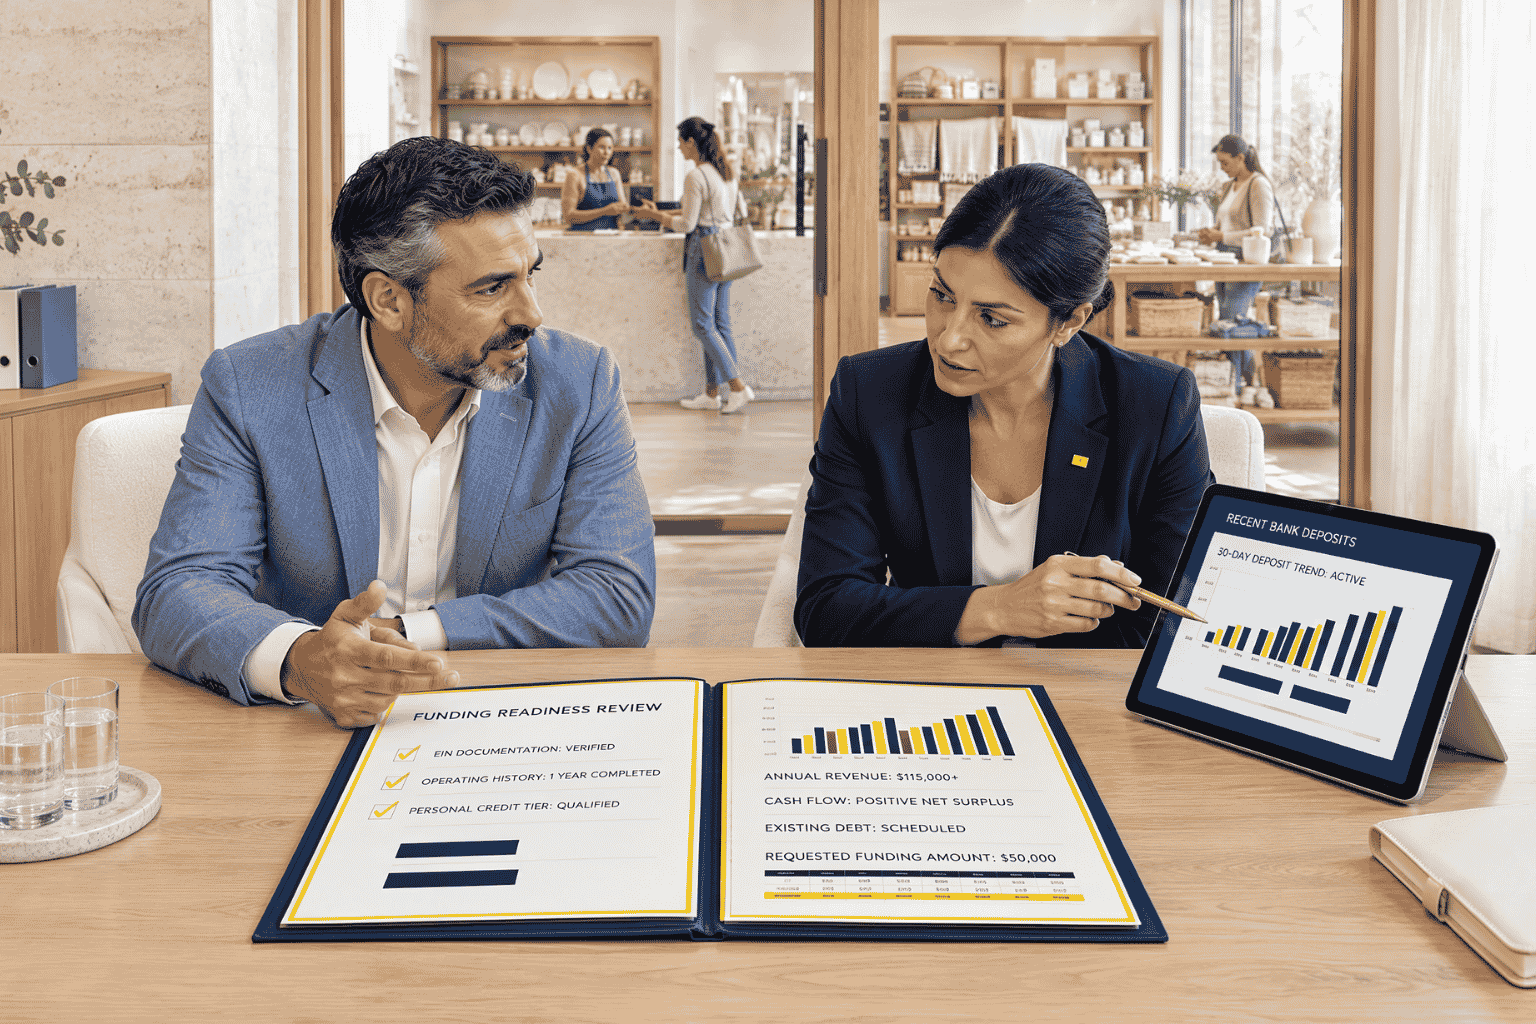 One year of operating history and $100K in revenue can broaden the financing categories worth evaluating, but the complete borrower profile still matters.