Use Cash or Get a Business Loan? How to Fund a Major Purchase Without Draining Working Capital
When a business has enough cash to make a major purchase, paying outright can appear to be the simplest choice. There is no loan application, no new repayment obligation and no financing cost.
But using a large portion of the company’s available cash can create a different problem: the business may own the asset while having too little liquidity left for payroll, inventory, supplier payments or unexpected operating expenses.
The Question Is Not Simply “Can We Pay Cash?”
A better question is: what will the company’s liquidity look like immediately after the purchase?
A business owner should understand the purchase price, available cash, normal monthly expenses, existing debt and the minimum operating reserve the company wants to maintain.
Why Preserving Working Capital Can Matter
Cash performs several jobs inside a business. It can cover payroll, inventory purchases, rent, insurance, vendor payments, taxes and unexpected expenses.
When a major purchase consumes a significant portion of that liquidity, the company may become financially tighter even if the underlying purchase was sensible.
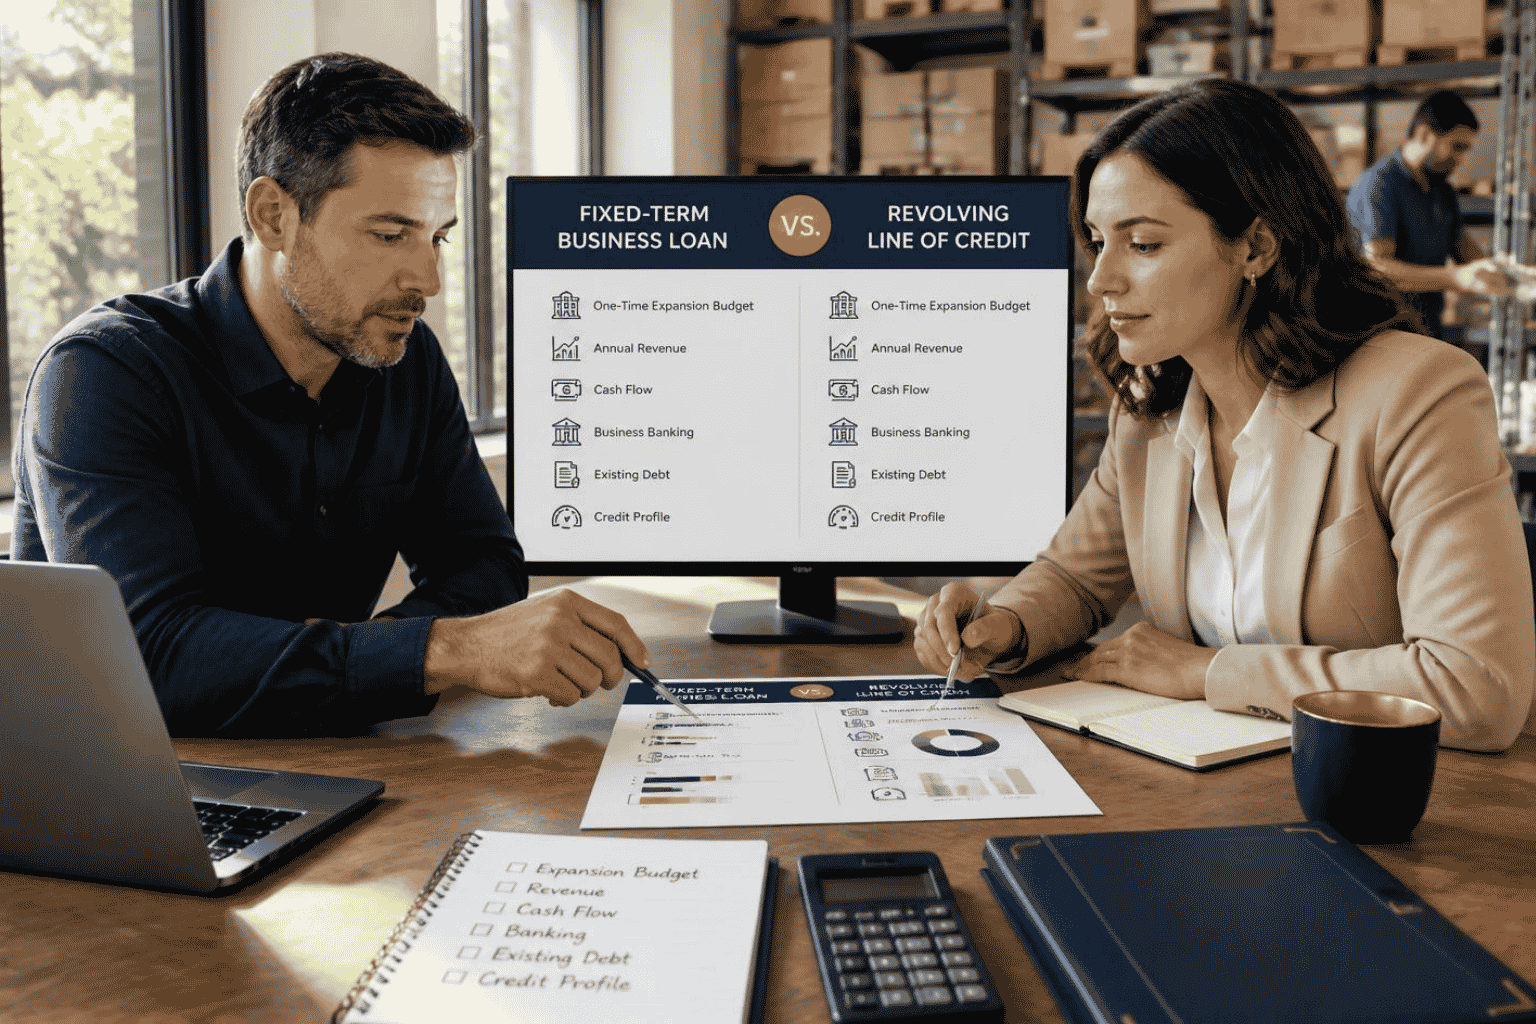
When May a Term Loan Be Worth Comparing?
A term loan may be worth evaluating when an established company has a clearly defined one-time capital requirement and wants to spread repayment over time rather than use all available cash immediately.
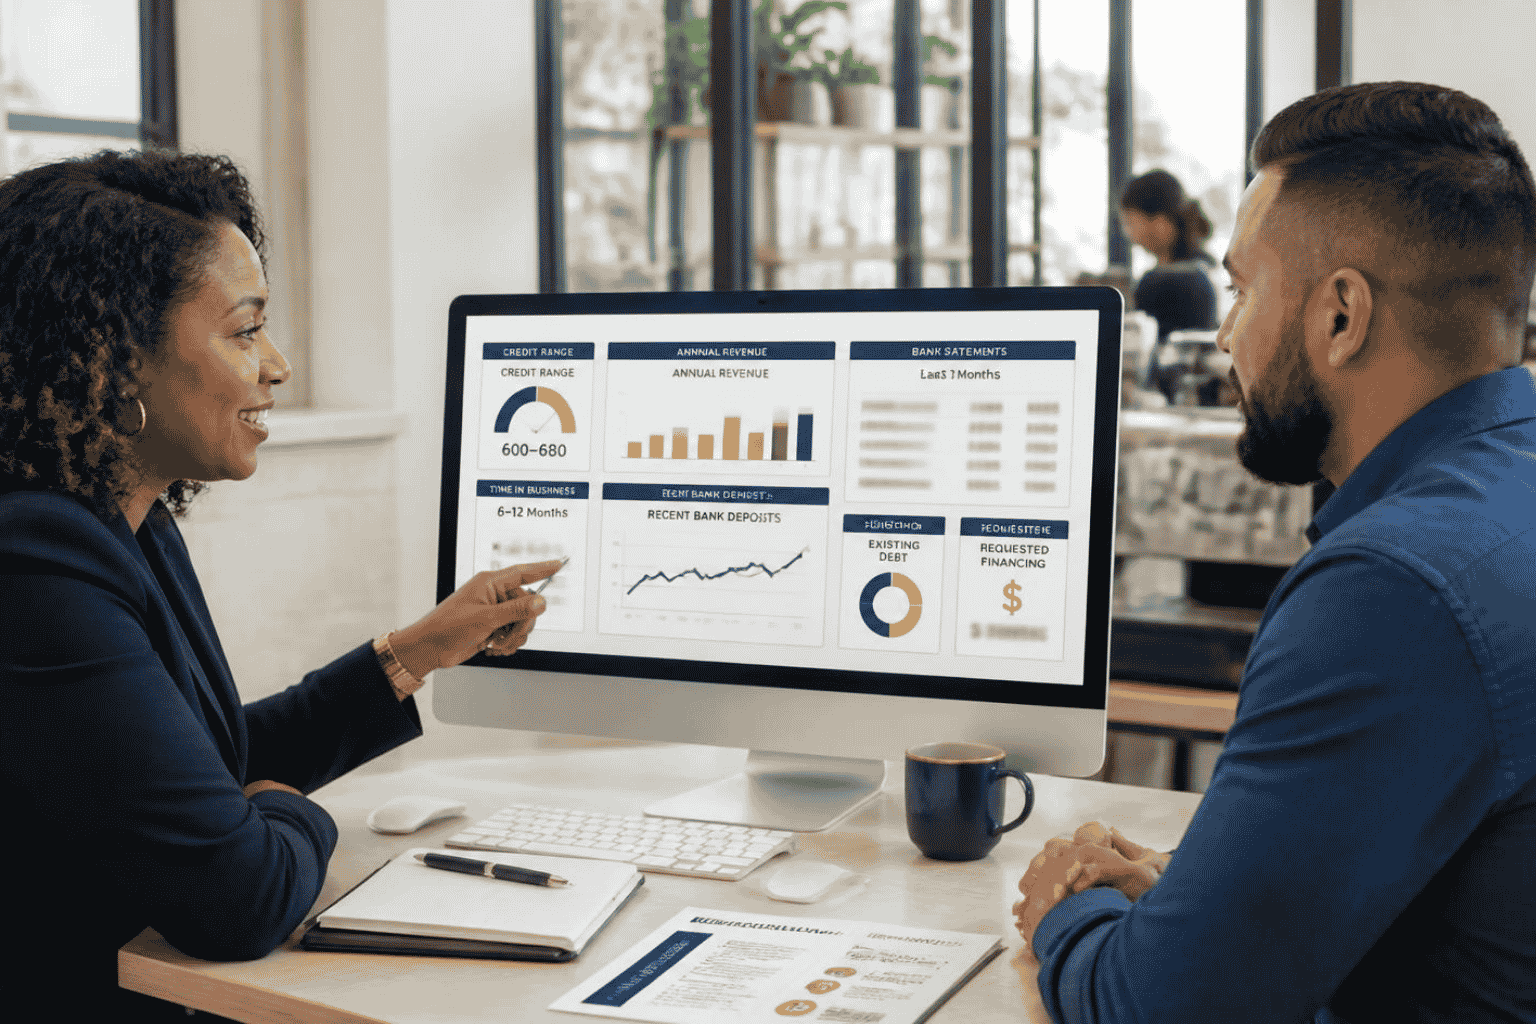
The EIN Business Funding guidance identifies common term-loan benchmarks of approximately 600 to 680+ personal credit, one or more years in business, $100,000+ annual revenue and positive cash flow.
Actual requirements vary by provider.
When May a Business Line of Credit Be More Relevant?
A line of credit serves a different purpose. It may be more relevant when the business wants revolving access to capital for recurring operating needs rather than financing one fixed purchase.
Traditional business lines of credit commonly use stronger qualification profiles. The EIN Business Funding guidance identifies approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ annual revenue and positive cash flow as common benchmarks.
What Do Traditional Lenders Commonly Review?
Traditional line-of-credit underwriting may include business and personal tax returns, profit and loss statements and business bank statements.
Lenders may also evaluate debt-service coverage, existing business debt, industry risk and cash-flow consistency.
Do Not Compare Financing Only by the Monthly Payment
A lower monthly payment does not automatically mean a financing offer is the best option. Review the complete structure, including repayment period, total financing cost, fees, collateral or guarantee requirements where applicable and the effect on future borrowing capacity.
When Paying Cash May Still Make Sense
If the purchase is relatively small compared with available liquidity and paying cash leaves the business with a healthy operating reserve, financing may not be necessary.
The decision should be based on the company’s actual cash position rather than the assumption that borrowing is always better or that paying cash is always cheaper.
When Financing May Preserve Flexibility
Financing can be worth evaluating when paying cash would materially reduce the company’s operating reserve, especially if the business expects upcoming inventory needs, seasonal expenses or other growth requirements.
That does not mean the company should automatically borrow. It means liquidity has value and should be considered alongside financing cost.
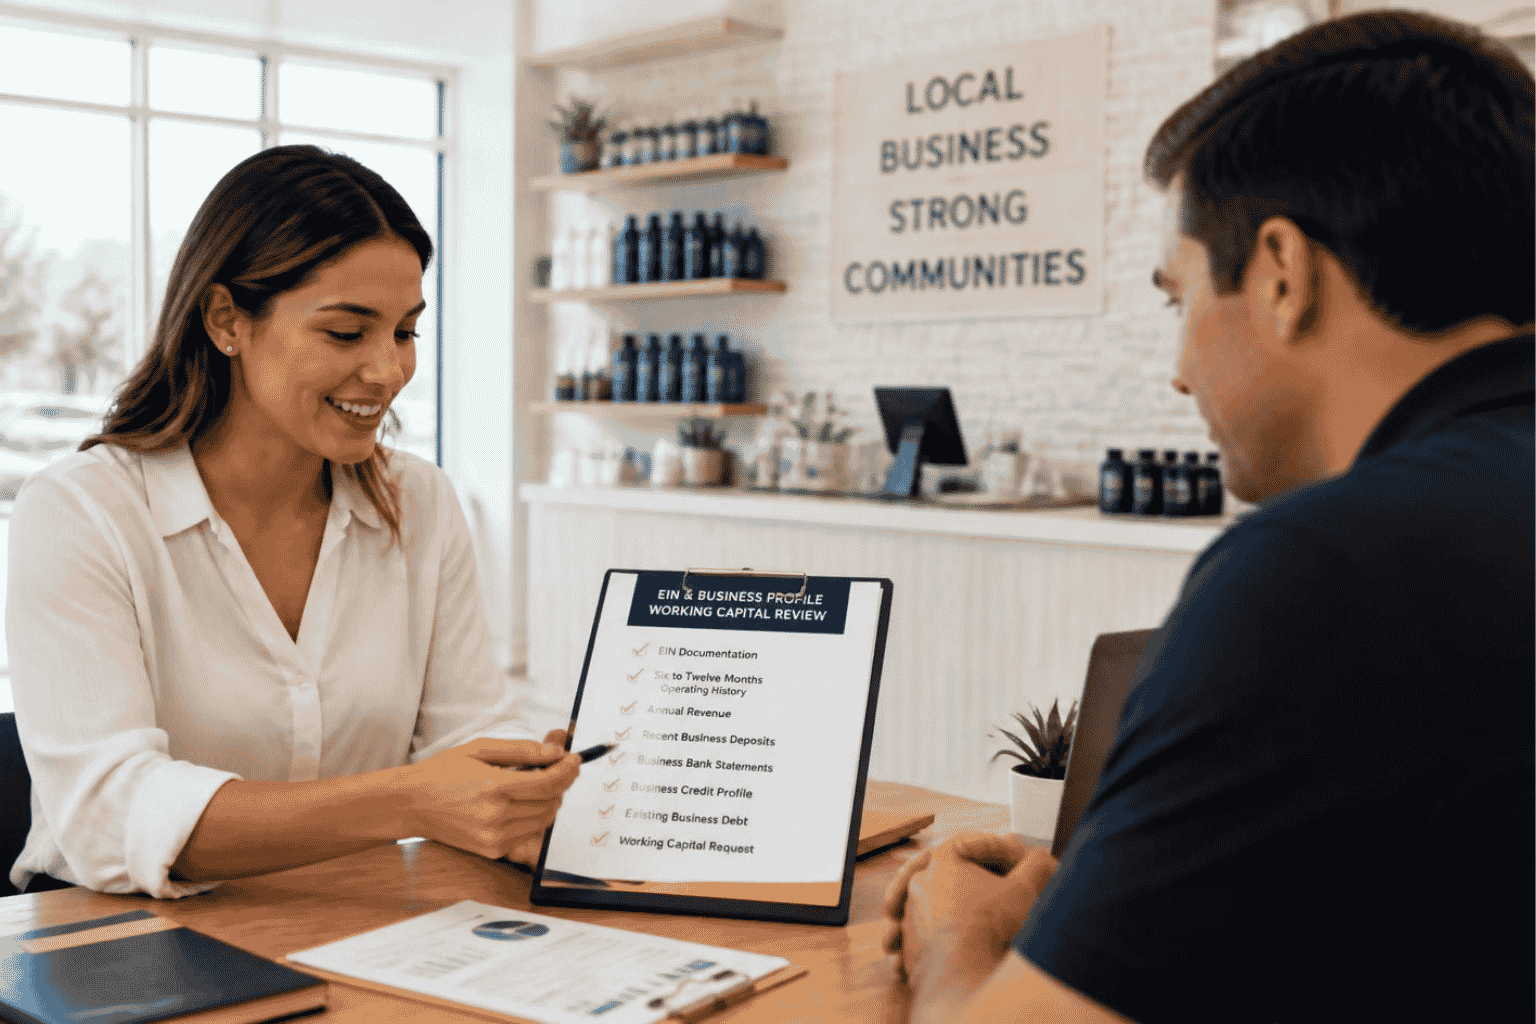
What Should Be Prepared Before Comparing the Options?
- Total purchase cost
- Available business cash
- Minimum operating reserve
- Annual revenue
- Current cash flow
- Existing business debt
- Current credit profile
- Expected future capital needs
- Exact use of funds
Use the Business Profile, Not a Rule of Thumb
A company with strong cash reserves, consistent revenue and limited debt can make a very different capital decision from a business with thin liquidity or several existing obligations.
The EIN Business Funding guidance describes a generally competitive funding profile as approximately 700+ personal credit, two or more years in business, $250,000+ annual revenue and positive, consistent cash flow, together with organized financial statements and an established business bank account.
Meeting those benchmarks does not guarantee funding, but a stronger profile may provide more financing choices to compare against paying cash.
If your business has a major purchase ready and you want to evaluate whether outside capital may preserve working cash, complete the EIN Business Funding Quick Lead Pre-Qualification with the purchase amount and current financial profile.
 Paying cash avoids new debt, but financing may help an established business preserve liquidity for ongoing operations.