Business Line of Credit vs Working Capital Loan: Which Fits a Short-Term Cash Gap?
If your business is temporarily short on cash because payroll, inventory or supplier payments arrive before customer receipts, the funding need may be short-term rather than permanent. Two categories owners often compare are a business line of credit and working-capital financing.
If the cash need is active now, complete the EIN Business Funding Quick Lead Pre-Qualification with the amount needed, annual revenue, business age and current credit profile.
When May a Business Line of Credit Fit?
A business line of credit can be useful when an established company wants revolving access to capital for recurring needs rather than one defined expense.
Traditional lines of credit commonly use stronger qualification standards.
What Are Typical Traditional Line-of-Credit Benchmarks?
The EIN Business Funding guidance identifies approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ in annual revenue and positive cash flow as common benchmarks.
Business bank statements, financial statements, existing debt and cash-flow consistency may also be reviewed.
When May Working Capital Financing Fit?
Working-capital financing may be relevant when the business needs cash for ordinary operating expenses such as payroll, inventory, supplier payments or other short-term requirements.
Common benchmarks in the funding guidance include approximately 600+ personal credit, six to twelve months in business and around $50,000 to $100,000 in annual revenue.
Which Option Is Easier to Qualify For?
Traditional bank lines of credit generally use stricter borrower profiles than many online working-capital products. However, actual approval depends on the provider and complete business profile.
What Should You Know Before Applying?
- Amount needed
- Exact use of funds
- Current personal credit score
- Time in business
- Annual revenue
- Recent business deposits
- Existing loans and credit lines
If you are trying to solve a current liquidity gap, complete the EIN Business Funding pre-qualification rather than applying broadly without first matching the funding need to your borrower profile.
FAQs
What is the main difference between a business line of credit and working-capital financing?
A line of credit generally provides revolving access to capital, while working-capital financing is often used to address operating expenses or a defined short-term cash need.
What are common traditional business line-of-credit benchmarks?
The EIN Business Funding guidance identifies approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ annual revenue and positive cash flow as common benchmarks.
What are common working-capital benchmarks?
The funding guidance identifies approximately 600+ personal credit, six to twelve months in business and around $50,000 to $100,000 in annual revenue as common benchmarks.
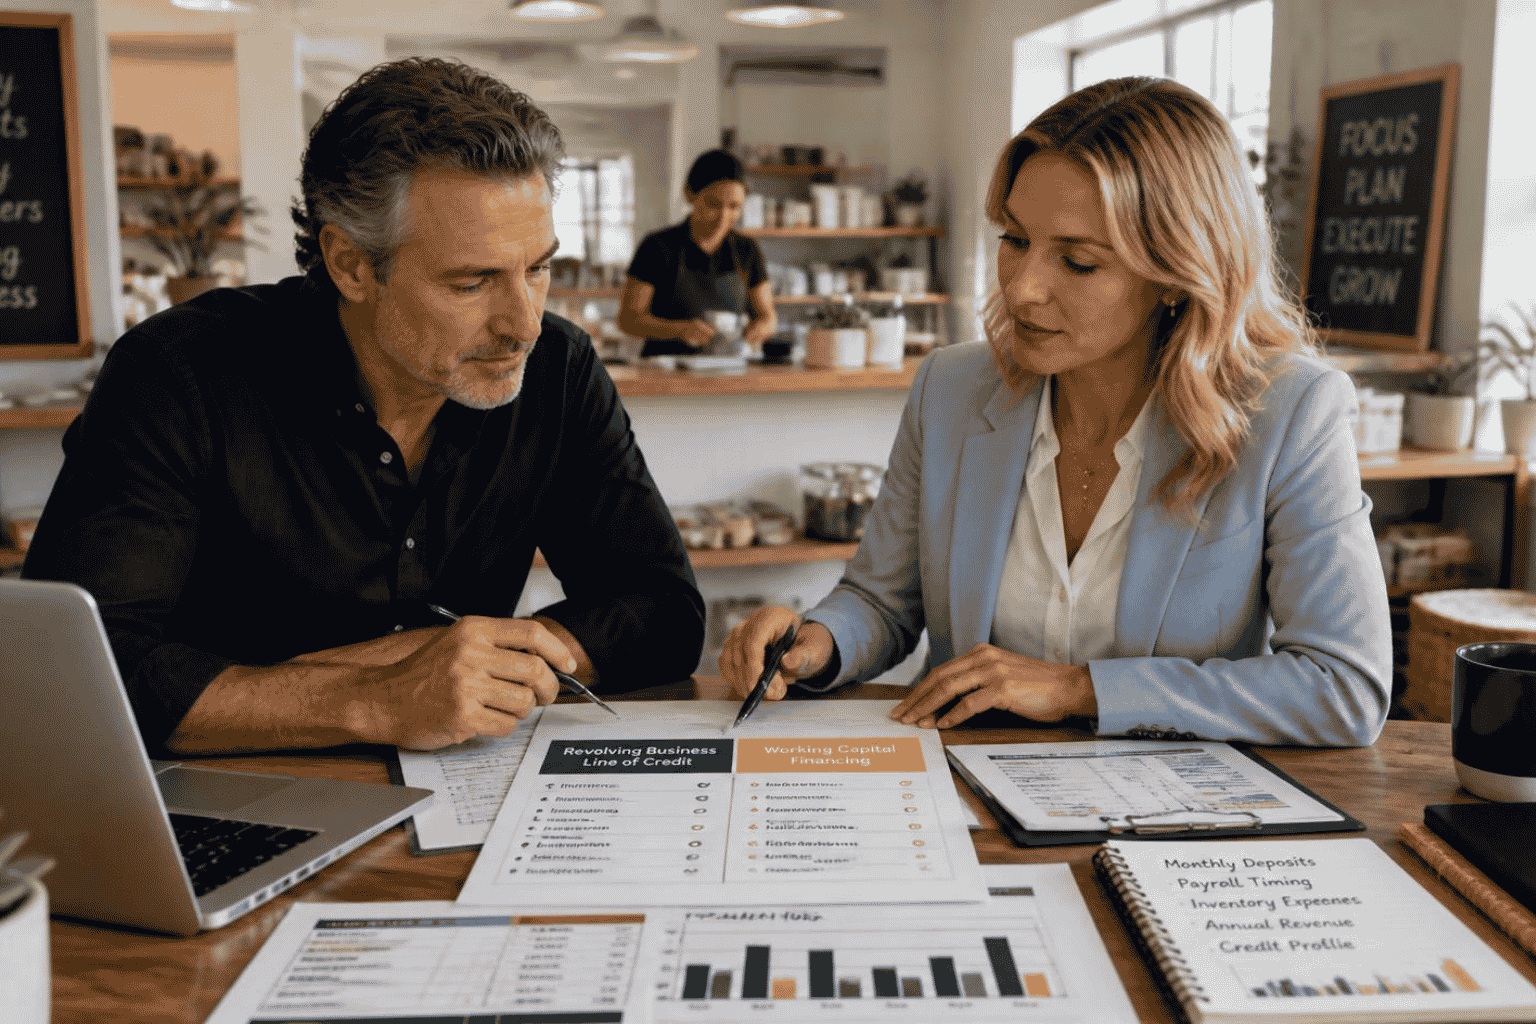 A revolving line and working-capital financing can solve different cash-flow needs and may use different qualification standards.