Business Loan Readiness: Can Your Cash Flow Support Another Loan Payment?
A business can have good revenue and still be unprepared for another loan. Funding providers often need to understand what remains after normal expenses and existing debt payments—not simply how much money comes into the company.
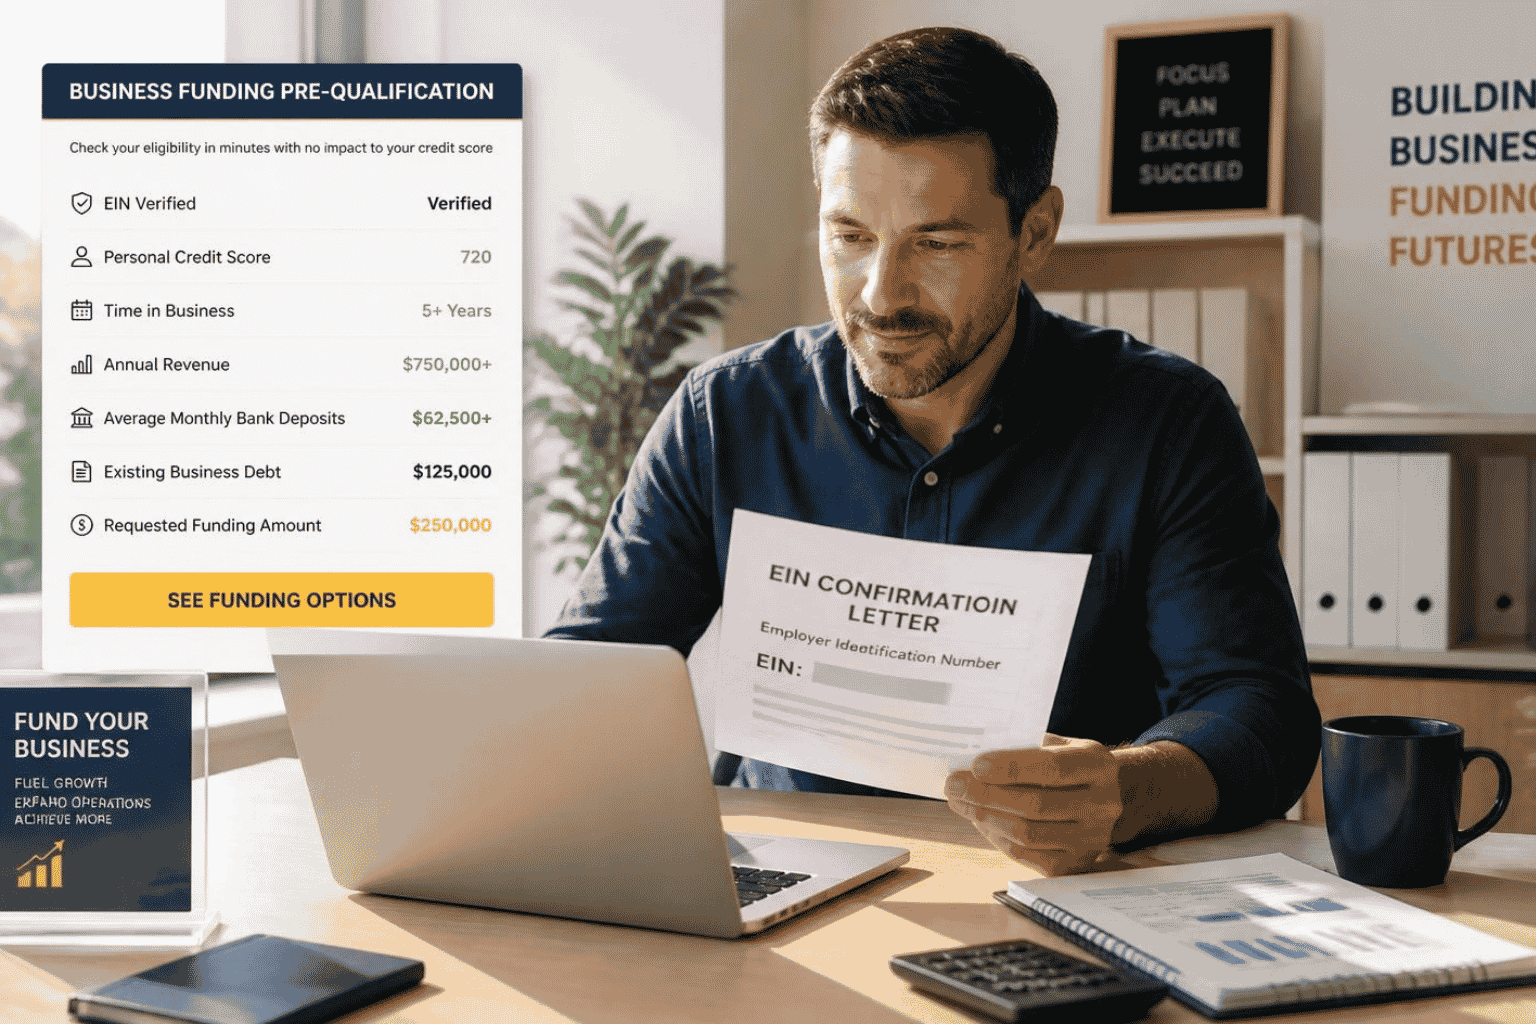
If your business currently needs capital, complete the EIN Business Funding Quick Lead Pre-Qualification with your annual revenue, current credit profile, existing debt and requested amount.
Why Is Cash Flow Important for Business Loan Readiness?
A new loan creates another repayment obligation. Positive and consistent cash flow can help demonstrate that the business has room to support financing while continuing normal operations.
How Does Existing Debt Affect the Review?
Existing loans, business lines of credit and credit-card balances can reduce the amount of cash available for another payment.
Prepare the lender or card name, credit limit, current balance and open date for each existing business obligation.
What Do Traditional Business Line-of-Credit Lenders Commonly Review?
Traditional business lines of credit commonly use stricter benchmarks, including approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ in annual revenue and positive cash flow.
Lenders may also review business bank statements, financial statements, existing debt, industry risk and debt-service coverage.
What If Your Credit or Business History Is Lower?
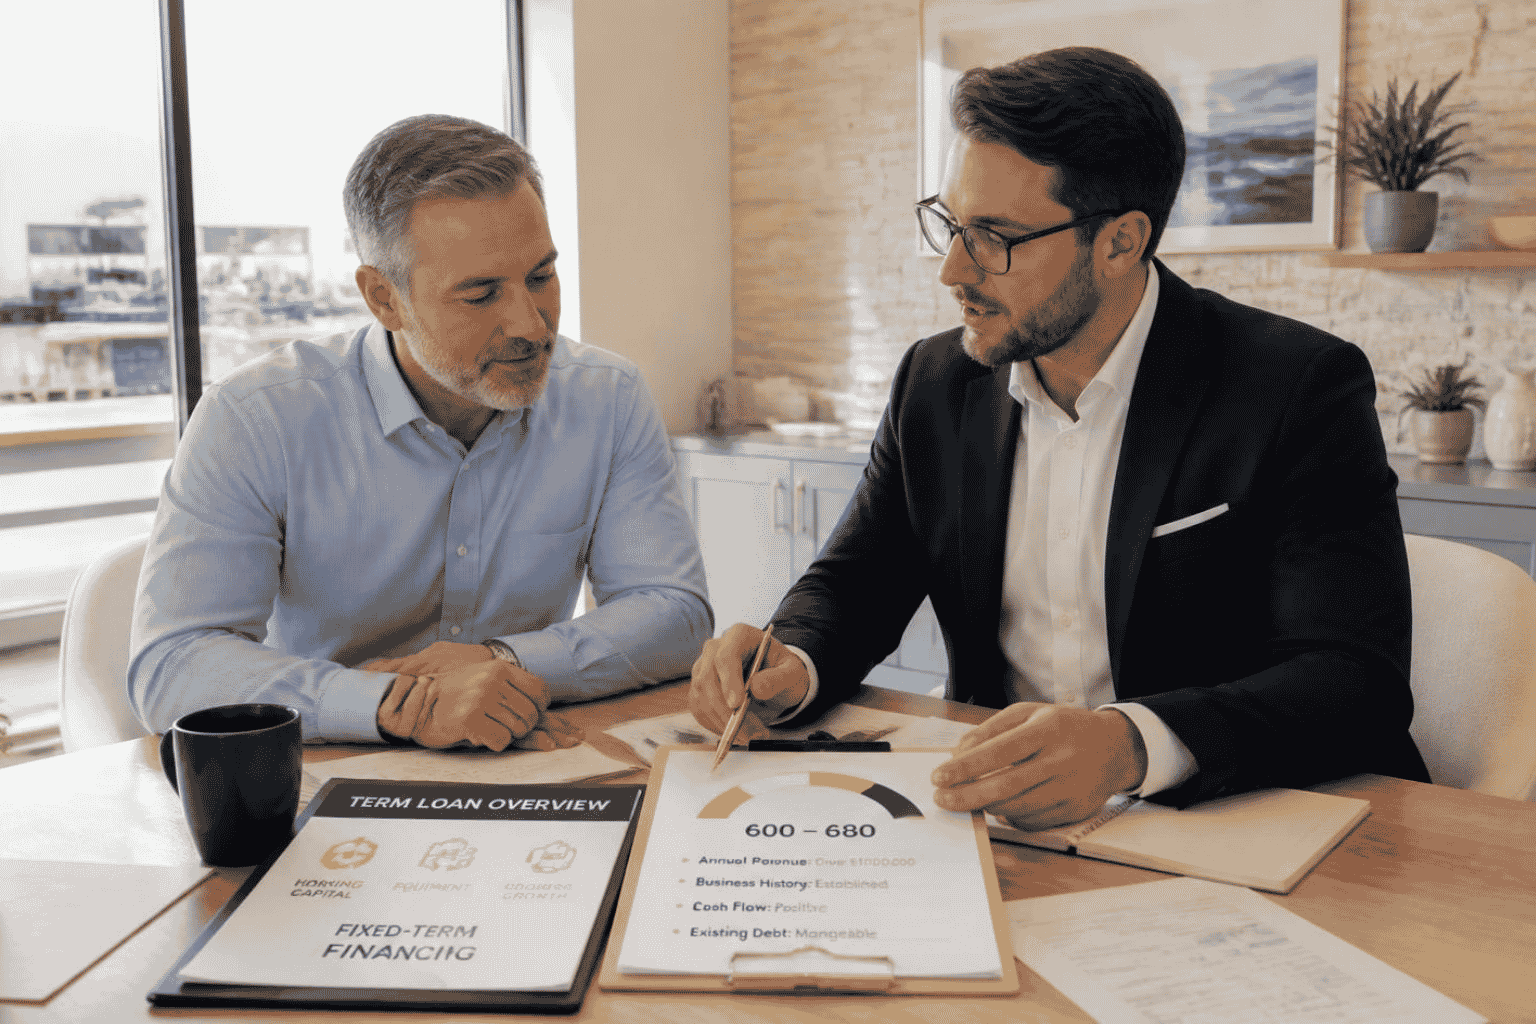
Different products use different standards. Working-capital financing may commonly consider approximately 600+ personal credit and six to twelve months in business, while online or alternative loans may use credit ranges around 600 to 680+ depending on the provider.
What Should You Know Before Requesting Another Loan?
- Current personal credit score
- Time in business
- Annual business revenue
- Typical business deposits
- Existing debt balances
- Requested funding amount
- Specific use of funds
If your company has an immediate funding need, complete the EIN Business Funding pre-qualification using your current numbers rather than relying only on annual revenue.
Questions Business Owners Ask
Is strong revenue enough to qualify for another business loan?
No. Funding providers may also review cash flow, credit, existing debt, operating history and repayment capacity.
Why does existing business debt matter?
Existing obligations affect how much cash remains available to support an additional financing payment.
Does meeting typical lender benchmarks guarantee approval?
No. Final eligibility depends on the provider and complete underwriting review.
 Revenue matters, but lenders may also evaluate cash-flow consistency and existing obligations before approving additional financing.