Comparing Business Funding Offers? Look Beyond the Interest Rate Before You Accept Capital
When business owners need capital quickly, it can be tempting to compare financing offers using one number—the quoted interest rate. But a business funding decision should consider the complete repayment structure and how it fits the company’s cash flow.
If you have an active funding need but are not sure which financing category fits your profile, start with the EIN Business Funding Quick Lead Pre-Qualification.
What Should You Compare in a Business Funding Offer?
- Amount of capital actually received
- Interest rate or financing cost
- Origination and other applicable fees
- Payment amount and payment frequency
- Repayment term
- Total repayment obligation
- Prepayment provisions
- Collateral or personal-guarantee requirements
Why Does Payment Frequency Matter?
A financing product with daily or weekly payments can affect operating cash differently from financing with monthly payments. Owners should compare the repayment schedule with normal business deposits and recurring expenses.
Why Does Your Funding Profile Affect the Offers Available?
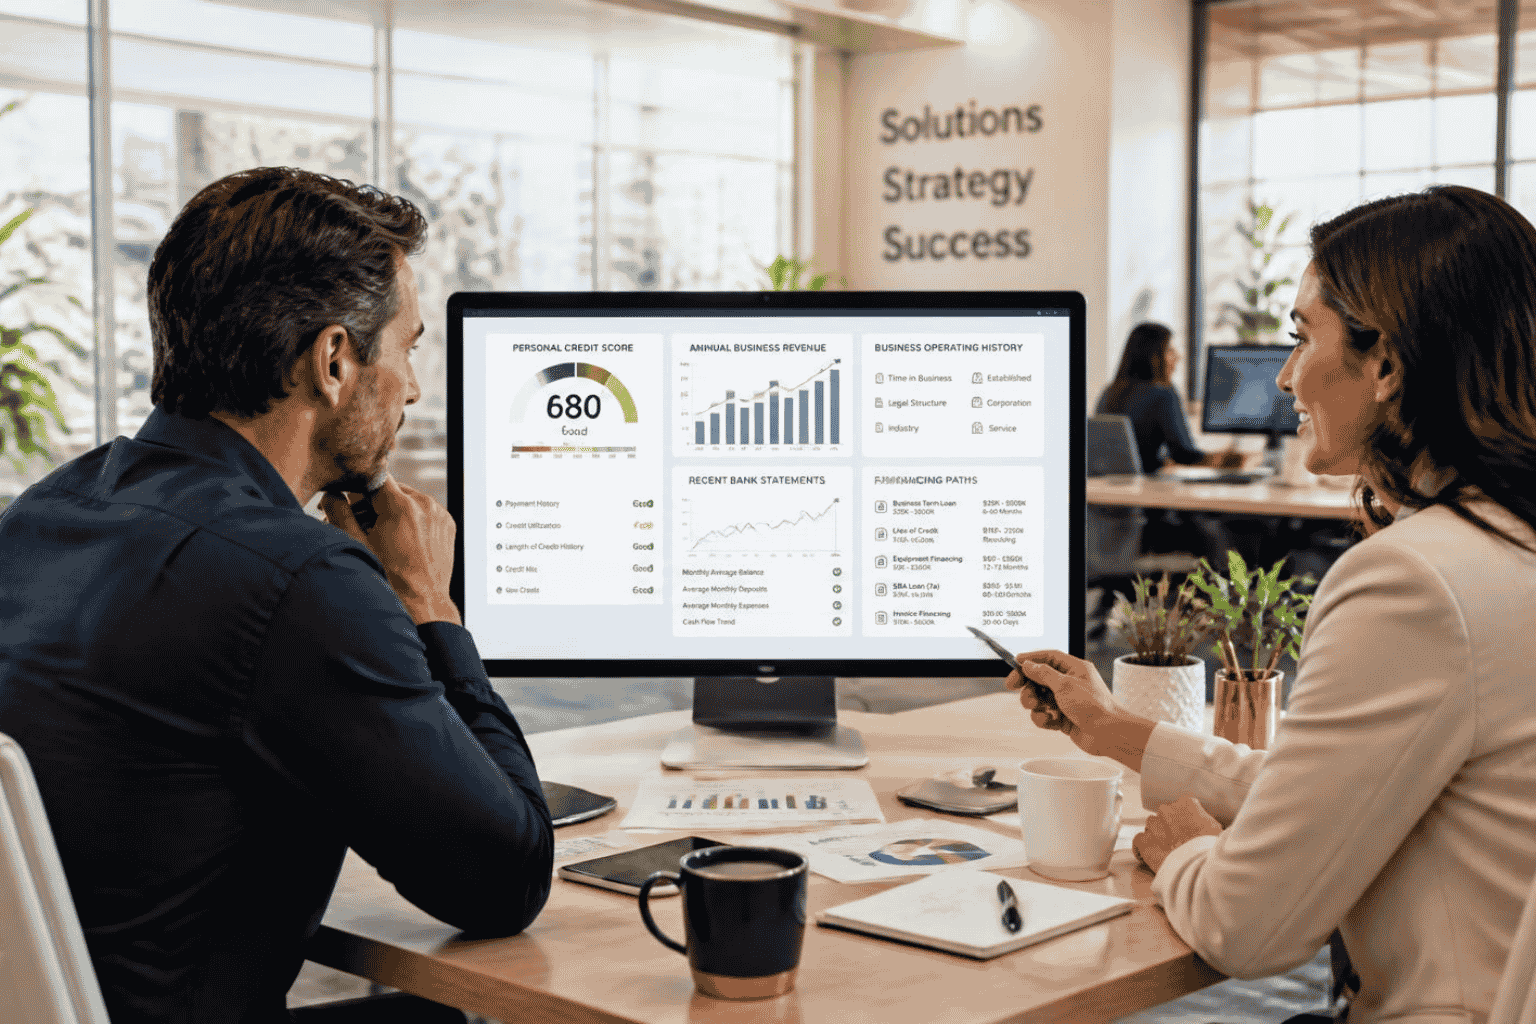
Funding providers commonly evaluate personal credit, business credit if established, time in business, annual revenue, cash flow, existing debt and industry.
Stronger profiles may have access to different financing categories than businesses with shorter operating histories or weaker credit.
What Financing Categories Should You Compare?
Depending on the business profile and use of funds, potential categories can include working-capital financing, term loans, equipment financing, online business loans, traditional lines of credit or SBA-related financing.
Should You Take the Largest Funding Amount Offered?
Not automatically. The requested amount should be tied to a clear business need and a repayment obligation the company can reasonably support.
If your business needs capital now, complete the EIN Business Funding pre-qualification using your actual revenue, credit, operating history and use of funds.
Questions Business Owners Ask
Should I choose business funding based only on the lowest rate?
No. Payment frequency, term, fees, total repayment and cash-flow impact should also be reviewed.
Why do different businesses receive different funding options?
Providers may evaluate credit, revenue, operating history, cash flow, existing debt, industry and other underwriting factors.
Should I borrow the maximum amount available?
Not necessarily. The financing amount should match a defined business need and a repayment level the company can support.
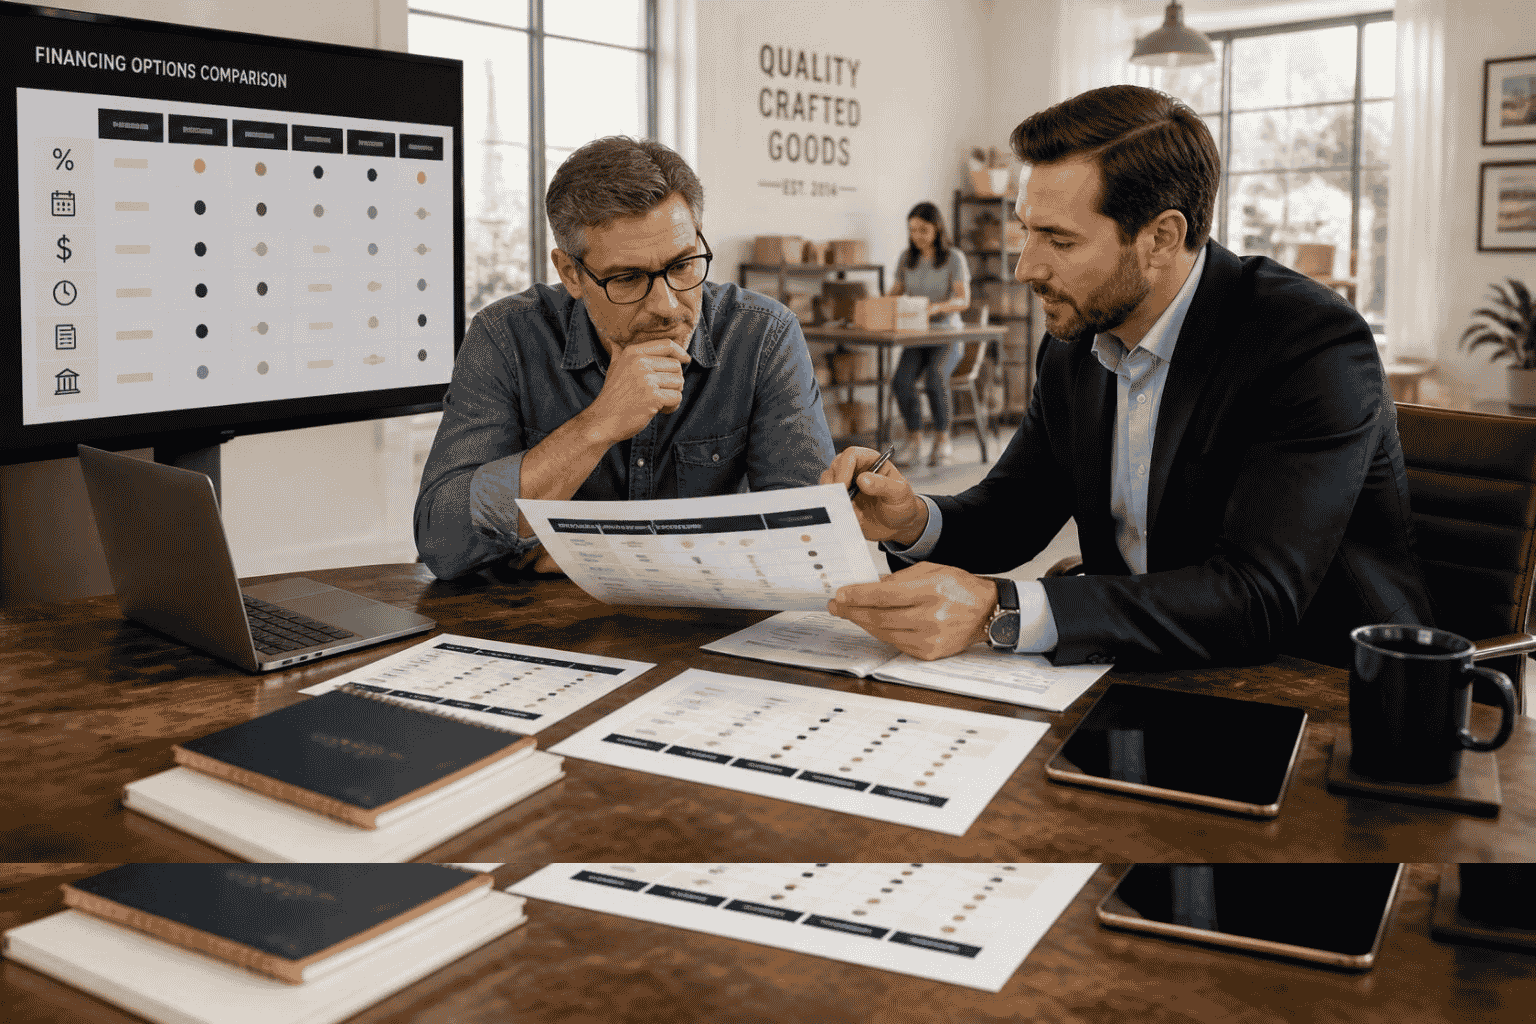 A business financing offer should be evaluated by its complete repayment structure—not the quoted rate alone.