Government-Backed Business Financing: What to Prepare Before Exploring an SBA Loan
Government-backed business financing can be attractive to established companies that need capital for growth, acquisitions, equipment or other qualifying business purposes. But an SBA-related loan still requires lender underwriting and a complete borrower profile.
If you are exploring SBA financing or another business funding option, start with the EIN Business Funding Quick Lead Pre-Qualification.
What Should an SBA Borrower Have Ready?
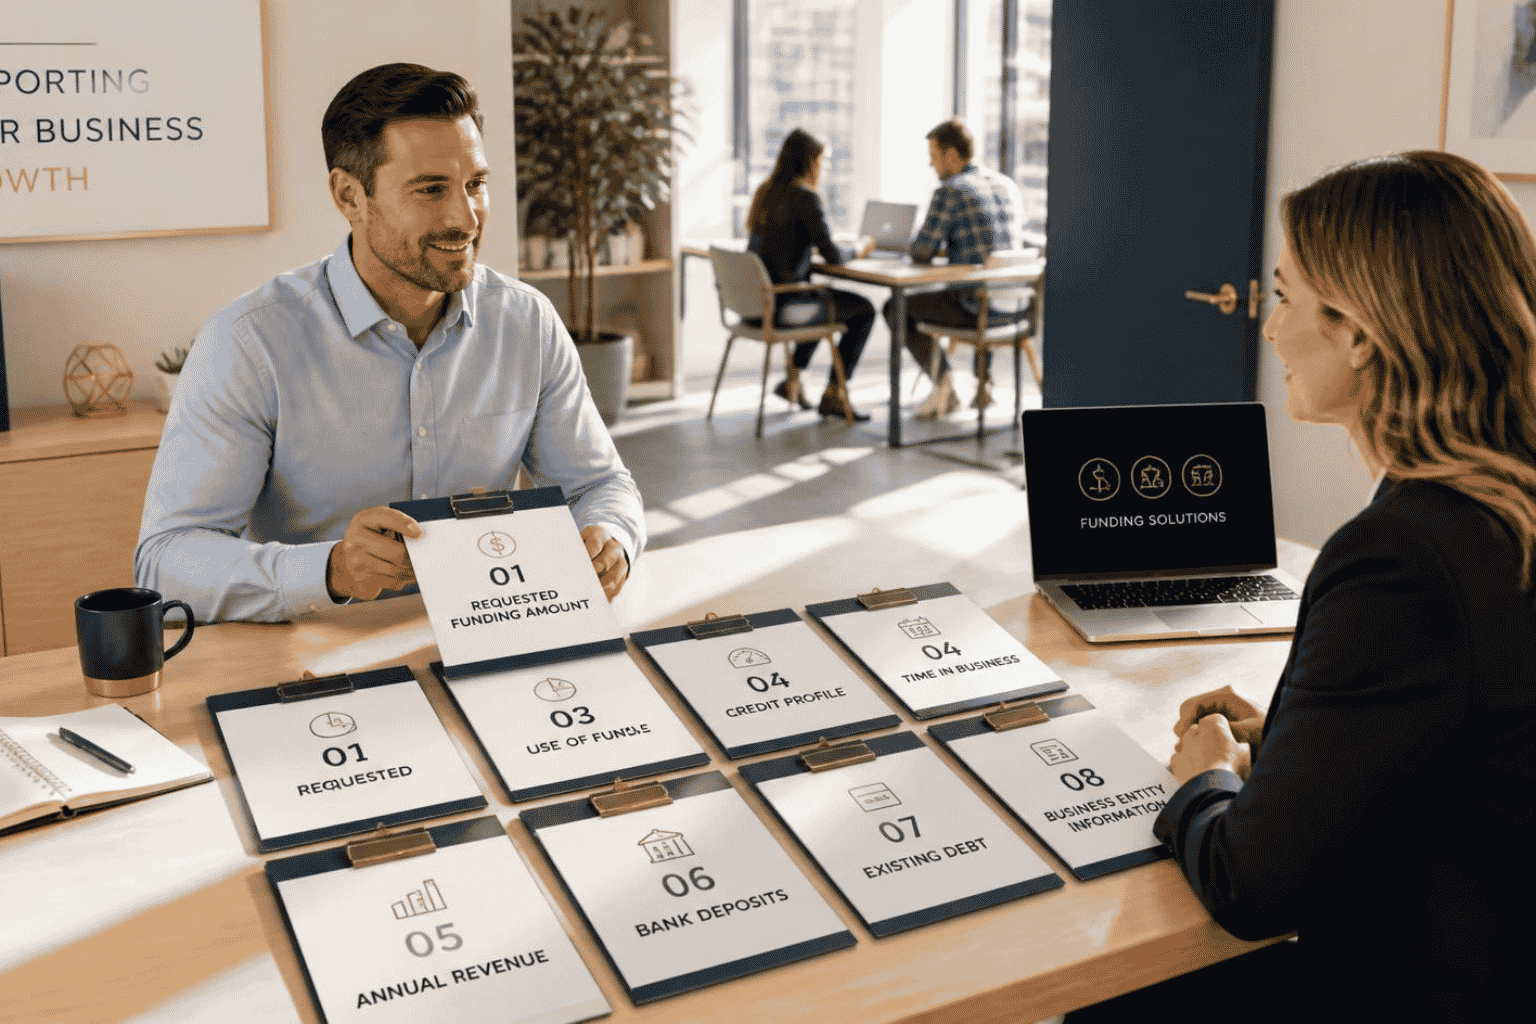
- Personal credit information
- Business entity and ownership details
- Time in business
- Annual revenue and cash flow
- Business financial statements
- Existing business debt
- Owner investment information
- Clear use of funds
- Repayment plan or repayment capacity
What Credit Profile Is Commonly Associated With SBA Financing?
Business funding guidance commonly associates SBA lending with good personal credit, often around 680 to 700 or higher, although individual lenders and programs can use different underwriting standards.
Why Does Repayment Ability Matter?
Government backing does not eliminate lender risk analysis. Funding providers still need to understand whether the operating business can reasonably support the proposed loan payments.
What About Owner Investment?
Depending on the SBA program and transaction, reasonable owner equity investment may be part of the financing structure. Acquisition and fixed-asset transactions can have different requirements.
Should Business Owners Assume SBA Is Their Only Option?
No. SBA-related financing is one category among several. Depending on credit, revenue, operating history and use of funds, a business may also evaluate term loans, equipment financing, working capital, online business loans or traditional lines of credit.
If your company is preparing for an SBA loan or another funding request, complete the EIN Business Funding pre-qualification using your current financial profile.
Questions Business Owners Ask
Does an SBA loan come directly from the federal government?
SBA lending is generally made through participating lenders under SBA program rules rather than directly to the borrower by the SBA.
What credit score is commonly associated with SBA financing?
Approximately 680 to 700 or higher is commonly associated with stronger SBA borrower profiles, although requirements vary.
Does government backing guarantee approval?
No. The lender still evaluates eligibility, repayment ability and the complete borrower and transaction profile.
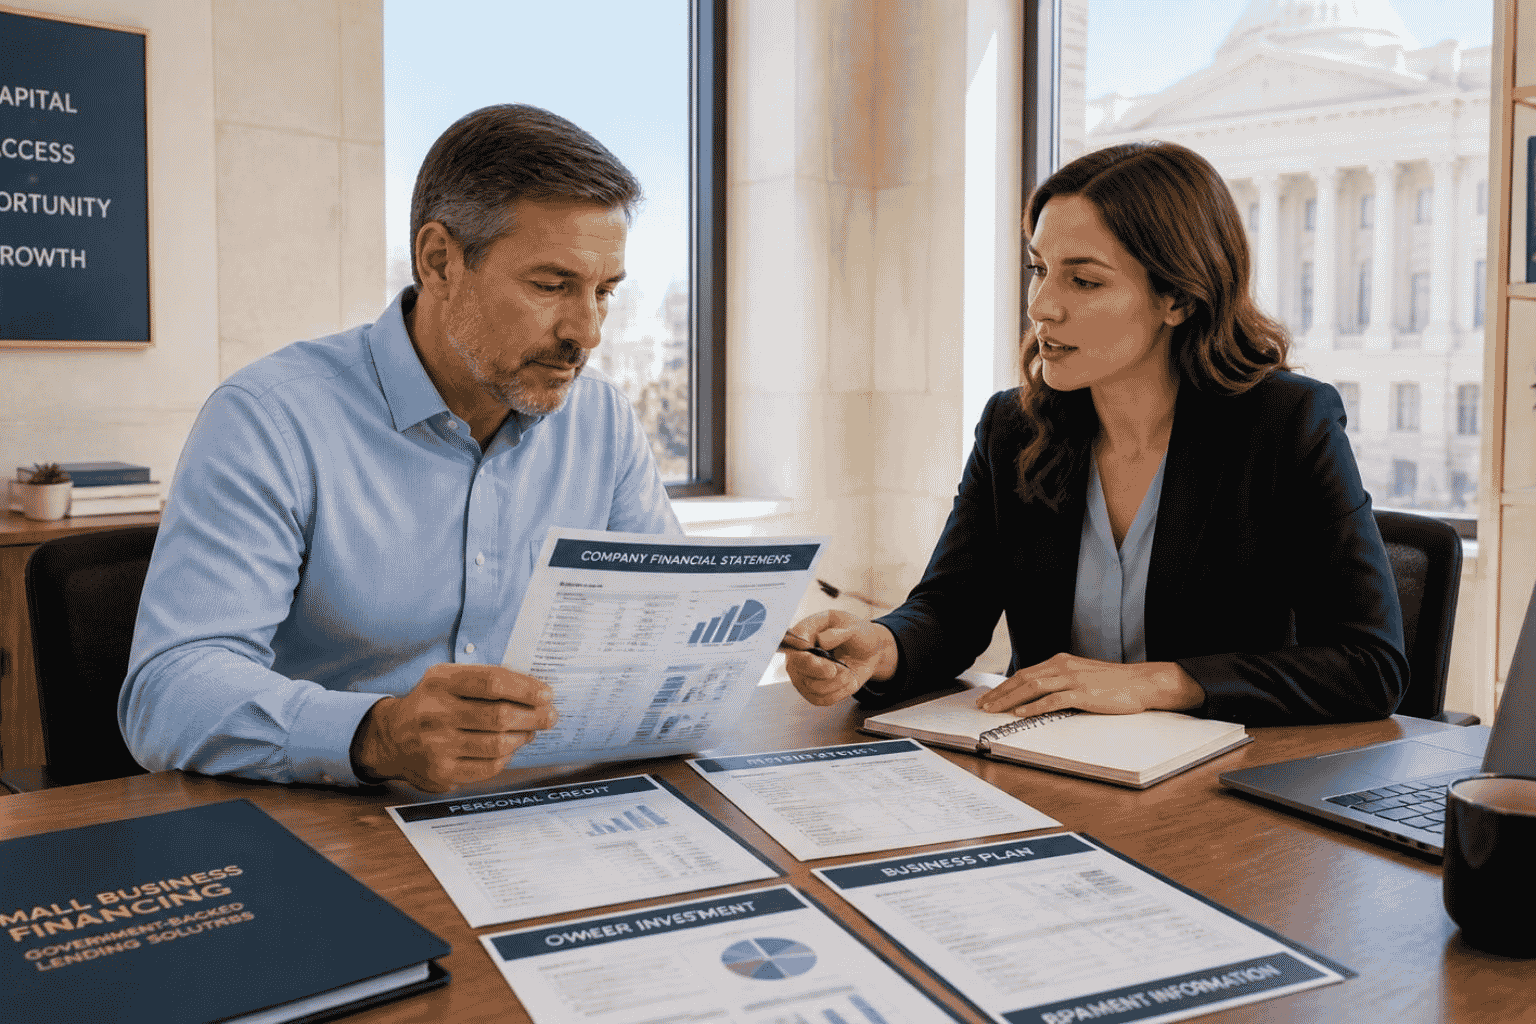 SBA-related financing still requires lender underwriting, repayment ability and an organized borrower profile.