Business Funding With Bank Statements: What Online Lenders Look for in Revenue and Deposits
Business owners searching for funding with bank statements are often looking for a financing process that focuses heavily on current operating activity rather than only traditional bank documentation. Online and alternative business lenders may place meaningful weight on consistent deposits and recent business performance.
If your business has active deposits and needs capital now, complete the EIN Business Funding Quick Lead Pre-Qualification with your annual revenue, time in business, credit range and requested funding amount.
Can Business Bank Statements Help With Funding Qualification?
Yes. Bank statements can help funding providers understand actual business deposits, operating activity and cash-flow consistency.
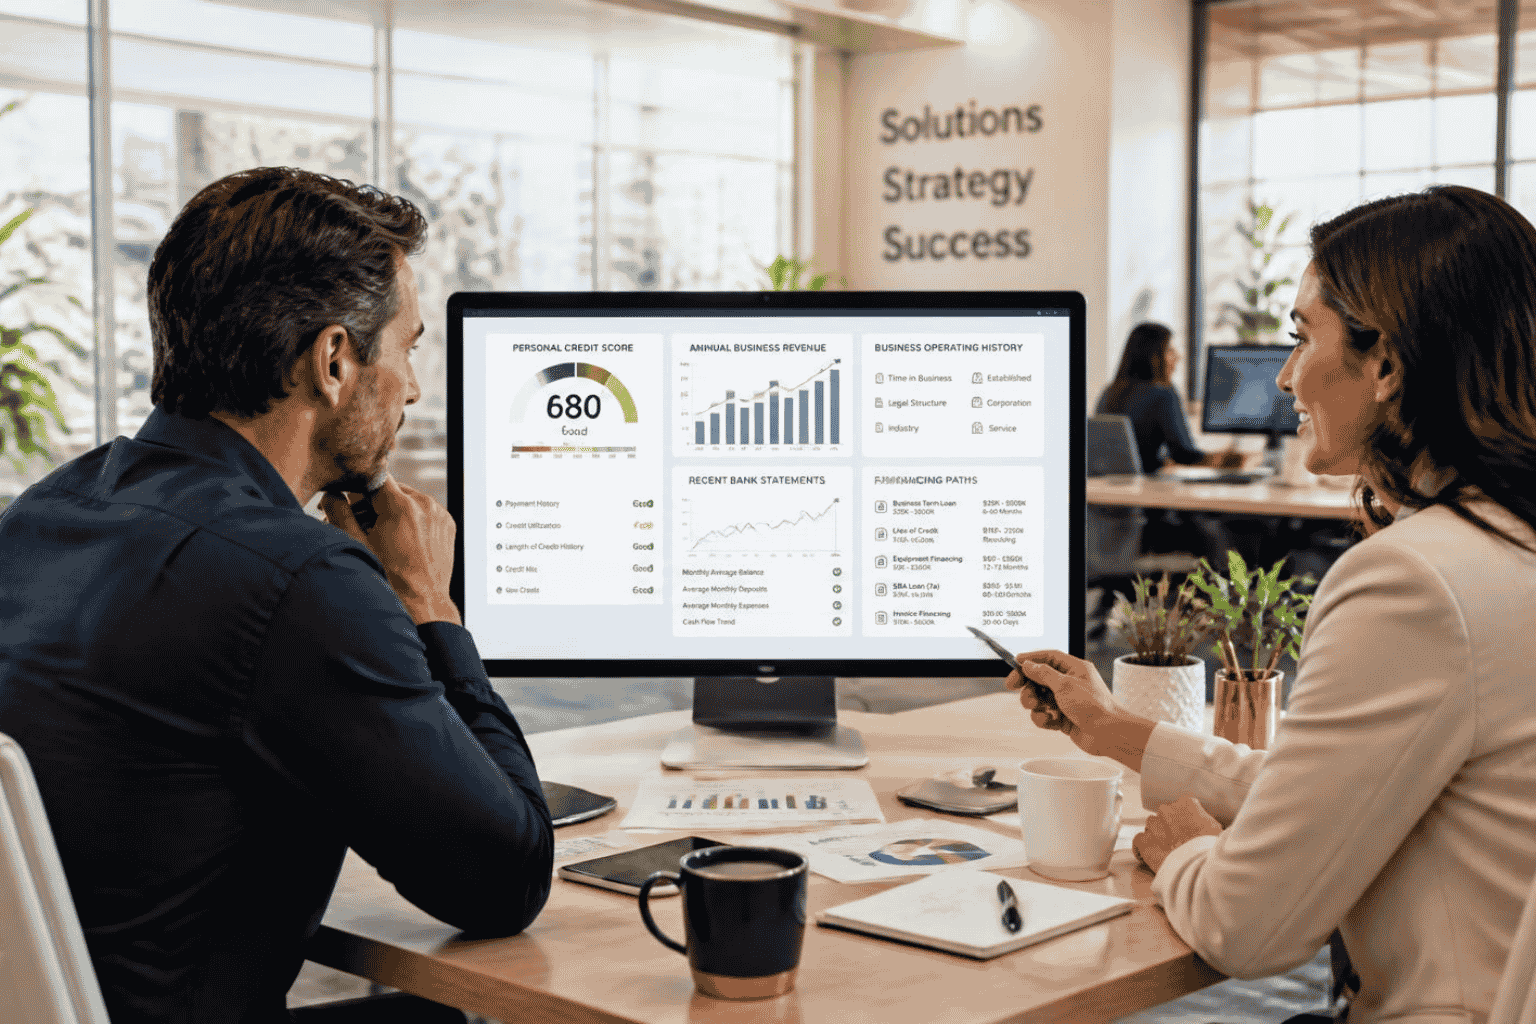
For online or alternative small-business loans, common benchmarks can include approximately 600 to 680+ personal credit, six to twelve months in business, approximately $50,000 to $250,000+ in annual revenue and consistent deposits.
What Do Lenders Look for in Business Deposits?
A provider may evaluate whether deposits appear consistent enough to support the requested financing. Revenue that exists only on paper but does not translate into usable business cash flow can present a different profile from a company with stable deposits.
What Else Matters Besides Bank Statements?
- Personal credit profile
- Time in business
- Annual business revenue
- Existing debt obligations
- Industry
- Requested funding amount
- Specific use of funds
Do Bank-Statement-Based Funding Options Require Perfect Credit?
Not necessarily. Alternative business lenders commonly use different credit standards from traditional banks. That does not mean credit is ignored; it means the complete business profile may be evaluated differently.
How Is This Different From a Traditional Business Line of Credit?
Traditional business lines of credit commonly use stricter qualification benchmarks, including approximately 720+ personal credit, one to two years in business, around $100,000 to $250,000+ annual revenue and positive cash flow.
They may also require business and personal tax returns, profit and loss statements and other financial documentation.
What Should You Prepare Before Pre-Qualification?
Know your current Experian FICO score, time in business, annual revenue, business banking institution, requested amount and existing debt.
If your company has consistent business deposits and an active funding need, complete the EIN Business Funding pre-qualification to explore which financing categories may fit your current profile.
Questions Business Owners Ask
Can I get business funding using bank statements?
Potentially. Some online and alternative funding providers place significant weight on recent bank activity and consistent business deposits.
What credit scores do online business lenders commonly consider?
Typical ranges can be approximately 600 to 680+, although requirements vary by provider and financing product.
Do bank statements replace every other qualification requirement?
No. Providers may still review credit, revenue, business history, existing debt, industry and use of funds.
 Consistent business deposits can help funding providers understand current operating activity and cash-flow strength.