Business Credit Card vs SBA Microloan for a Startup: Which Funding Profile Fits?
A startup that needs capital before building a long operating history may not fit traditional bank-loan requirements. Two funding categories that can sometimes be relevant earlier are business credit cards and SBA microloans, but their qualification profiles are not identical.
If your startup has a defined funding need, complete the EIN Business Funding Quick Lead Pre-Qualification with your current credit profile, business age and use of funds.
Can a Startup Qualify for a Business Credit Card Without Revenue?
Potentially. Business credit-card issuers may approve new businesses or side businesses without established revenue when the owner’s personal credit is strong.
Approximately 740+ personal credit is a common strong benchmark in the EIN Business Funding guidance.
What Else Is Commonly Required for a Business Credit Card?
A registered business and the owner’s Social Security Number are commonly part of the application. An EIN may also be required or recommended depending on the issuer.
A personal guarantee is also commonly required.
What About an SBA Microloan?
SBA microloans are designed for smaller financing needs and can be available to startups. Common considerations include good personal credit, a business plan and demonstrated ability to repay.
The funding guidance associates approximately 740+ credit with a stronger SBA microloan profile, although actual intermediary requirements can vary.
How Are the Two Funding Paths Different?
A business credit card provides revolving credit and may rely heavily on the owner’s personal credit profile. An SBA microloan is a loan structure intended for smaller business financing needs and typically involves review of the business plan and repayment ability.
What Should a Startup Prepare Before Applying?
- Business registration information
- EIN if applicable
- Current personal credit profile
- Ownership details
- Business plan
- Requested funding amount
- Specific use of funds
- Repayment plan or expected business cash flow
Should a Startup Apply for Both Immediately?
Not automatically. The stronger approach is to understand the qualification profile first and avoid submitting unnecessary applications for products that do not fit the business or owner.
If your startup needs capital and you want to understand which business-funding categories may be worth exploring, complete the EIN Business Funding pre-qualification.
Questions Startup Founders Ask
Can a startup get a business credit card without revenue?
Potentially. Some issuers may approve new businesses when the owner’s personal credit is strong.
Can startups qualify for SBA microloans?
Potentially. SBA microloans can serve smaller financing needs and may be available to startups that meet intermediary requirements.
Which is better for a startup: a business credit card or SBA microloan?
The better fit depends on the amount needed, intended use, personal credit, business plan, repayment ability and the requirements of the specific provider.
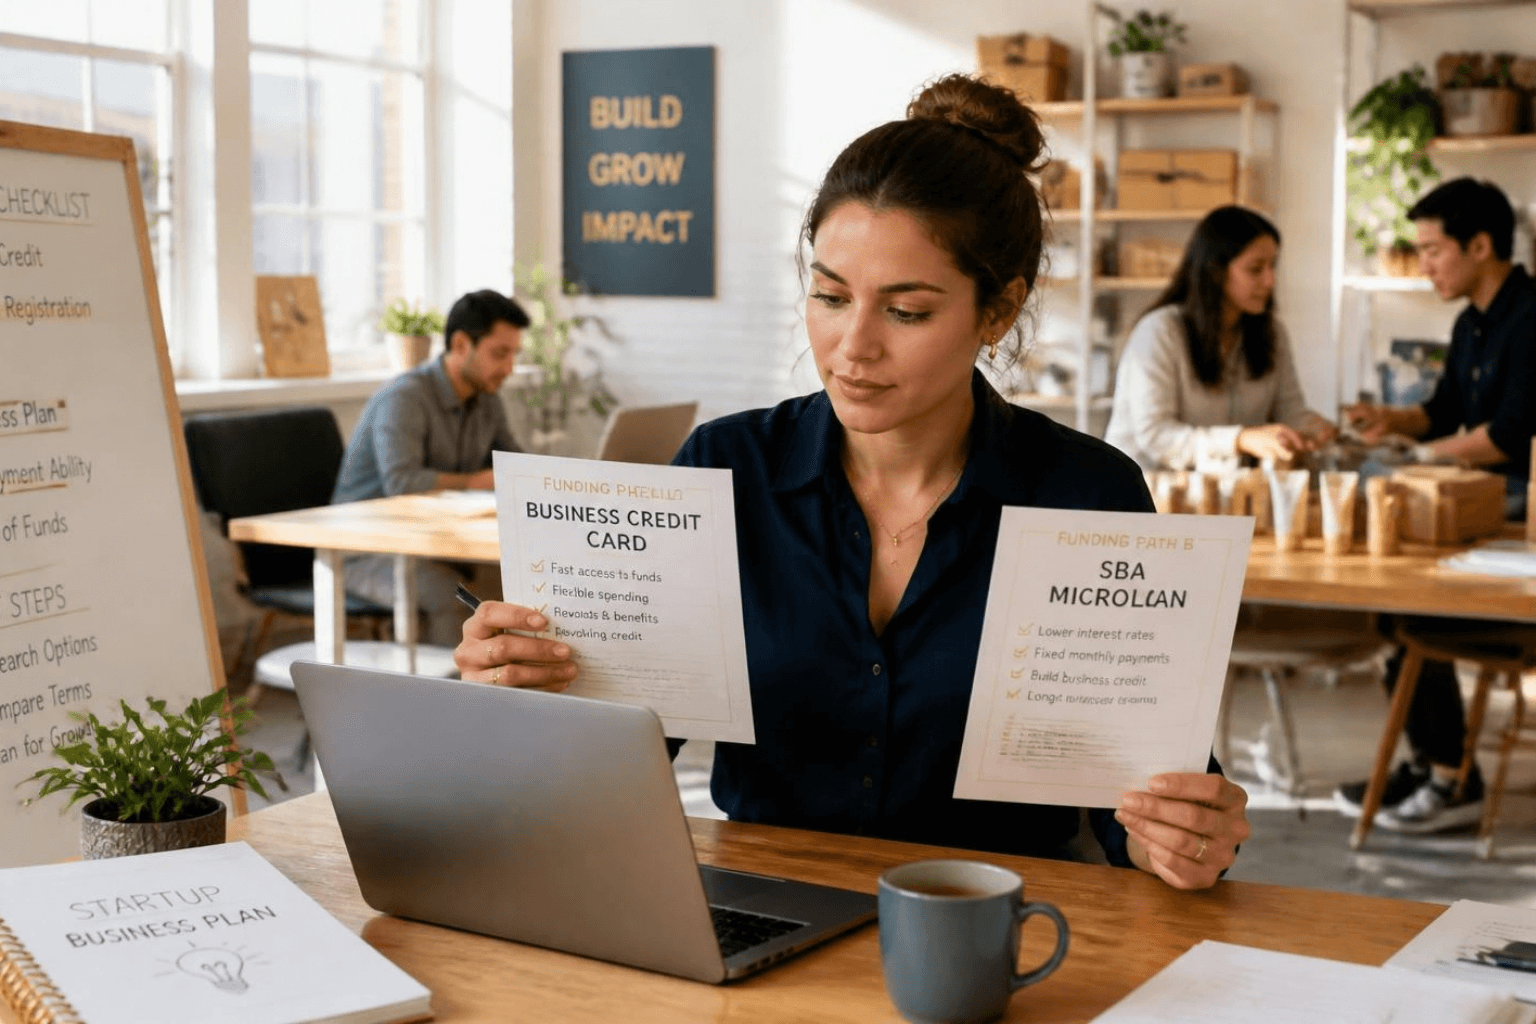 Business credit cards and SBA microloans can serve different startup funding needs and use different qualification considerations.