Business Equipment Line of Credit vs Equipment Financing: Which Fits Repeat Purchases?
A business buying one major machine has a different capital need from a company that expects to make equipment purchases repeatedly throughout the year. That distinction can affect whether equipment financing or a revolving business line of credit is worth exploring.
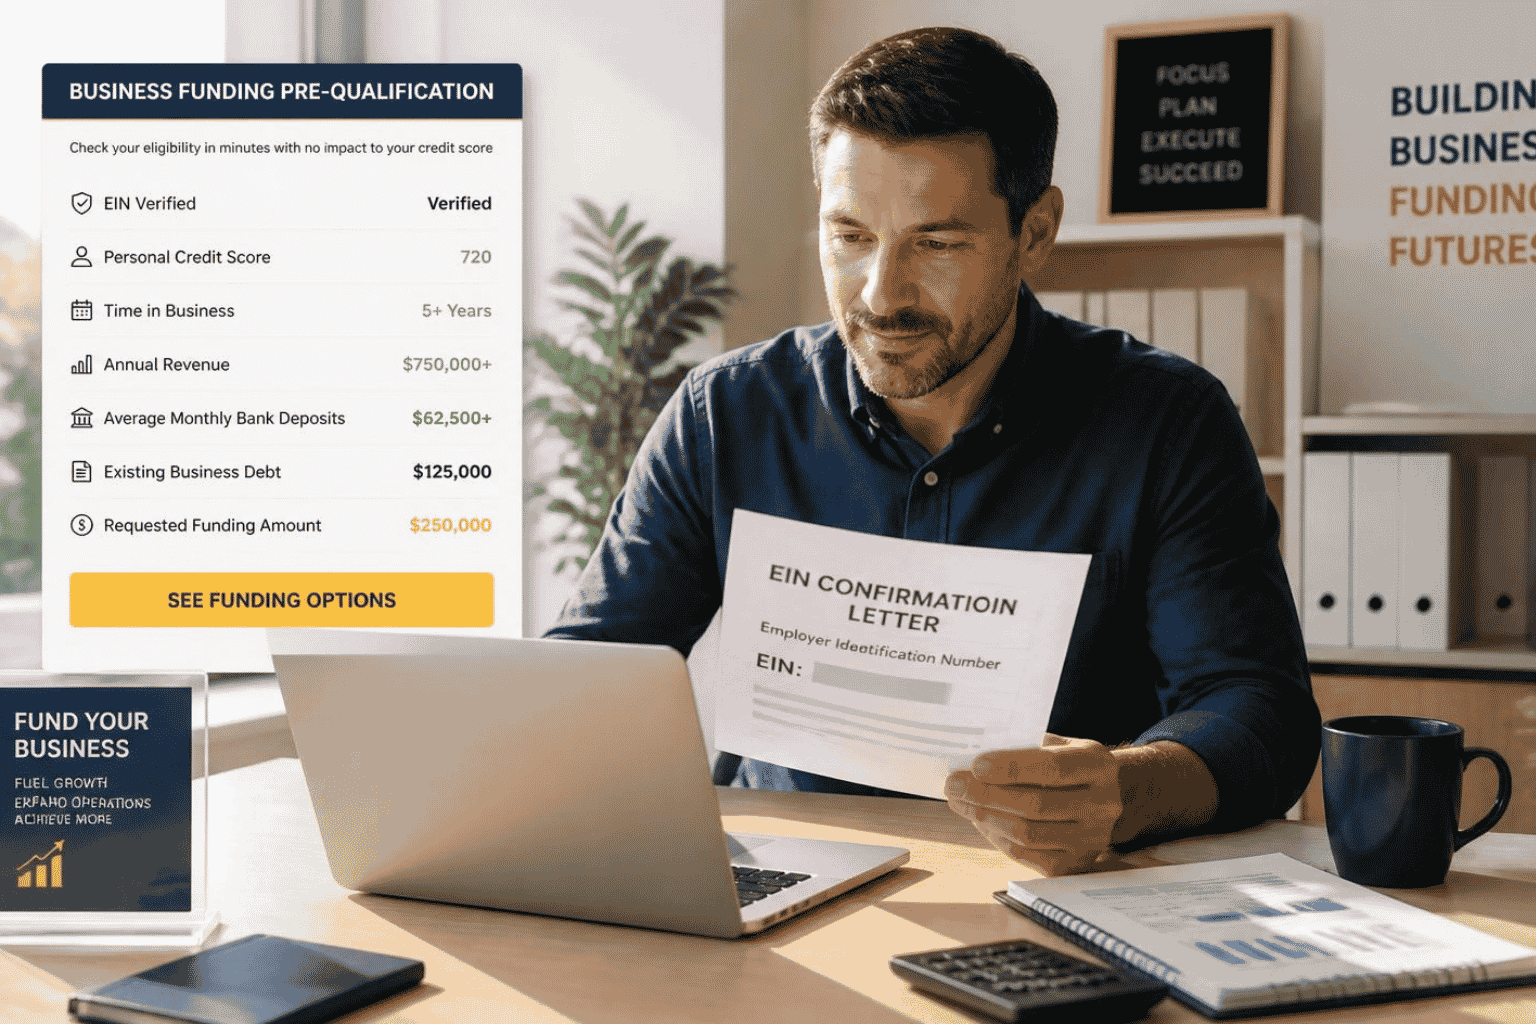
If your company has upcoming equipment purchases and needs capital now, complete the EIN Business Funding Quick Lead Pre-Qualification.
When May Equipment Financing Fit Better?
Equipment financing may be worth evaluating when the funding request is tied directly to a specific qualifying business asset.
Have the equipment quotation, purchase price and requested financing amount ready.
When May a Business Line of Credit Fit Better?
A line of credit may be more relevant when an established business wants revolving access to capital for recurring needs rather than financing one asset at a time.
What Are Typical Traditional Line-of-Credit Benchmarks?
The EIN Business Funding guidance identifies approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ in annual revenue and positive cash flow as common traditional business line-of-credit benchmarks.
Business tax returns, personal tax returns, profit and loss statements and business bank statements may also be requested.
What Else May the Lender Review?
Traditional lenders may evaluate debt-service coverage, existing business debt, industry risk and cash-flow consistency.
What If You Need Equipment and Operating Cash?
Do not automatically combine everything into one request. Equipment and working-capital needs may fit different financing categories.
If your company is actively purchasing equipment, complete the EIN Business Funding pre-qualification with the equipment cost, business revenue, credit profile and whether the need is one-time or recurring.
FAQs
What is the difference between equipment financing and a business line of credit?
Equipment financing is generally tied to a specific qualifying asset, while a line of credit can provide revolving access to business capital subject to the provider’s terms.
What are common traditional business line-of-credit benchmarks?
Approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ annual revenue and positive cash flow are common benchmarks in the EIN Business Funding guidance.
Should equipment and working capital be financed the same way?
Not necessarily. The two needs may fit different financing structures.
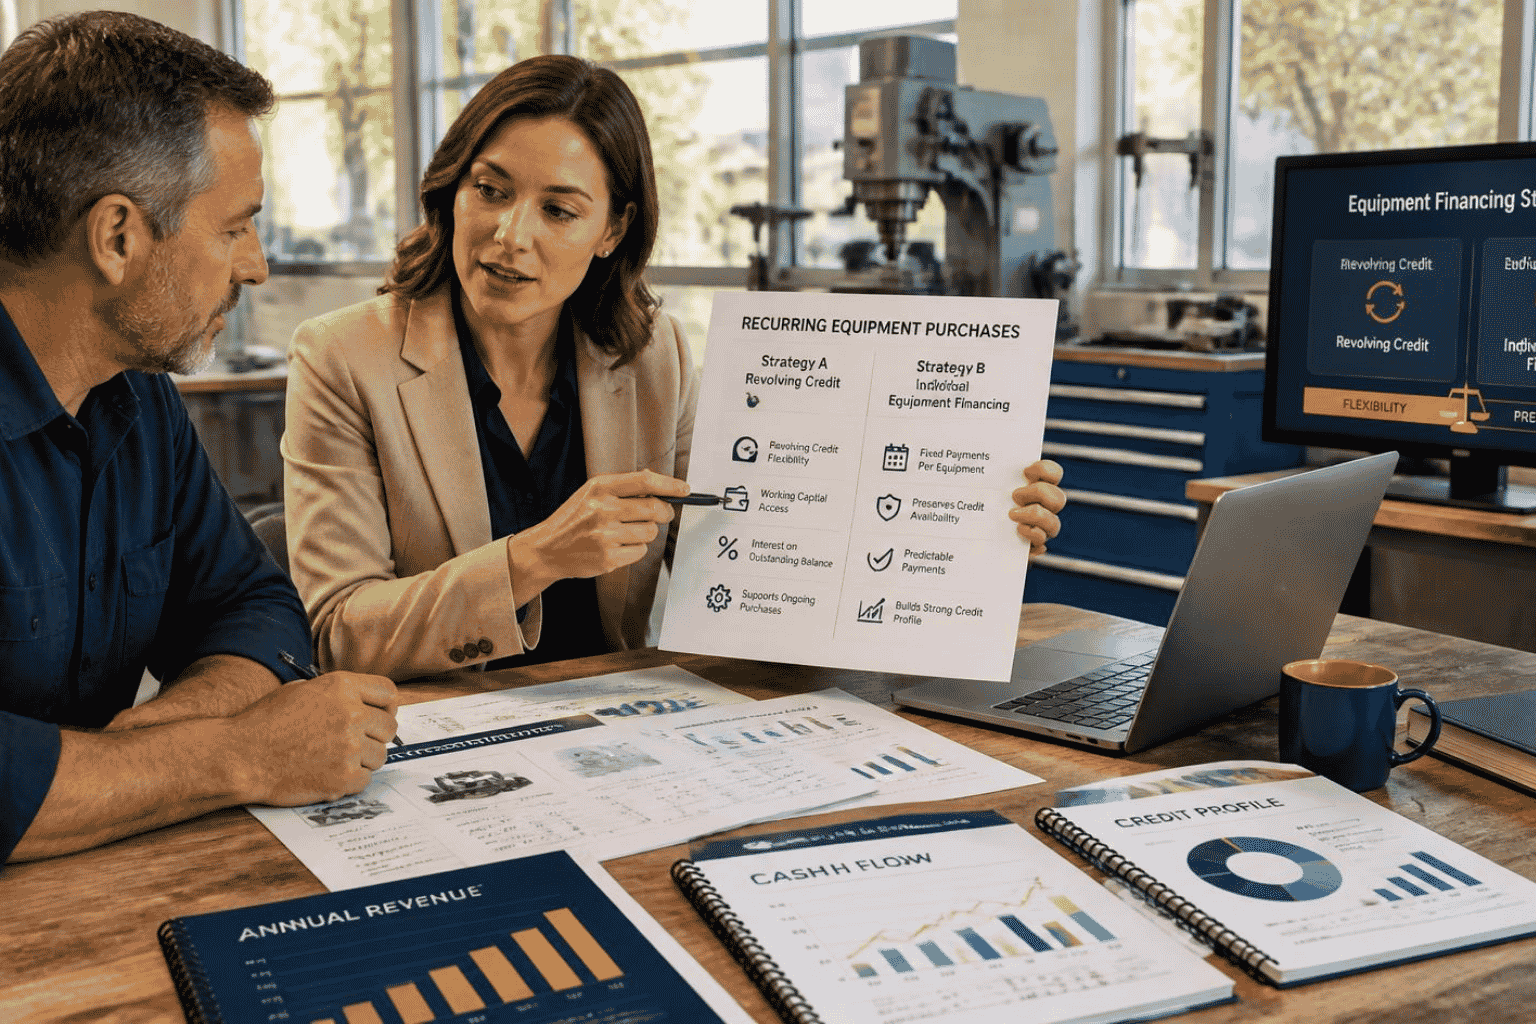 Recurring equipment purchases and one-time asset purchases can require different capital strategies.