Fixed-Term Business Loan vs Line of Credit: Which Fits a One-Time Funding Need?
A business owner who needs capital for one defined purchase or project may not need the same financing structure as a company that expects to draw funds repeatedly throughout the year. That distinction is important when comparing a fixed-term business loan with a business line of credit.
If your company currently needs capital, complete the EIN Business Funding Quick Lead Pre-Qualification with the amount needed, use of funds, revenue and current credit profile.
When May a Fixed-Term Business Loan Fit?
A term loan may be worth evaluating when the business has one defined funding requirement and expects to repay the borrowed amount over a set repayment period.
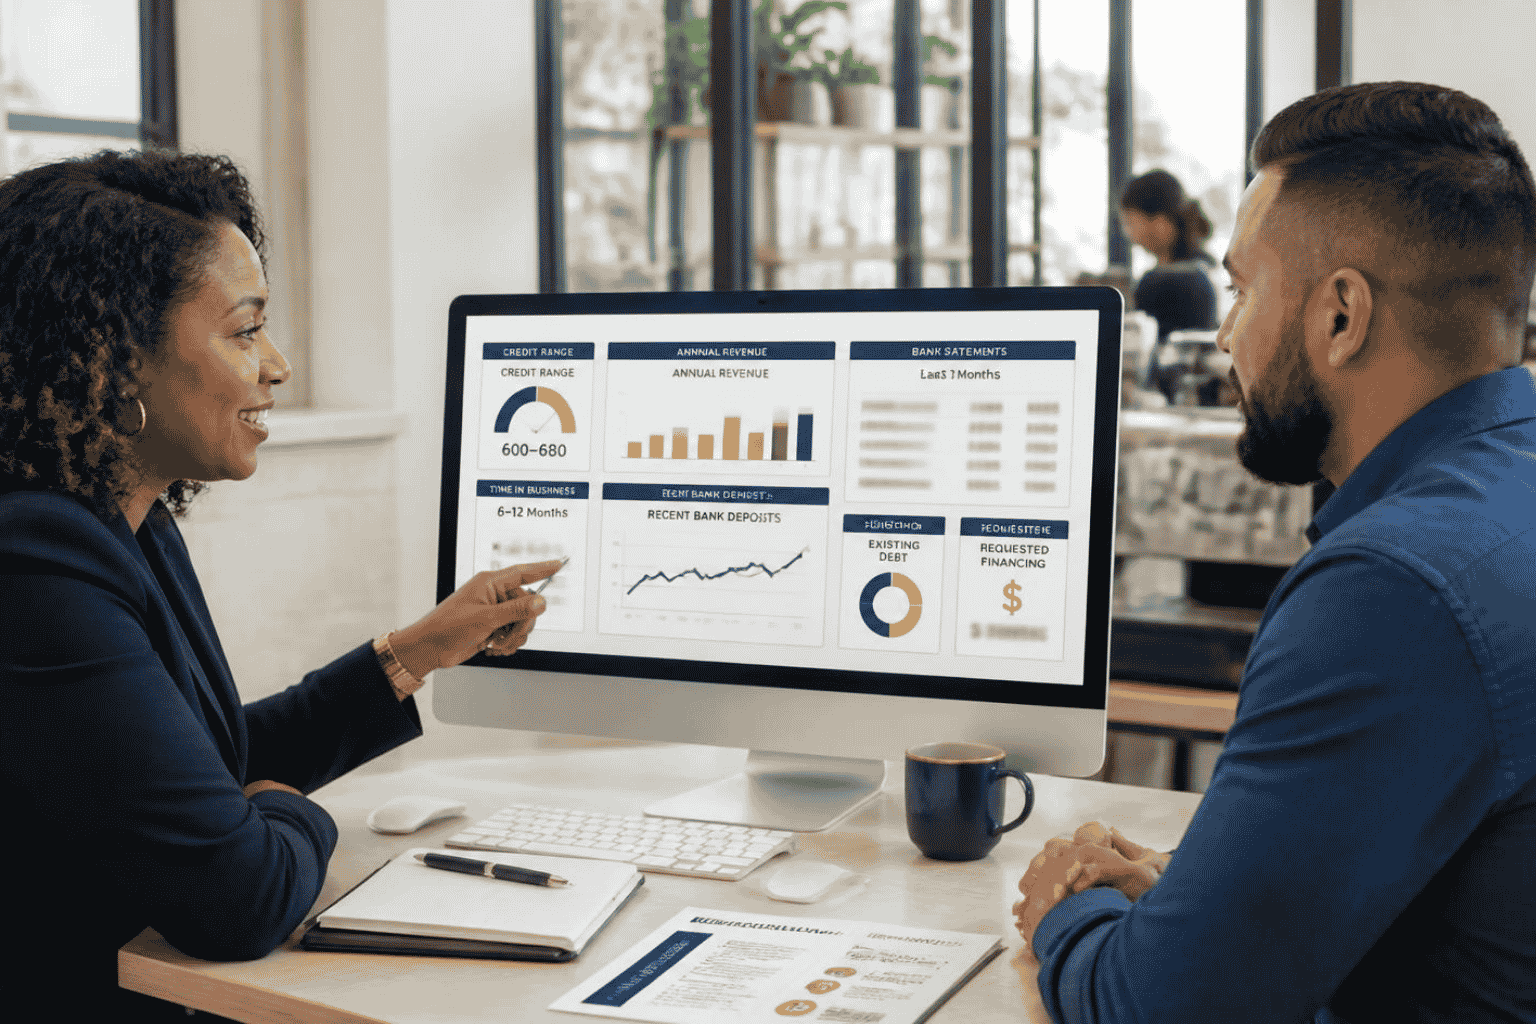
Typical term-loan benchmarks in the EIN Business Funding guidance include approximately 600 to 680+ personal credit, one or more years in business, $100,000+ in annual revenue and positive cash flow.
When May a Business Line of Credit Fit?
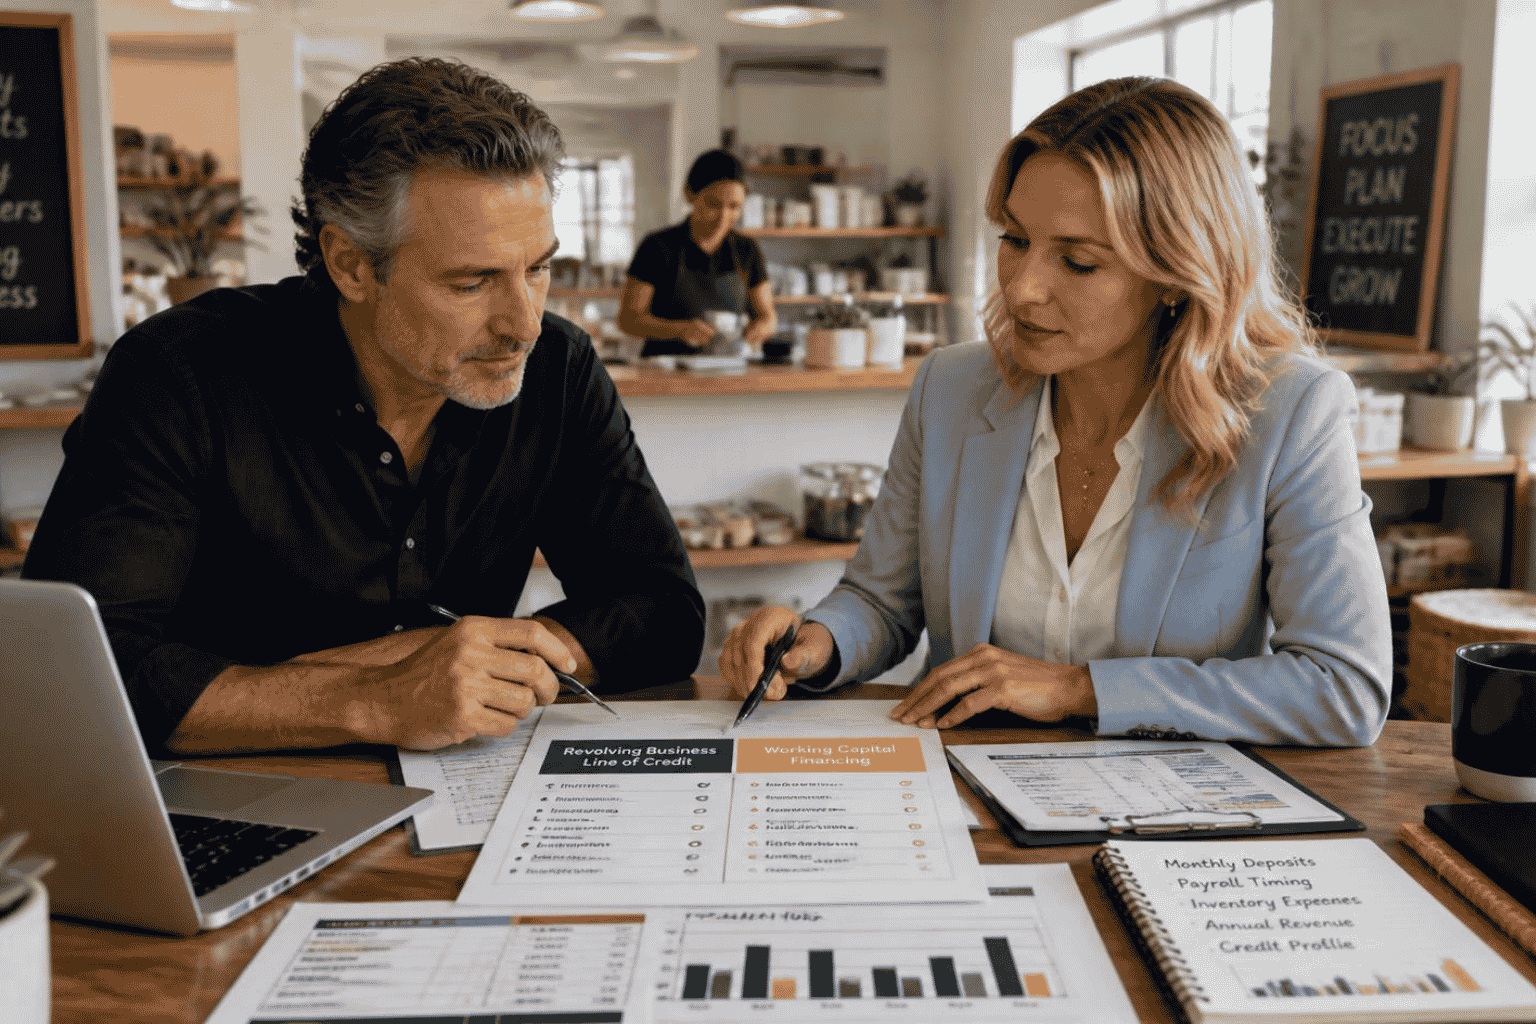
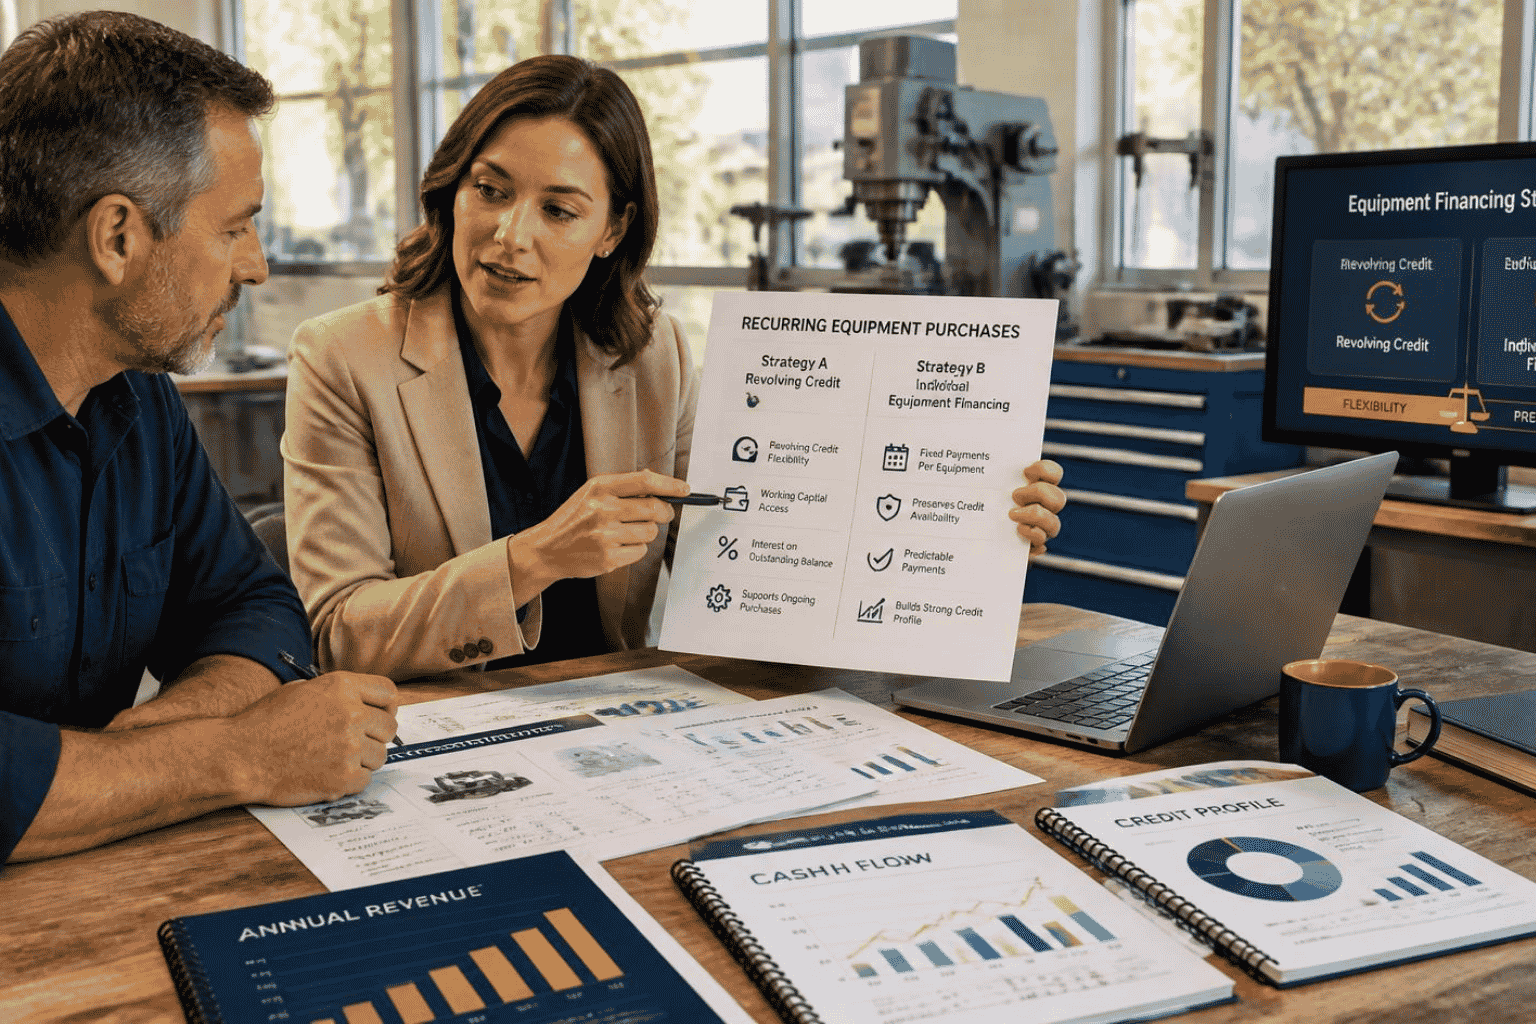
A line of credit can be more relevant when the business wants revolving access to capital for recurring needs rather than one specific expense.
What Are Typical Traditional Line-of-Credit Benchmarks?
The funding guidance identifies approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ in annual revenue and positive cash flow as common traditional line-of-credit benchmarks.
What Else Can a Traditional Lender Review?
- Business bank statements
- Profit and loss statements
- Business and personal tax returns
- Existing business debt
- Debt-service coverage
- Cash-flow consistency
- Industry risk
Which Option Is Easier to Qualify For?
There is no universal answer. Traditional bank lines of credit commonly use stronger borrower profiles than many online term-loan options, but each provider has its own underwriting standards.
If you already know the amount and exact business purpose, complete the EIN Business Funding pre-qualification so the request can be matched more closely to your current profile.
FAQs
What are common term-loan qualification benchmarks?
The EIN Business Funding guidance identifies approximately 600 to 680+ personal credit, one or more years in business, $100,000+ annual revenue and positive cash flow as common benchmarks.
What are common traditional business line-of-credit benchmarks?
Approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ annual revenue and positive cash flow are common benchmarks in the funding guidance.
Should I choose a term loan or line of credit based only on the interest rate?
No. The business should also consider whether the need is one-time or recurring, qualification requirements, repayment structure and total financing terms.
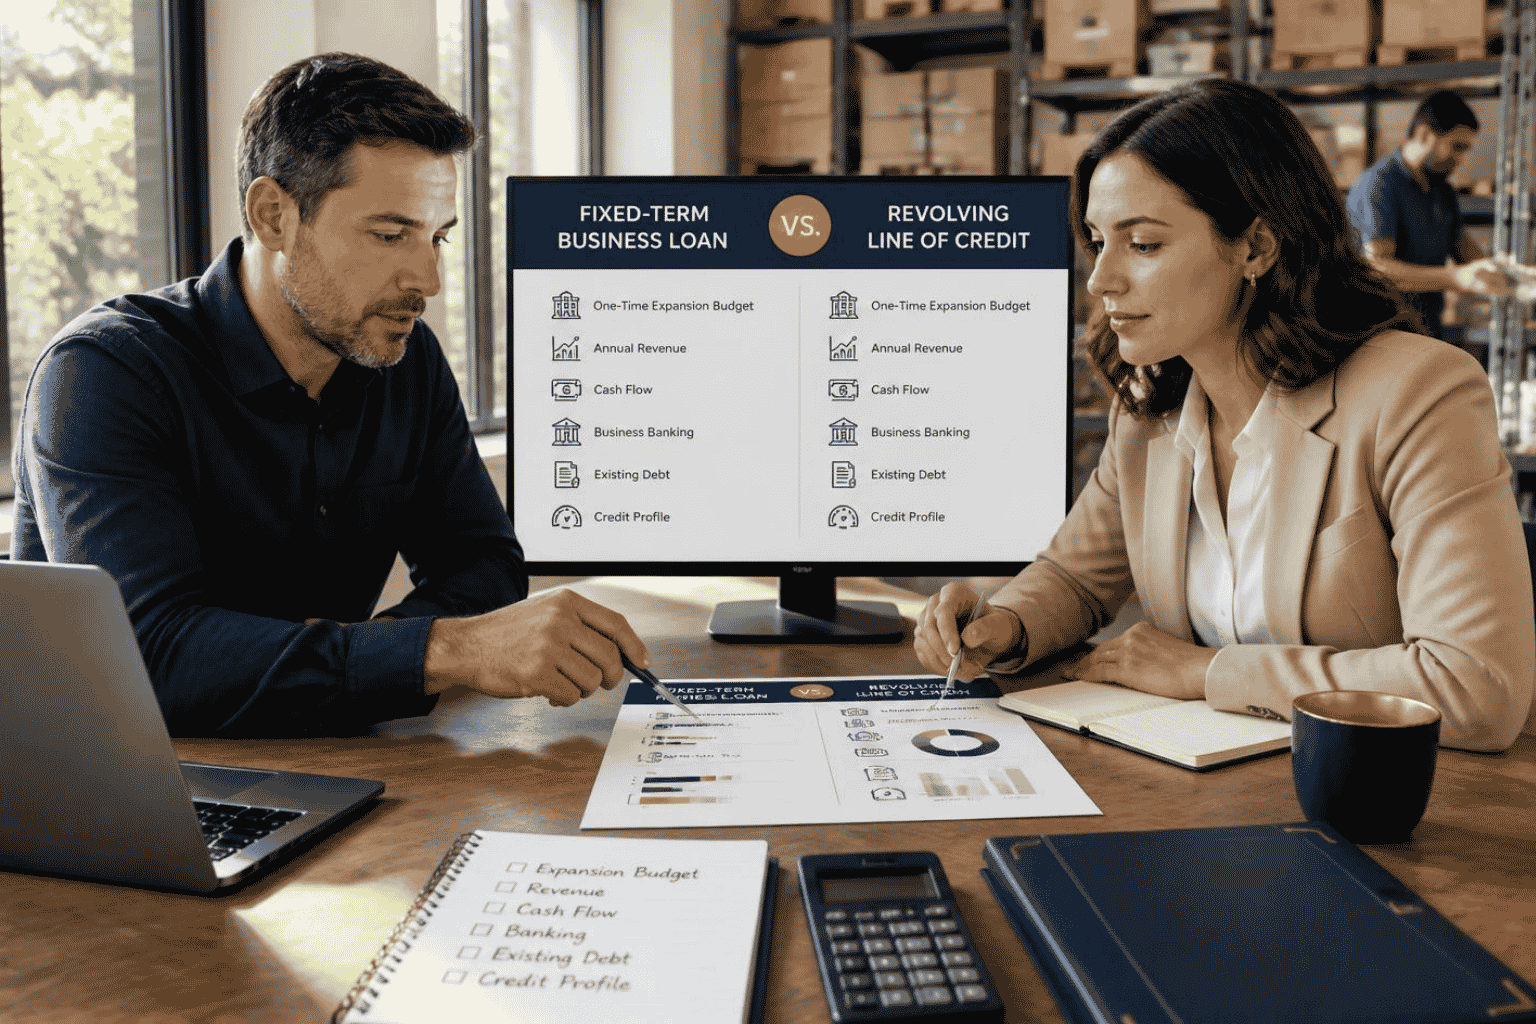 A defined one-time expense and a recurring capital need may call for different business financing structures.