Fintech Business Loan With 600–680 Credit: What Online Lenders May Review Beyond Your FICO Score
Fintech and online business lenders can use different qualification profiles from traditional banks. That does not mean credit stops mattering, but it can mean revenue, deposits and operating history receive significant attention alongside the owner’s credit profile.
If your business needs capital now and your credit is around 600 to 680, complete the EIN Business Funding Quick Lead Pre-Qualification with your current business numbers.
What Are Common Online or Alternative Loan Benchmarks?
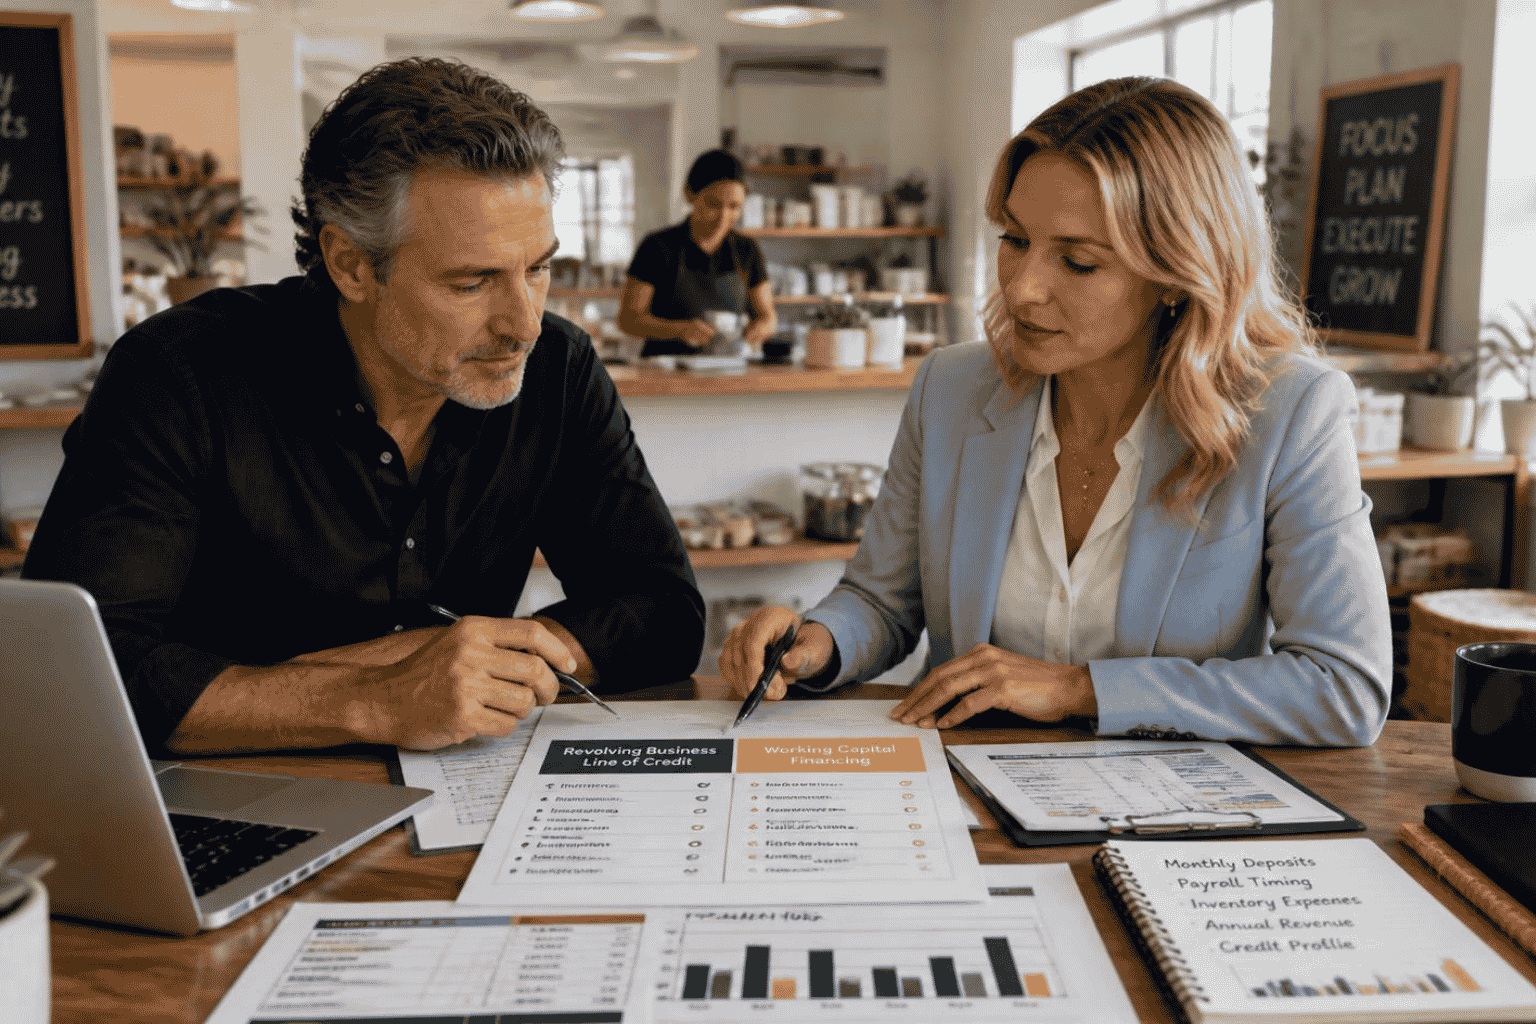
The EIN Business Funding guidance identifies approximately 600 to 680+ personal credit, six to twelve months in business and approximately $50,000 to $250,000+ in annual revenue as common benchmarks for online or alternative small-business financing.
Why Do Bank Deposits Matter?
Consistent deposits can help demonstrate that the business is actively generating revenue. Business bank statements may therefore become an important part of the financing review.
Does a Fintech Loan Mean EIN-Only Approval?
No. An EIN may be part of the application, but funding providers may still evaluate personal credit, operating history, annual revenue, cash flow, existing debt and other underwriting factors.
What Should You Prepare?
- Business formation date
- EIN and legal entity information
- Annual business revenue
- Recent business deposits
- Business bank statements
- Current credit profile
- Existing loans and credit lines
- Requested amount and use of funds
Is Online Financing Automatically Better Than a Bank Loan?
No. Qualification speed, documentation, repayment structure and total cost can differ substantially by provider. Business owners should compare the complete financing terms rather than focusing only on approval speed.
If your business has at least six months of operating history and consistent revenue, complete the EIN Business Funding pre-qualification to explore financing paths that may fit your current profile.
FAQs
Can online lenders consider a business owner with a 600–680 credit score?
Potentially. The EIN Business Funding guidance identifies approximately 600 to 680+ as a common range for online or alternative small-business financing.
Why do fintech lenders ask for business bank statements?
Bank statements can help show recent deposits, operating activity and cash-flow patterns.
Does using an EIN mean personal credit will not be reviewed?
No. Funding providers may still evaluate personal credit and the complete business profile.
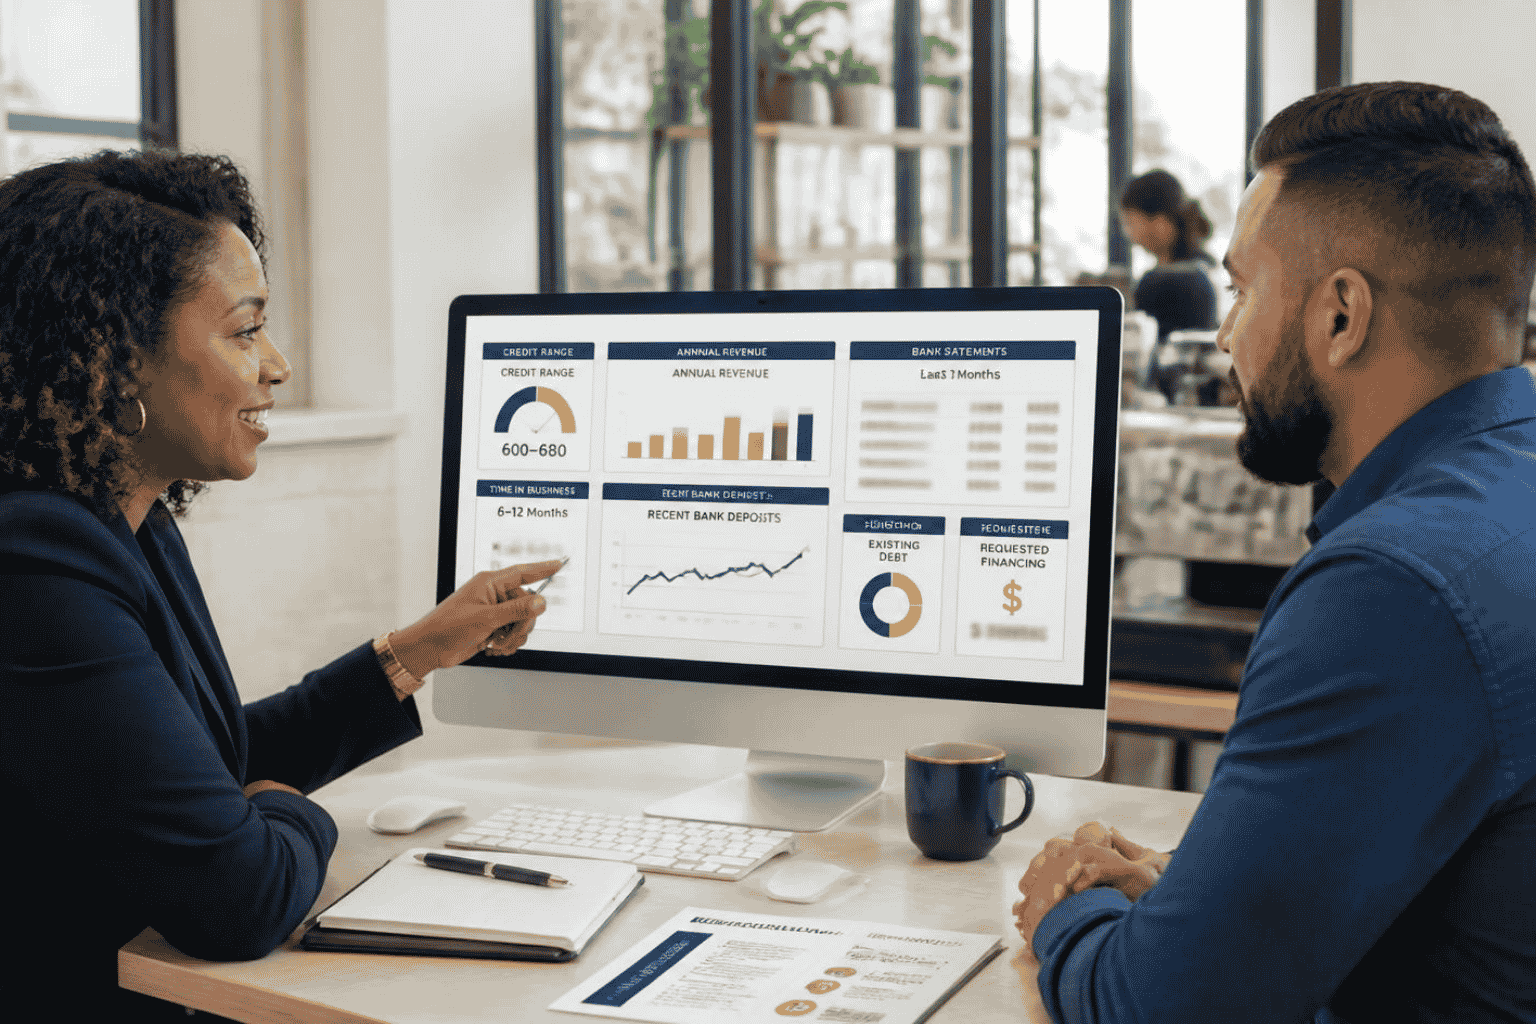 Online lenders may review credit together with revenue, business history, deposits and existing obligations.