Holiday Inventory Financing: Working Capital Loan or Business Line of Credit With EIN?
The holiday season creates one of the clearest working-capital problems for product-based businesses: inventory often has to be purchased before the sales revenue arrives.
Retailers, e-commerce companies, wholesalers, gift businesses and specialty-product sellers may need to place larger supplier orders, pay freight and prepare inventory weeks before customers make their purchases.
For businesses searching for holiday inventory financing, two common options worth comparing are a working capital loan and a business line of credit.
If you already know how much inventory your business needs and how much cash is required before holiday sales arrive, complete the EIN Business Funding Quick Lead Pre-Qualification using current revenue, credit, business age and the actual funding requirement.
Start With the Inventory Gap
Do not begin by asking for the largest amount available.
Calculate how much inventory must be purchased, when suppliers must be paid and when customer cash is expected to arrive.
If the business needs $80,000 in inventory but has $30,000 available without disrupting payroll and ordinary operations, the actual funding gap may be closer to $50,000.
That is a much more useful number for a financing discussion.
When Can a Working Capital Loan Fit?
A working capital loan may be relevant when the business has a defined short-term operating need.
The capital can potentially support inventory, payroll, supplier obligations or other eligible operating expenses depending on the provider and financing structure.
For a business making one substantial seasonal inventory purchase, a fixed funding amount may be easier to plan around than revolving credit.
When Can a Business Line of Credit Fit?
A business line of credit may be worth evaluating when the company repeatedly needs capital during the inventory cycle.
Subject to the financing terms, the business may draw funds when supplier payments are due, repay the balance as customer revenue arrives and use the available credit again later.
This can be useful for companies that experience seasonal inventory needs every year or several times throughout the year.
Does “Business Line of Credit With EIN” Mean EIN-Only Approval?
No.
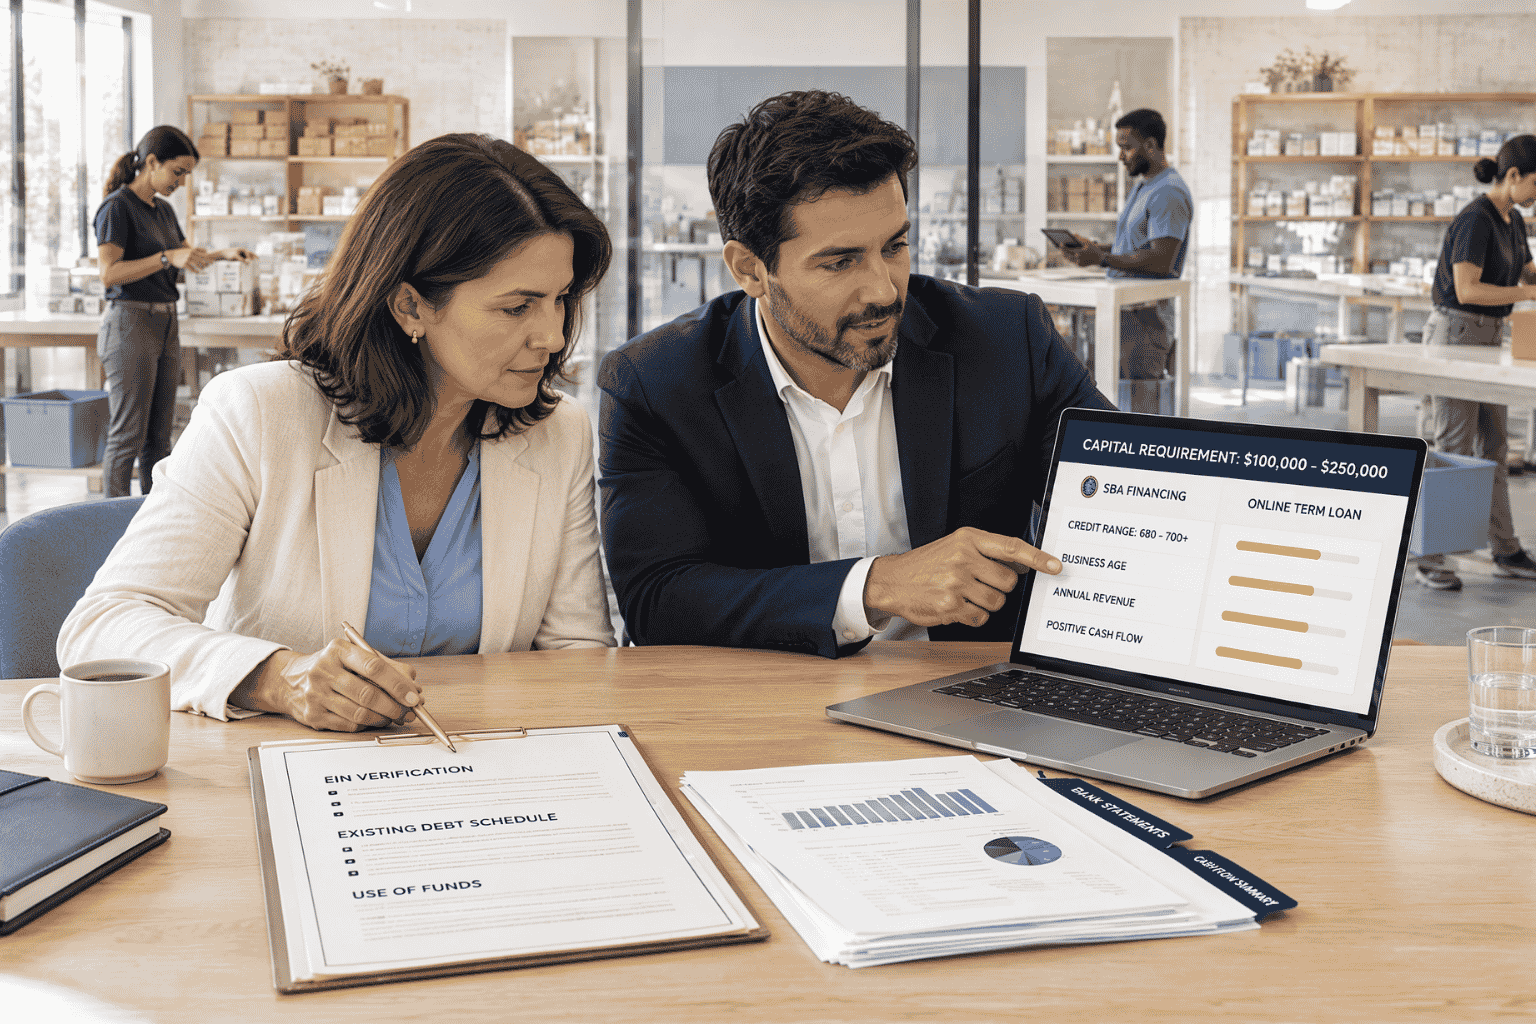
An Employer Identification Number identifies the business, but financing providers may also review personal credit, time in business, annual revenue, cash flow, bank statements, existing debt and other factors.
The EIN is an important part of the business application, not a universal replacement for underwriting.
How Do Traditional Line-of-Credit Profiles Differ?
Traditional revolving business credit commonly favors stronger borrower profiles.
Businesses may find that providers look for established operating history, stronger personal credit, meaningful annual revenue, positive cash flow and organized financial records.
A company that does not fit a traditional bank profile may still have other funding structures worth evaluating depending on its revenue, deposits, credit and financing need.
Holiday Inventory Financing Is About Timing
A profitable product can still create a cash-flow problem when the business pays for it long before the customer buys it.
The owner should understand:
- Supplier deposit date
- Final supplier payment date
- Freight and delivery cost
- Expected date inventory becomes available for sale
- Expected customer sales period
- Customer payment timing
The financing should bridge that gap without creating a repayment structure the company cannot support.
Do Not Forget Freight and Fulfillment
Inventory price is not always the full seasonal cost.
The business may also need capital for freight, warehouse labor, packaging, fulfillment, temporary staff, marketplace fees or increased advertising.
Identify those expenses separately instead of discovering them after the inventory purchase has already consumed available cash.
How Much Inventory Is Too Much?
Holiday demand can encourage owners to order aggressively.
Financing should not become a reason to purchase more stock than the company can reasonably sell.
Unsold seasonal merchandise may require discounting after the peak period, which can reduce margins while the financing obligation remains.
Look at Last Year’s Inventory Turn
If the business operated during the previous holiday season, review how quickly inventory sold and how much remained afterward.
Historical results can help the owner develop a more realistic purchasing plan.
A business experiencing rapid growth may need more inventory than last year, but the increase should still be tied to credible sales activity rather than optimism alone.
Recent Business Deposits Can Matter
Some funding providers may review recent bank activity to understand current revenue and cash-flow consistency.
For a business entering the holiday season, recent deposits can help demonstrate whether operations are stable before the larger inventory purchase is made.
Existing Debt Can Reduce Seasonal Flexibility
Prepare current business loans, credit lines, business credit cards, equipment financing and other obligations.
A company already making several substantial payments may have less ability to support another financing facility even if holiday sales are expected to be strong.
Should the Business Borrow for Marketing Too?
Marketing can be a legitimate operating expense, but it should be budgeted separately from the inventory itself.
Know how much of the funding request is for products and how much is for acquiring customers.
Borrowing heavily for advertising becomes risky when the expected sales conversion has not been tested.
What Should Be Ready Before Applying?
- Holiday inventory purchase amount
- Supplier invoices or purchase orders
- Existing cash available
- Exact funding gap
- Annual business revenue
- Recent monthly deposits
- Time in business
- Current credit profile
- Existing business debt
- Expected inventory sales period
Match the Financing Structure to the Inventory Cycle
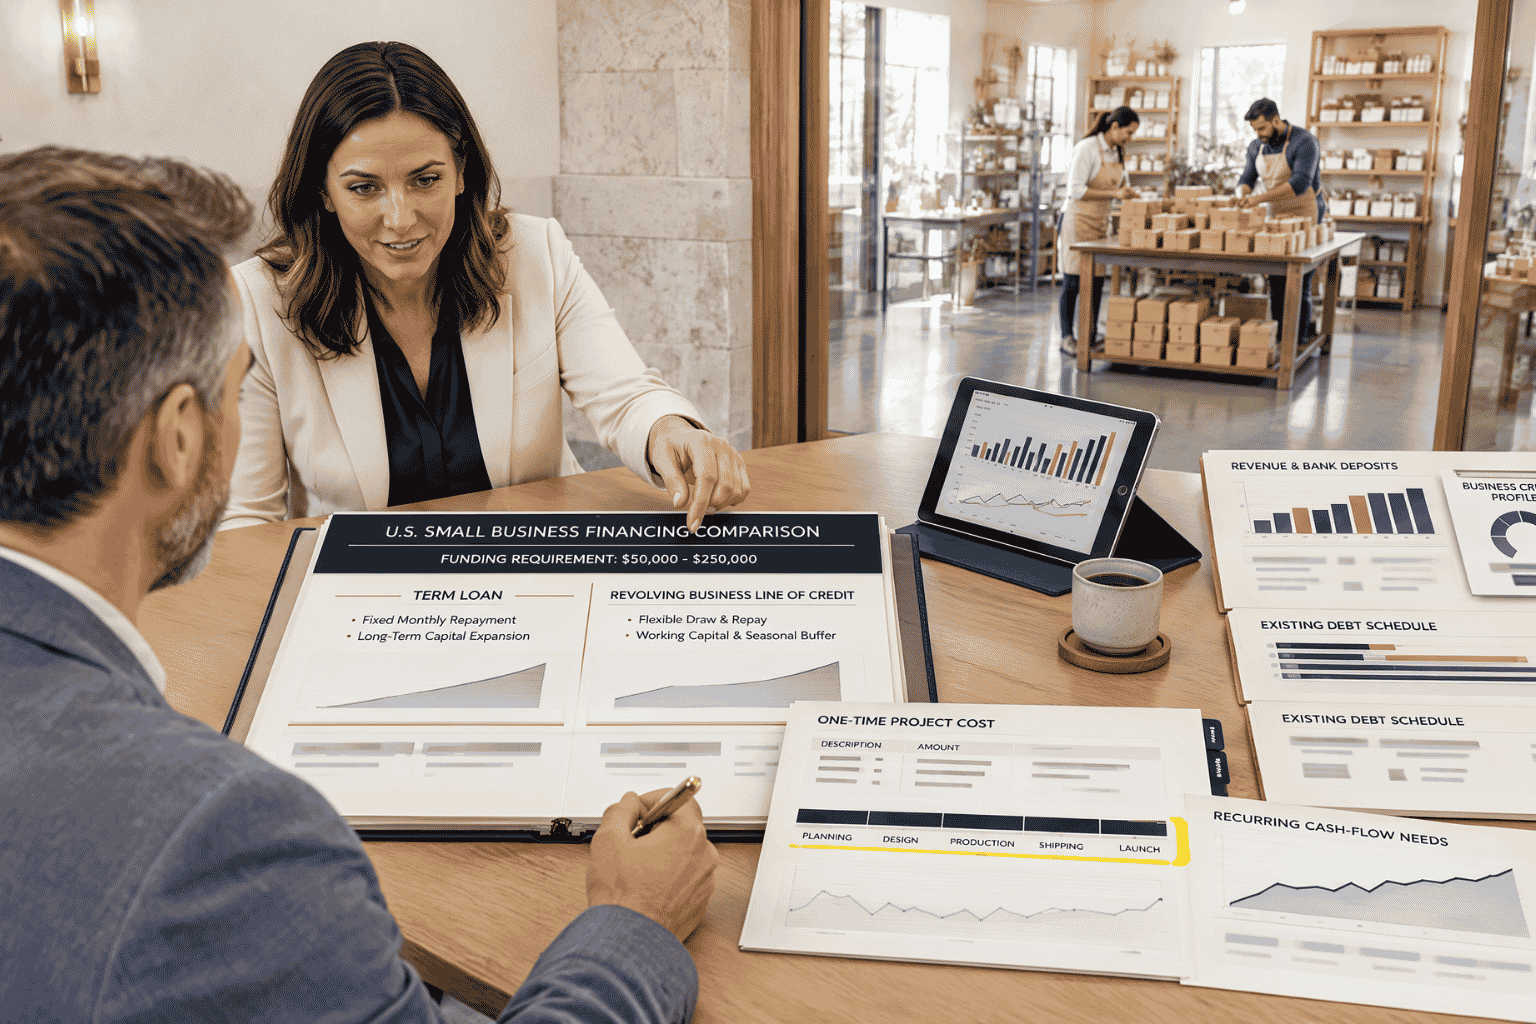
A working capital loan can make sense for a defined seasonal requirement. A business line of credit may be more useful when the company repeatedly needs access to capital.
The better choice depends on the actual cash-flow cycle, borrower profile and terms available—not simply on which product name sounds more attractive.
Holiday Sales Should Repay the Capital—Not Create Another Debt Problem
Seasonal financing works best when the inventory is tied to demonstrated customer demand and the expected gross profit can comfortably support the financing cost.
Before borrowing, calculate what happens if sales arrive later than expected or some inventory remains unsold after the holiday rush.
FAQs
Can a business use financing to purchase holiday inventory?
Potentially. Working capital, revolving credit and other funding products may support eligible inventory needs depending on the provider and borrower profile.
Is a business line of credit better than a working capital loan for holiday inventory?
It depends. A line may fit recurring funding needs, while a working capital loan may fit a more defined one-time seasonal requirement.
Can I obtain a business line of credit with only an EIN?
An EIN identifies the business, but providers may still review personal credit, business age, revenue, cash flow and other underwriting factors.
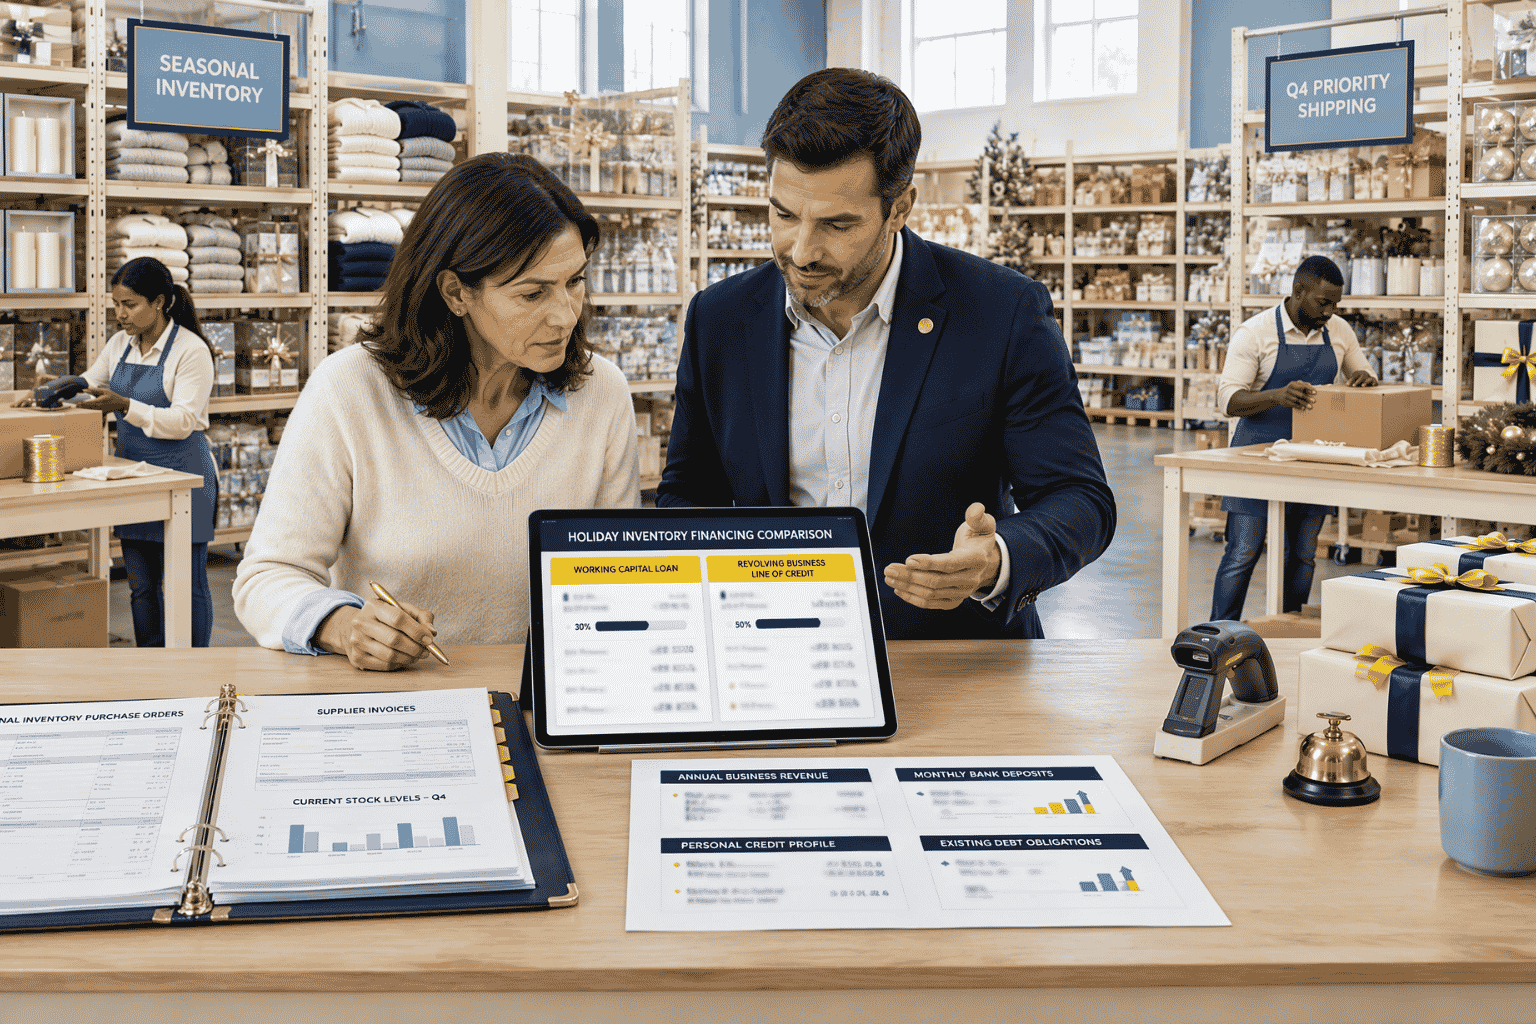 Seasonal inventory financing should be based on the real supplier-payment and customer-sales cycle.