Business Loan Underwriting Checklist: 9 Factors to Review Before You Apply Again
If a previous business-funding application did not produce the result you expected, submitting the same profile repeatedly may not solve the problem. Start by reviewing the core factors funding providers commonly consider.
If your business still has an active capital need, complete the EIN Business Funding Quick Lead Pre-Qualification using your current information.
1. Personal Credit
Personal credit remains a common underwriting factor across many small-business financing products.
2. Business Credit
If an established business credit profile exists, a funding provider may consider it alongside other borrower information.
3. Time in Business
Operating history can materially affect the financing categories worth evaluating. Some products may consider businesses after six to twelve months, while traditional products often require longer histories.
4. Annual Revenue
Revenue helps show the scale of the business and can be an important qualification benchmark.
5. Cash Flow
Funding providers may evaluate whether the company generates enough cash to support normal operations and another financing obligation.
6. Existing Debt
Open loans, credit lines and business credit-card balances affect the overall repayment profile.
7. Industry
Industry risk can be part of lender underwriting, particularly for more traditional financing.
8. Collateral
Some financing products or larger requests may involve collateral, depending on the provider and structure.
9. Personal Guarantee
Personal guarantees are common in several small-business financing categories. Requirements vary by product and lender.
What Should You Change Before Applying Again?
Update your credit information, current revenue, bank activity, debt balances and use of funds. A current profile is more useful than relying on numbers from an earlier application.
If your business still needs capital, complete the EIN Business Funding pre-qualification before submitting another broad round of applications.
FAQs
What factors do business lenders commonly review?
Common factors include personal credit, business credit if established, time in business, annual revenue, cash flow, debt obligations, industry, collateral for some financing and personal guarantees.
Does meeting common lender benchmarks guarantee approval?
No. Approval depends on the provider, financing product and complete borrower profile.
Should I update my information before applying again?
Yes. Use current credit, revenue, bank activity, debt balances and funding requirements so the next review reflects the business as it operates today.
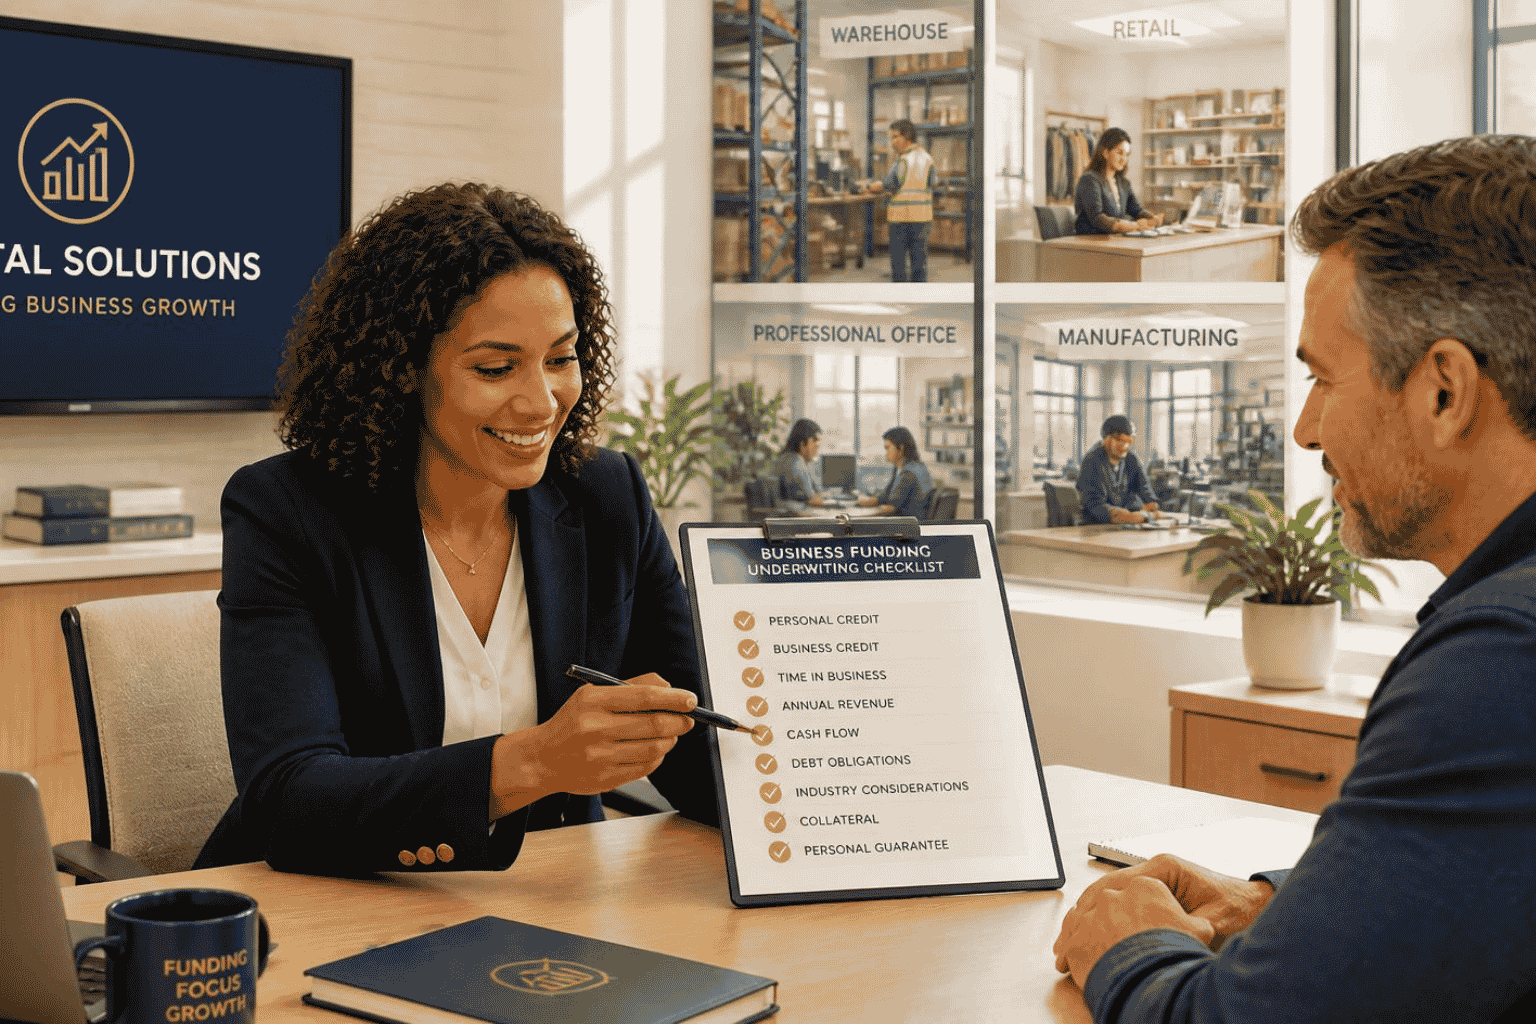 Before another funding application, review the credit, revenue, cash-flow and debt factors that commonly shape underwriting.