Business Sale Financing Contingency: What Sellers Should Require Before Taking the Company Off Market
A seller can receive an attractive offer, sign a letter of intent and remove the business from active marketing—only to discover weeks later that the buyer never had a realistic financing plan.
That can cost the seller time, momentum and potentially other qualified buyers. When an offer depends on business acquisition financing, financing readiness should be considered alongside price and other transaction terms.
What Is a Financing Contingency?
A financing contingency generally means the buyer’s obligation to complete the purchase depends on obtaining financing under the terms defined in the transaction documents.
The exact legal language matters. Sellers should work with qualified transaction counsel when negotiating a letter of intent or purchase agreement rather than relying on generic language.
Why Financing Readiness Matters Before Exclusivity
Once the seller agrees to exclusivity or otherwise stops actively marketing the company, the buyer gains valuable time to complete diligence and arrange capital.
If the buyer has not yet calculated the purchase-price funding gap, the seller may be giving up market exposure while the buyer starts from the beginning.
Ask How Much Cash the Buyer Has Available
The seller does not necessarily need every detail of the buyer’s personal finances, but the transaction should have a credible source of buyer contribution.
An offer based on the assumption that the entire purchase price will be financed can require much more scrutiny than one supported by a realistic capital plan.
Ask How Much Outside Financing Is Required
A $1 million offer does not necessarily mean the buyer needs a $1 million loan.
The funding structure may include buyer cash, seller financing and outside acquisition capital.
The seller should understand the approximate financing requirement rather than accepting a vague statement that the buyer will “get a business loan.”
Ask Whether the Buyer Has Started Pre-Qualification
Pre-qualification does not guarantee that a lender will fund the transaction, but it can help determine whether the buyer’s credit, contribution and financing requirement appear aligned with a realistic funding path.
A buyer who has organized these details is further along than one who plans to begin searching for financing after the seller removes the company from the market.
If the buyer needs acquisition financing, the buyer can complete the EIN Business Funding Quick Lead Pre-Qualification using the purchase price, contribution and approximate amount required.
Understand the Target Company’s Role in Financing
Acquisition financing is not based solely on the buyer.
The target company’s revenue, cash flow, existing debt, operating history and financial records may affect whether the proposed transaction can support financing.
Sellers should therefore have organized financial information ready for legitimate buyer and lender review under the appropriate confidentiality process.
Do Not Hide Existing Business Debt
Open loans, lines of credit, equipment obligations and other company liabilities can change both the transaction structure and the company’s post-closing cash flow.
Unexpected debt discovered late in the process can create a financing problem after both parties have already invested significant time in the deal.
Seller Financing Should Be Defined Early
If the buyer expects the seller to finance part of the purchase price, that expectation should not appear at the last minute.
The seller should understand the proposed amount, repayment structure and how the seller note interacts with the buyer’s outside acquisition financing.
Seller financing creates real financial exposure for the seller and should be reviewed carefully with the seller’s professional advisers.
Set a Realistic Financing Timeline
A transaction should include enough time for legitimate underwriting without allowing an unprepared buyer to control the listing indefinitely.
The appropriate timeline depends on the financing product, transaction size, documentation and diligence requirements.
Sellers should consider milestones rather than relying only on one distant closing date.
What Financial Information Should the Seller Prepare?
- Current and historical revenue information
- Profit and loss information
- Existing business debt
- Major equipment obligations
- Ownership and entity information
- Supporting financial documentation appropriate to the transaction
Organized information can help a qualified buyer move through financing review more efficiently.
High Price Is Not the Same as High Closing Probability
A slightly higher offer can be less valuable if the buyer has no credible capital plan.
Sellers should evaluate price together with buyer contribution, financing readiness, transaction complexity and the probability of closing.
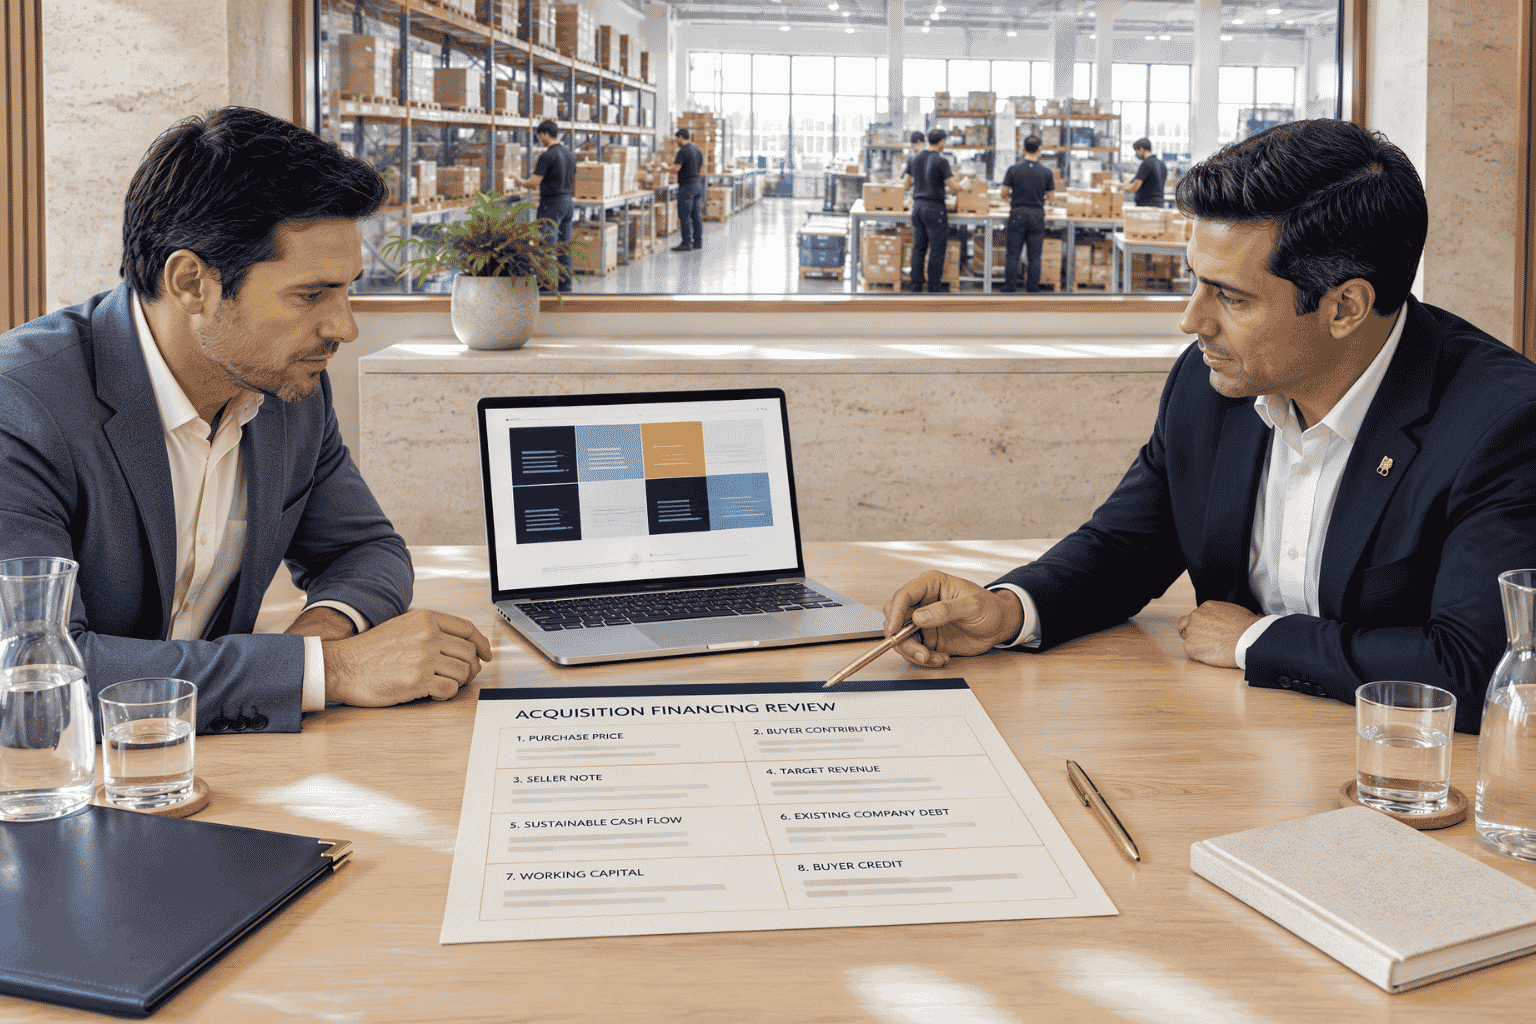
What Should Be Clarified Before Taking the Company Off Market?
- Purchase price
- Buyer contribution
- Outside financing requirement
- Any seller-financed amount
- Whether pre-qualification has begun
- Financing timeline
- Due-diligence milestones
- Expected closing date
A Financeable Buyer Protects the Seller’s Time
The purpose of financing readiness is not to eliminate every transaction risk. It is to avoid spending weeks or months on a buyer whose funding assumptions were unrealistic from the beginning.
If a serious buyer needs financing to complete the acquisition, encourage the buyer to clarify the capital requirement early through the EIN Business Funding pre-qualification before the transaction becomes dependent on an untested financing plan.
FAQs
Should a seller accept an offer that depends on financing?
It can be reasonable, but the seller should understand the buyer’s contribution, financing requirement, readiness and expected timeline before relying on the offer.
Does buyer pre-qualification guarantee the business sale will close?
No. It can help identify whether a financing path appears worth evaluating, but final approval depends on underwriting, documentation and the complete transaction.
Should seller financing be discussed before the business is taken off market?
Yes. If seller financing is expected to be part of the deal, the amount and proposed structure should be addressed early rather than introduced immediately before closing.
 Before taking a business off market, sellers should understand whether the buyer has a realistic acquisition financing plan.