Need $50K–$250K for Your Business? Check These 7 Funding Factors Before You Apply
When a business owner says, “I need $100,000” or “I need $250,000,” the amount alone does not identify the right financing product. The provider still needs to understand what the capital will do and whether the company has a profile capable of supporting the requested amount.
For many small businesses, requests between roughly $50,000 and $250,000 can involve working capital, equipment, inventory, expansion, term financing or other business needs. The best starting point is not the product name—it is the borrower profile.
If you already know the amount you need and why you need it, complete the EIN Business Funding Quick Lead Pre-Qualification using your current credit, revenue, business age and existing debt.
1. What Is Your Current Credit Score?
Know the actual current score rather than describing credit as simply good or bad.
Different financing categories can use very different credit profiles. Working-capital and online financing may begin around lower credit ranges than traditional bank financing, while stronger-credit borrowers may have more products and structures to compare.
A lower score does not answer every funding question, but it can materially change which options are realistic.
2. How Long Has the Business Been Operating?
Operating history helps a funding provider determine how much real business performance is available to review.
A company with six months of bank activity presents differently from a business with two or five years of financial history.
The EIN Business Funding guidance identifies six to twelve months as a common benchmark for some working-capital and alternative financing profiles, while term loans commonly begin around one or more years in business.
3. What Is the Annual Revenue?
Revenue helps establish the size of the business and provides context for the amount requested.
A $200,000 financing request may be evaluated very differently for a business generating $150,000 annually than for a company generating $1 million.
Revenue should be current and supported by real business activity.
4. What Do Recent Bank Deposits Look Like?
Annual revenue is important, but lenders may also want to understand what is happening today.
Recent business deposits can show whether customers are actively paying the company and whether revenue is relatively consistent.
This can be especially relevant to online and alternative financing.
5. Is Cash Flow Positive?
Revenue and cash flow are different.
A company can generate substantial sales while having very little cash available after payroll, rent, inventory, supplier payments and other expenses.
A new financing payment needs to fit alongside those operating costs.
6. How Much Existing Business Debt Is Already Open?
Prepare every business loan, credit line and business credit-card obligation.
For each account, know the lender or card name, applicable limit, current balance and open date.
Existing debt can materially reduce the amount of additional repayment the company can support.
7. What Exactly Will the $50K–$250K Be Used For?
The use of funds can determine which financing structure should be evaluated.
- Equipment purchase
- Inventory
- Working capital
- Payroll timing
- Expansion
- Renovation or build-out
- Another clearly defined business expense
“Business growth” is usually too broad. A defined use of funds gives the financing request a real purpose.
What if You Have 600–680 Credit?
Online or alternative business financing may be worth reviewing depending on the complete profile.
The EIN Business Funding guidance identifies approximately 600 to 680+ credit, six to twelve months in business and approximately $50,000 to $250,000+ annual revenue as common alternative-financing benchmarks.
Consistent deposits and business bank statements can also matter.
What if You Have 700+ Credit and $250K+ Revenue?
A stronger profile can potentially create additional financing categories to compare.
The guidance describes a generally competitive borrower as having approximately 700+ personal credit, two or more years in business, $250,000+ annual revenue and positive, consistent cash flow, together with organized financial information and an established business bank account.
Those benchmarks still do not guarantee approval.
Do You Need the Full $250K?
Do not request the top of a funding range simply because it sounds attractive.
Calculate the actual capital requirement. Borrowing more than the business needs can create unnecessary repayment pressure and reduce financial flexibility.
Should You Apply Everywhere at Once?
Applying broadly before understanding the borrower profile can waste time and create a confusing funding process.
Start by identifying which product category appears to fit the credit, business age, revenue, cash flow and use of funds.
The Goal Is a Qualified Funding Request
A high-quality request is specific. The owner knows the amount needed, why it is needed, how long the company has operated, what the business generates and what obligations already exist.
Those details move the conversation from “Can I get money?” to “Does this specific financing need fit this specific business profile?”
FAQs
Can a business qualify for $50K–$250K with 600–680 credit?
Potentially. Some alternative financing profiles use approximately 600 to 680+ credit, but time in business, revenue, deposits, cash flow, debt and the funding purpose also matter.
Does $250K in annual revenue mean a business can borrow $250K?
No. Annual revenue does not directly equal borrowing capacity. Providers evaluate the complete business and repayment profile.
What should I know before submitting a business funding request?
Know your requested amount, use of funds, credit score, time in business, annual revenue, recent deposits, cash flow and existing debt.
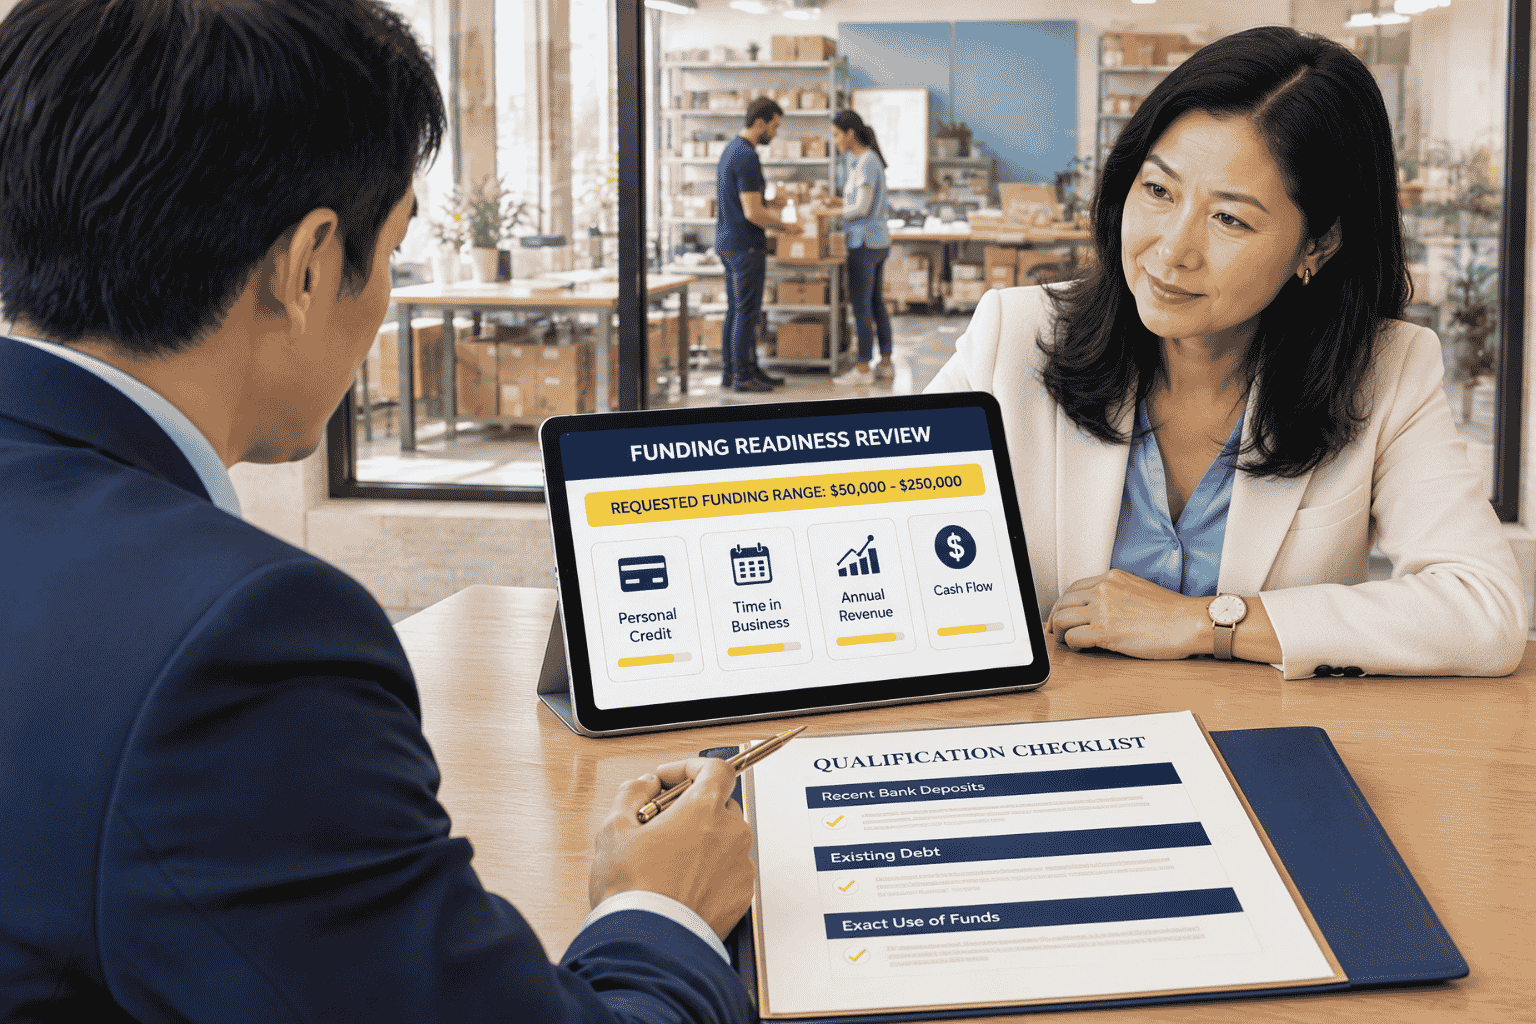 The amount requested should be evaluated together with credit, revenue, business age, cash flow and existing obligations.