Business Auto Loan With EIN for a Used Commercial Vehicle: What Lenders May Review
A used commercial vehicle can be a practical way for a delivery company, contractor, repair business or field-service operation to expand capacity without paying the cost of a brand-new vehicle.
Business owners searching for a business auto loan with an EIN should still expect the financing review to extend beyond the tax ID. The provider may need to understand both the vehicle being purchased and the financial profile of the business behind it.
If you already have a vehicle selected and know the purchase price, complete the EIN Business Funding Quick Lead Pre-Qualification using the actual vehicle cost, business revenue and current credit profile.
Can a Used Commercial Vehicle Be Financed?
Potentially. Used trucks, vans and other commercial vehicles can represent legitimate revenue-producing business assets.
Provider requirements can vary based on the type of vehicle, age, condition, value, business profile and complete transaction.
Start With the Actual Vehicle
A specific purchase is easier to evaluate than a general request for vehicle capital.
Have the purchase price, year, make, model, mileage where applicable and dealer or seller information available.
The provider may also need to understand whether the vehicle is being purchased from a dealer or through another type of transaction.
Why Vehicle Age and Condition Matter
The useful economic life of a vehicle affects the financing decision.
A used commercial vehicle should remain productive long enough for the repayment structure to make business sense.
A lower purchase price is not necessarily attractive if the vehicle will immediately require major repairs or replacement.
Does an EIN Mean the Loan Is EIN-Only?
No. The EIN identifies the business, but financing providers may still review personal credit, business credit if established, business age, revenue, cash flow and existing obligations.
Search terms such as “business auto loan with EIN” describe what business owners are looking for; they should not be interpreted as a promise that an EIN alone determines eligibility.
How Does Business Revenue Affect the Request?
Revenue helps show that the company has active operations capable of supporting a vehicle payment.
A provider may also consider recent deposits and whether the requested vehicle cost is reasonable relative to the size of the business.
What if the Vehicle Is Expected to Create New Revenue?
That can strengthen the business case, but projected future revenue should not be treated as guaranteed.
The provider may still want to know whether the current business can support the payment while the new vehicle is being integrated into operations.
Existing Vehicle Debt Must Be Included
If the business already finances trucks, trailers, vans or other equipment, include those obligations in the debt schedule.
Another vehicle increases productive capacity but also increases fixed monthly obligations.
What About Upfitting?
Commercial vehicles frequently require additional equipment.
- Shelving
- Tool storage
- Refrigeration
- Specialized service equipment
- Safety equipment
- Commercial wraps or operational modifications
Identify those expenses separately from the base vehicle purchase so the total project cost is clear.
Do Not Put Fuel and Payroll Into the Vehicle Price
Fuel, insurance, driver payroll and other ongoing operating expenses are different from the physical vehicle.
If adding the vehicle also creates a working-capital need, calculate that amount separately.
Why Does Current Credit Matter?
Commercial vehicle financing can still involve the owner’s credit profile, particularly for smaller businesses.
Know the current score instead of assuming the vehicle itself eliminates credit considerations.
What if the Business Has One Year of Operating History?
One year gives the provider more real business information to review than a newly formed company. Annual revenue, deposits and existing debt can help show how the business operates.
Minimum business-age requirements vary by provider and financing structure.
What Should Be Ready?
- Vehicle purchase price
- Vehicle year and description
- Mileage or condition information
- Upfitting costs
- Legal business name and EIN
- Business formation date
- Annual revenue
- Recent bank deposits
- Current credit profile
- Existing vehicle and business debt
Used Can Be a Good Business Decision—if the Numbers Work
A used commercial vehicle can reduce the initial investment and help a growing business add capacity more efficiently.
The correct financing decision should still consider expected vehicle life, maintenance requirements, business cash flow and the complete repayment cost.
Match the Loan to a Revenue-Producing Asset
A high-intent vehicle funding request is specific: the owner knows which vehicle is being purchased, what it costs, how it will be used and what financial profile supports the purchase.
That creates a much stronger starting point than simply asking whether an EIN can be used to get an auto loan.
FAQs
Can a business get financing for a used commercial vehicle with an EIN?
Potentially. The EIN can be part of the business application, while the provider may also review credit, revenue, operating history, existing debt and the vehicle itself.
Does the age of a used work vehicle matter?
Potentially. Providers may consider vehicle age, condition, value and expected useful life when evaluating the transaction.
Should vehicle upfitting be included in the financing request?
Upfitting costs should be identified separately from the base vehicle so the provider can understand the complete project cost.
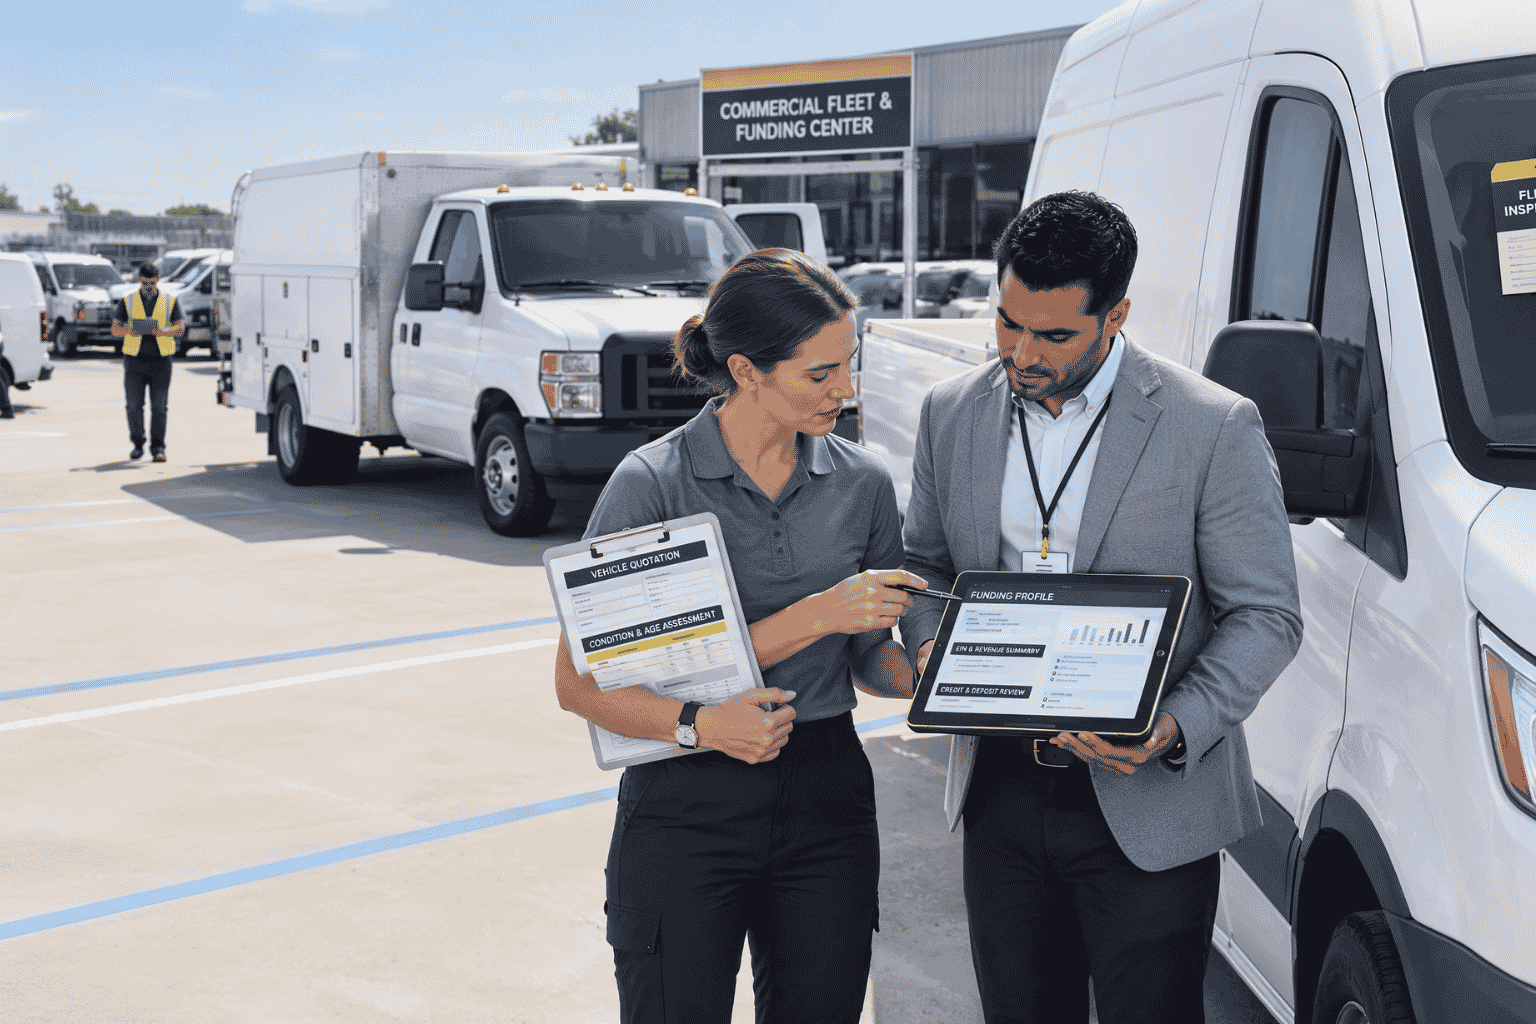 Used commercial vehicle financing can depend on both the asset and the financial profile of the business purchasing it.