Medical Device Inventory Financing: When Asset-Based Lending May Fit a Growing Healthcare Supplier
A growing medical device distributor can look financially strong on paper while still facing a significant cash-flow problem. The company may purchase inventory well before hospitals, clinics, distributors or other commercial customers pay their invoices.
That can leave substantial capital tied up in inventory and accounts receivable at the same time the business needs cash to purchase the next round of products.
If inventory growth is creating an active capital need, complete the EIN Business Funding Quick Lead Pre-Qualification with current revenue, inventory needs and existing debt information.
What Is the Core Funding Problem?
The business may be profitable but still experience a timing gap between paying suppliers and collecting customers.
For medical-device businesses, that gap can become significant when products are expensive, inventory levels must remain high or large institutional customers use extended payment terms.
Why Asset-Based Lending May Be Worth Evaluating
Asset-based lending generally focuses heavily on eligible business assets that can support a borrowing structure. Depending on the provider, accounts receivable, inventory or other qualifying assets may be relevant.
That does not mean every inventory item or receivable will be treated equally. Eligibility, concentration, age, marketability and documentation can matter.
Why Medical Device Inventory Can Be Different
Healthcare inventory may involve expiration dates, regulatory requirements, specialized buyers, controlled distribution channels or products that cannot be resold easily outside their intended market.
A funding provider may therefore want to understand what the inventory is, who buys it and how quickly it normally converts into sales.
Accounts Receivable May Matter Too
If the company has already delivered products and is waiting for commercial customers to pay, receivables may represent another important part of the working-capital picture.
The quality of the customer and the age of the invoice can matter more than simply the total dollar amount outstanding.
What Should the Supplier Know About Inventory?
- Total inventory value
- Products currently held
- Average inventory turnover
- Any expiration or obsolescence concerns
- Supplier payment terms
- Large customer concentration
- Amount of new inventory being purchased
What Business Information Still Matters?
An asset-based structure does not make the operating business irrelevant.
Funding providers commonly review personal credit, business credit if established, time in business, annual revenue, cash flow, debt obligations and industry.
The stronger and more organized the business profile, the easier it can be to understand how the assets fit into the financing request.
What Existing Debt Should Be Reviewed?
Prepare current business loans, lines of credit and business credit cards. If another lender already has a security interest in company assets, that can also become relevant to the financing discussion.
The objective is to understand what assets and cash flow are already supporting existing obligations.
What If the Need Is Simply Short-Term Working Capital?
A broader working-capital loan may also be worth evaluating depending on the size and profile of the company.
The EIN Business Funding guidance identifies approximately 600+ personal credit, six to twelve months in business and roughly $50,000 to $100,000 in annual revenue as common working-capital benchmarks.
A healthcare supplier with a more substantial asset base or larger financing need may require a different structure.
Do Not Request Capital Without Identifying the Timing Gap
Calculate how much money is tied up between supplier payment and customer collection.
If the company pays $200,000 for inventory and expects customers to pay 45 to 60 days after delivery, that timing information is more useful than simply requesting “growth capital.”
What Should Be Ready for an Initial Review?
- Annual business revenue
- Current inventory value
- Inventory purchase requirement
- Accounts receivable information
- Customer payment terms
- Supplier payment terms
- Current credit profile
- Existing business debt
- Requested financing amount
- Specific use of funds
Asset-Based Financing Is About More Than Having Assets
The assets need to support a realistic financing structure. Inventory that is difficult to sell or receivables that are severely overdue may not provide the same financing value as current, marketable assets and high-quality commercial receivables.
For a growing healthcare supplier, the goal is to connect the funding request directly to the inventory and receivables cycle that is creating the cash requirement.
EINBF’s organic search data has already recorded the specific query “asset-based lending for medical device inventory,” making this a relevant search-intent topic as well as a practical funding need.
FAQs
Can medical device inventory support an asset-based financing request?
Potentially. Eligibility depends on the provider, type and quality of inventory, business profile and other assets or receivables supporting the request.
Can accounts receivable also matter in asset-based lending?
Potentially. Some asset-based structures can consider eligible business receivables, although customer quality, invoice age and other factors may affect eligibility.
Should inventory financing be based only on the total inventory value?
No. Product type, marketability, turnover, age and other characteristics can affect how a provider evaluates inventory.
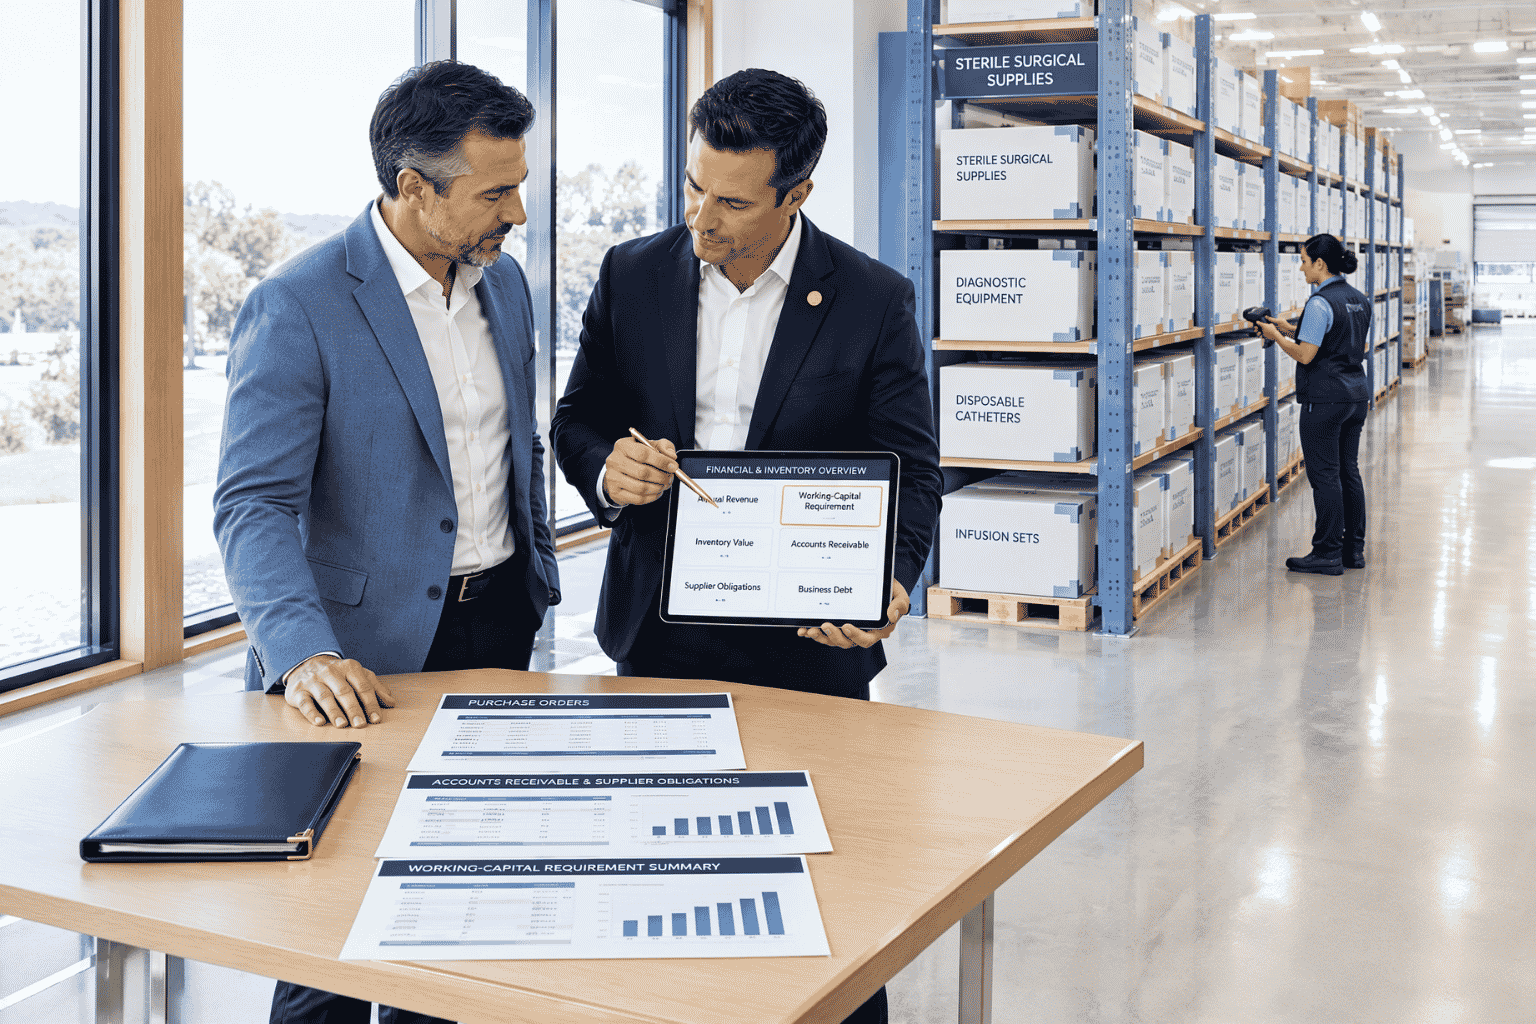 Healthcare suppliers can have substantial cash tied up between purchasing inventory and collecting commercial customer payments.