Selling a Business to a Buyer Who Needs Financing: 7 Questions to Ask Before Accepting the Offer
A seller can receive an attractive offer and still end up with a closing problem if the buyer has not thought through the financing.
Price matters, but so does the buyer’s ability to fund the transaction. Before accepting an offer that depends heavily on outside capital, the seller should understand how the buyer expects the purchase to be financed.
1. How Much Cash Is the Buyer Contributing?
The buyer should be able to explain how much personal or business capital is available for the transaction.
A vague statement that the buyer plans to “finance everything” may be a sign that the transaction structure has not yet been developed.
2. How Much Outside Financing Is Required?
Separate the purchase price from the actual outside financing requirement.
If the business is priced at $1.5 million and the buyer has $400,000 available, the conversation should focus on how the remaining transaction need will be structured rather than simply repeating the full purchase price.
3. Is the Buyer Asking the Seller to Finance Part of the Deal?
Seller financing can be part of some transactions, but sellers should understand the amount, repayment terms, priority and risk before agreeing to carry a note.
Do not assume that seller financing automatically guarantees the buyer’s outside financing will be approved.
4. Can the Business Cash Flow Support the Proposed Debt?
The company’s revenue can attract buyers, but financing depends heavily on repayment capacity.
Buyers and sellers should understand whether the business produces enough cash after normal expenses and existing obligations to support the proposed acquisition financing.
5. What Existing Business Debt Must Be Resolved?
Open loans, lines of credit, equipment financing and business credit-card obligations should be identified before closing.
Some obligations may need to be satisfied as part of the transaction, while others may affect the valuation or the amount of cash available after the sale.
6. Does the Buyer Need Additional Working Capital?
This question is frequently overlooked.
A buyer may have enough capital to complete the purchase but not enough liquidity to operate the company comfortably after closing.
Payroll, inventory, supplier payments and other normal expenses continue immediately after the transaction.
7. Has the Buyer Started a Real Funding Review?
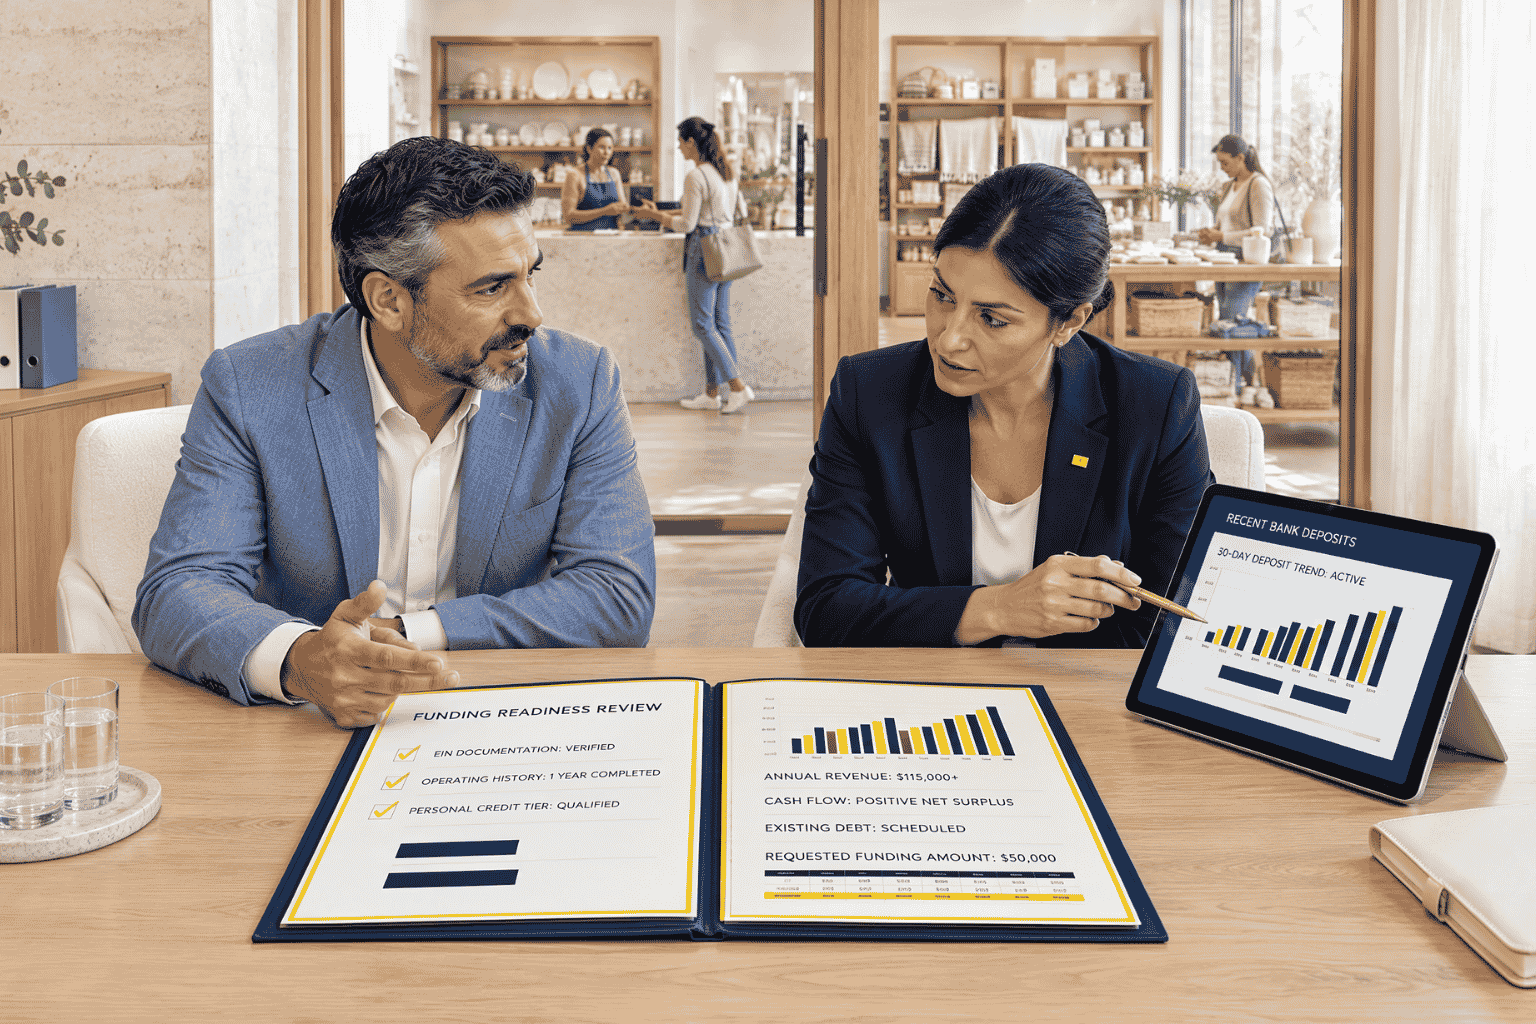
There is a meaningful difference between a buyer who says financing “should not be a problem” and a buyer who has already organized credit, contribution, business information and the amount required.
A preliminary funding review does not guarantee closing, but it can help identify obvious gaps earlier in the process.
What Should the Seller Have Ready?
A seller cannot control the buyer’s financing, but the business can prepare information a funding provider may need to evaluate the transaction.
- Annual revenue
- Current financial statements
- Existing business debt
- Cash-flow information
- Business formation and ownership information
- Major equipment or asset information
- Clear purchase price and proposed deal structure
Do Not Confuse a High Offer With a High-Probability Closing
An offer that is substantially above the buyer’s financing capacity may create more risk than a slightly lower offer supported by a realistic funding plan.
Sellers should evaluate the quality of the buyer and the financing path alongside price and other deal terms.
What If the Buyer Wants 100% Financing?
That should trigger a more detailed conversation about contribution, available collateral or other capital sources, rather than an assumption that the entire purchase can automatically be financed.
EINBF’s historical search data includes strong interest around 100% business acquisition financing and buying a business with seller financing, showing that buyers actively search for these structures. Search interest, however, does not make every transaction financeable.
A Funding Problem Discovered Early Is Easier to Solve
When buyer financing is addressed before the parties invest heavily in diligence, legal documents and closing preparation, both sides have more time to evaluate alternatives.
If your buyer has an active financing requirement, the buyer can complete the EIN Business Funding Quick Lead Pre-Qualification using the purchase price, contribution and amount needed.
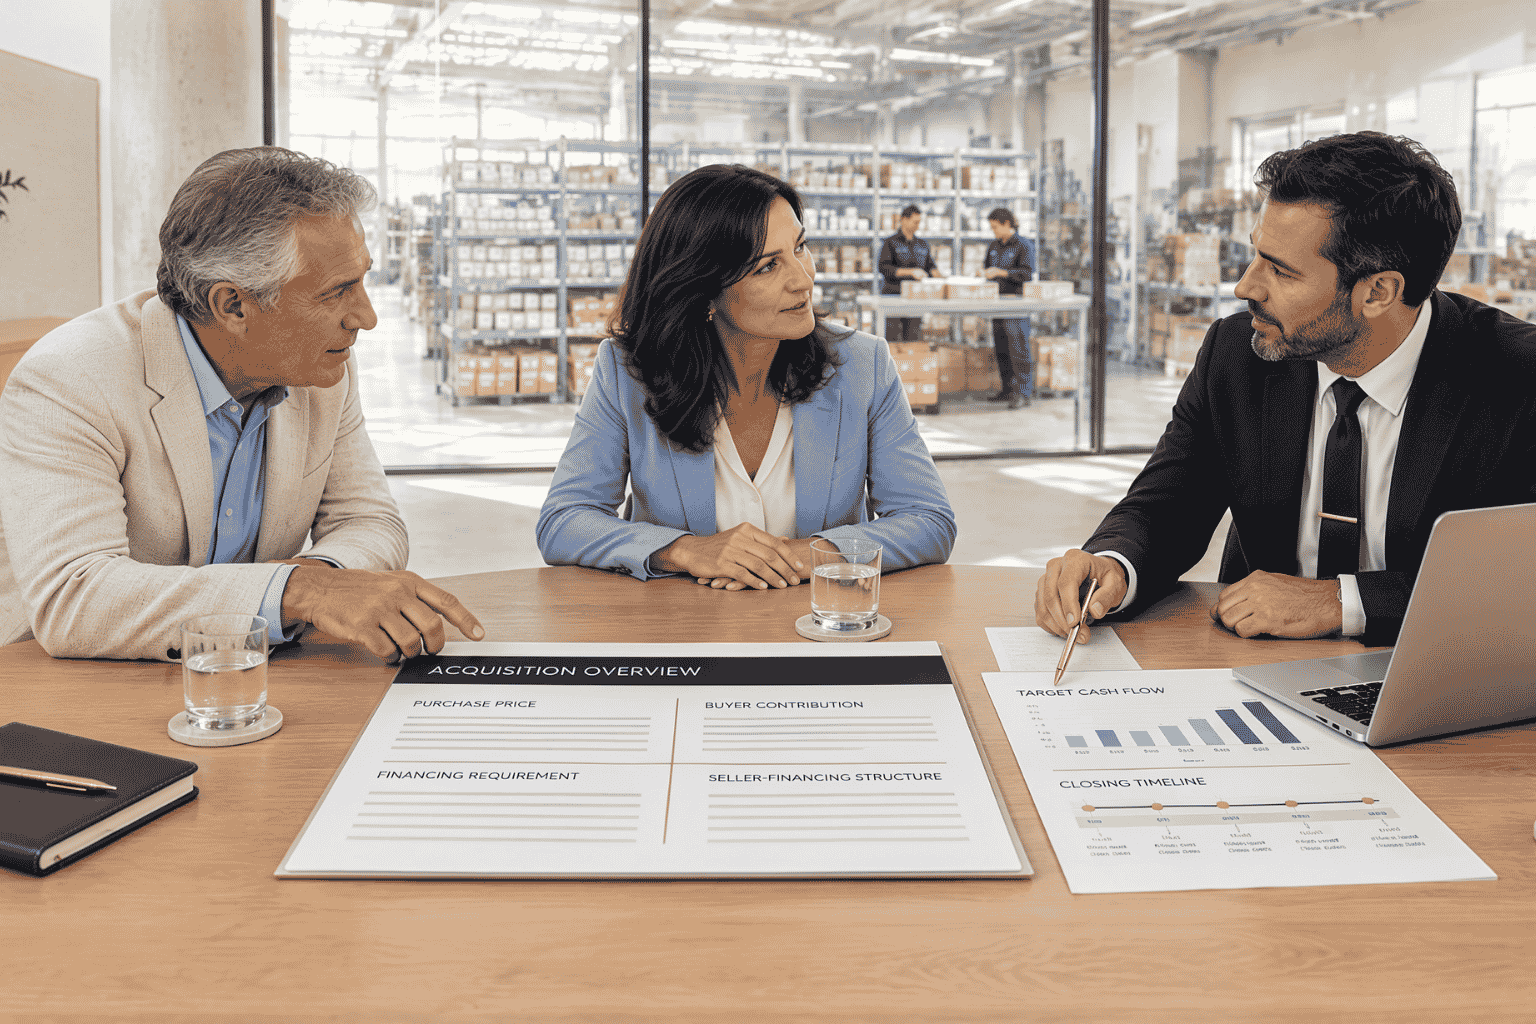 An attractive offer is more valuable when the buyer also has a realistic path to financing and closing.