Holiday Inventory Financing: Working Capital Loan or Line of Credit Before Q4 Stock Peaks?
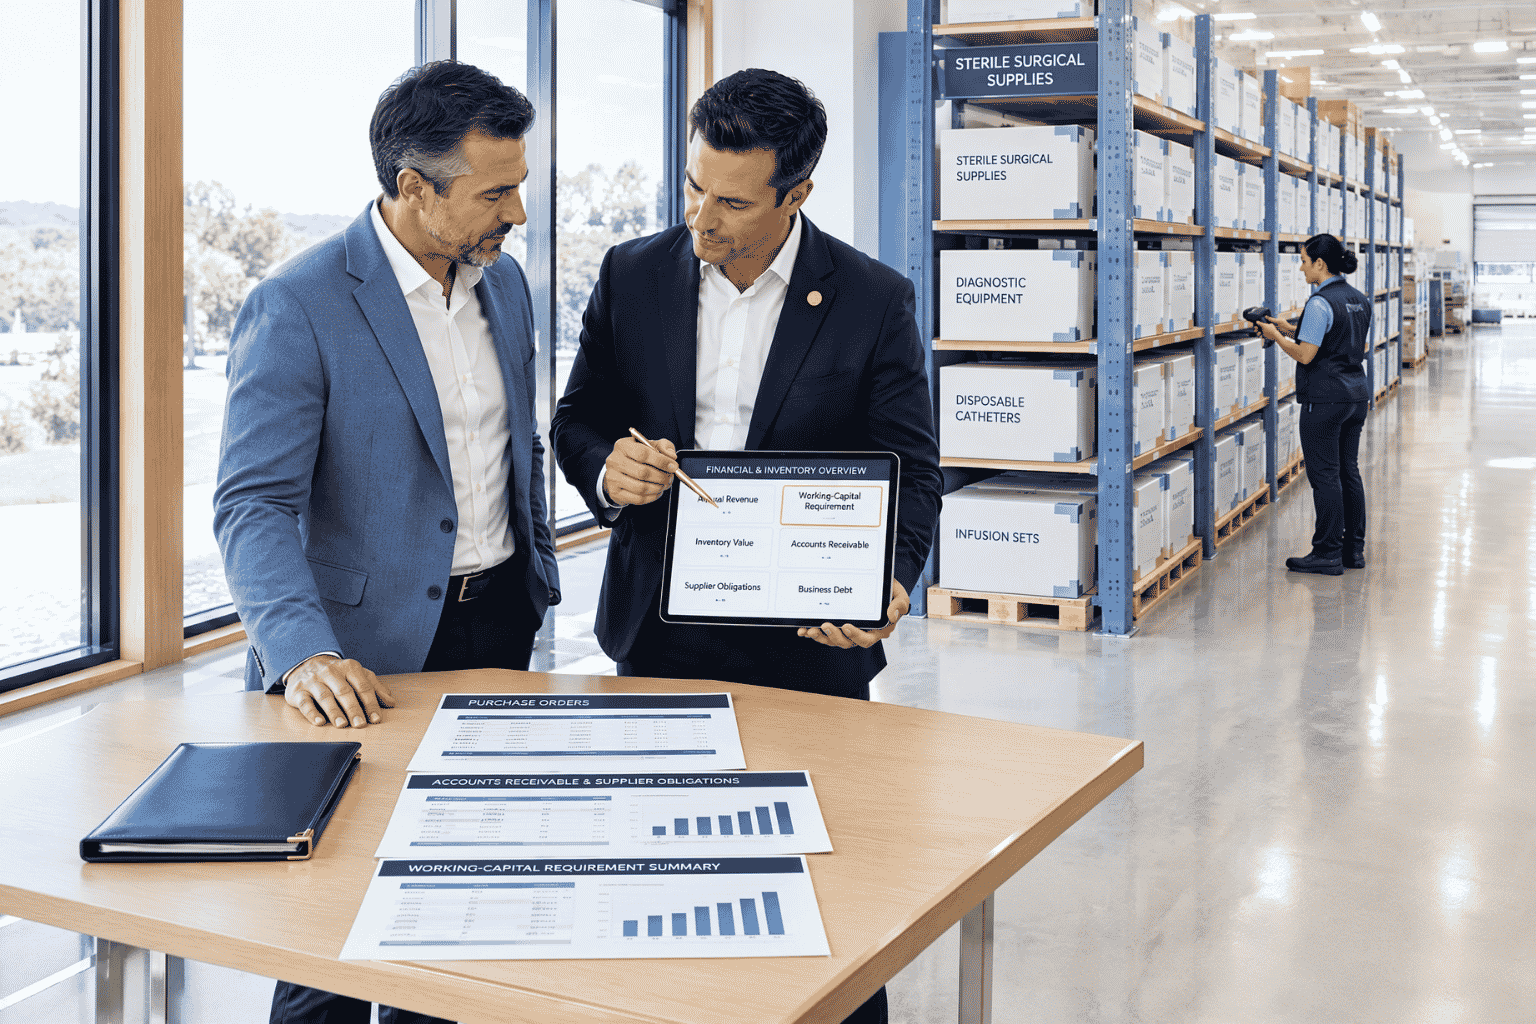
Retailers and ecommerce businesses often face their largest inventory cash requirement before the strongest selling period begins. Suppliers may need payment weeks before holiday merchandise is sold, while payroll, advertising, fulfillment and ordinary operating expenses continue at the same time.
The result can be a predictable seasonal working-capital gap even for a profitable business.
If you have supplier orders ready and need capital to purchase inventory for the upcoming sales cycle, complete the EIN Business Funding Quick Lead Pre-Qualification using the actual inventory amount and current business profile.
Start With the Inventory Purchase Requirement
Know how much inventory the business needs to buy before discussing financing.
Separate confirmed supplier orders from optimistic sales projections. A funding request tied to actual inventory purchases is more specific than simply asking for seasonal growth capital.
Why Holiday Inventory Creates a Cash-Flow Gap
The retailer pays for stock before collecting customer revenue. Depending on supplier terms, shipping timelines and sales velocity, cash can remain tied up in inventory for weeks or months.
That timing gap is the financing problem the business is trying to solve.
When May a Working Capital Loan Fit?
Working-capital financing can be relevant when the business has a defined short-term operating need such as inventory, payroll or supplier payments.
The EIN Business Funding guidance identifies approximately 600+ personal credit, six to twelve months in business and around $50,000 to $100,000 in annual revenue as common working-capital benchmarks.
Actual requirements vary by provider.
When May a Business Line of Credit Fit Better?
A revolving line can be more attractive when inventory needs repeat throughout the year rather than appearing only once.
The business can potentially draw capital when needed, repay it and use the line again subject to the provider’s terms.
Traditional Lines Usually Require a Stronger Profile
The EIN Business Funding guidance identifies approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ annual revenue and positive cash flow as common traditional business line-of-credit benchmarks.
Banks may also evaluate debt-service coverage, existing business debt, industry risk and cash-flow consistency.
What if the Retailer Has Only 6–12 Months in Business?
A younger company may have fewer traditional bank options, but online or alternative financing may use different thresholds.
The guidance identifies approximately 600 to 680+ personal credit, six to twelve months in business and roughly $50,000 to $250,000+ annual revenue as common alternative-financing benchmarks.
Recent deposits and bank statements can also matter.
Do Not Borrow Based Only on Expected Holiday Sales
Strong seasonal forecasts can be useful, but the company still needs to support the financing if sales are slower than expected.
Base the request on realistic inventory needs and the current business profile rather than assuming every purchased item will sell immediately.
How Much Inventory Should Be Financed?
Consider existing stock, confirmed purchase orders, supplier minimums, normal sell-through rates and the amount of inventory the company can reasonably carry without excessive markdown or obsolescence risk.
More inventory is not automatically better if the business must discount unsold stock later.
What Existing Debt Should Be Included?
Prepare current business credit-card balances, loans and lines of credit. Seasonal businesses sometimes accumulate debt from prior inventory cycles, which can affect the ability to take on additional financing.
Could a Merchant Cash Advance Be an Option?
Merchant cash advances may be available to some businesses with regular card sales and lower credit profiles, but the EIN Business Funding guidance identifies MCAs as generally among the most expensive financing categories.
Retailers should understand the total repayment obligation and compare other appropriate options before using expensive capital to purchase inventory.
What Should Retailers Prepare?
- Inventory purchase amount
- Supplier invoices or purchase orders
- Time in business
- Annual and recent monthly revenue
- Business bank deposits
- Current credit profile
- Existing debt
- Expected inventory-turn cycle
- Requested financing amount
Choose the Structure Based on Whether the Need Repeats
A one-time inventory purchase and a recurring inventory cycle are different financing needs.
If the business repeatedly needs capital between supplier payment and customer sales, a revolving structure may deserve consideration. If the need is a single seasonal gap, a working-capital product may be more straightforward.
The objective is to finance inventory without creating a repayment burden that remains after the seasonal opportunity has passed.
FAQs
Can a working capital loan be used for holiday inventory?
Potentially. Inventory is a common operating-capital need, although permitted uses and eligibility depend on the provider.
When may a line of credit fit better than a working capital loan?
A revolving line may be more relevant when the business has recurring inventory or cash-flow needs throughout the year.
Should a retailer borrow based entirely on expected holiday sales?
No. The financing request should also reflect current revenue, cash flow, deposits, existing debt and realistic inventory requirements.
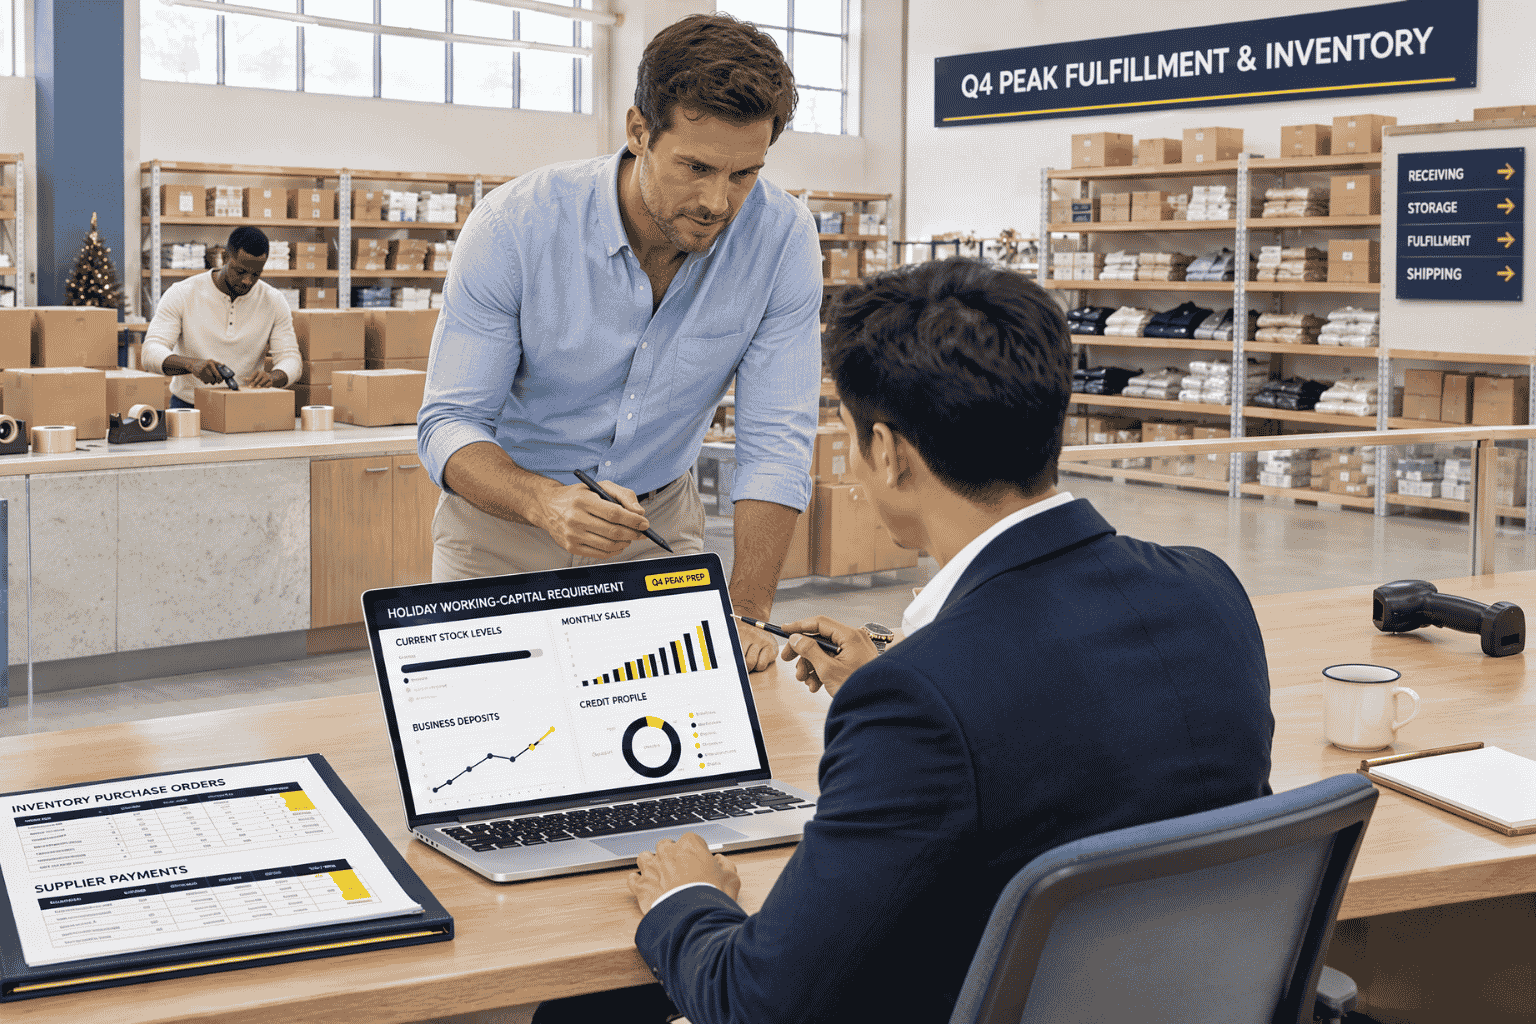 Retailers often need to pay suppliers and build inventory before peak-season customer revenue arrives.