Business Loan to Buy Into an Existing Company: Financing a Partial Ownership Purchase in 2026
Not every business acquisition involves buying 100% of a company. A key employee, manager, family member, investor or strategic partner may want to purchase a partial ownership interest while the existing owner remains involved.
That creates a different financing question from a complete change of ownership: what exactly is being purchased, how is the ownership stake valued and can the business support the transaction after the new partner comes in?
If you are actively negotiating a partial ownership purchase and know the approximate stake and purchase amount, complete the EIN Business Funding Quick Lead Pre-Qualification using the actual transaction structure.
Start With the Percentage Being Purchased
A buyer acquiring 20% of a company is entering a different ownership position from someone acquiring 49% or 80%.
Know the exact percentage being purchased and the ownership structure that will exist after closing.
How Was the Ownership Stake Valued?
The purchase price should be connected to a reasonable business valuation rather than simply dividing the seller’s desired company value by the ownership percentage.
Minority ownership, control rights, voting rights, distributions and other transaction-specific factors can affect the economics of the investment.
Appropriate legal and valuation professionals should address those issues as part of the transaction.
Can SBA 7(a) Financing Be Relevant to a Partial Change of Ownership?
Potentially. SBA has permitted partial changes of ownership under the 7(a) program, and its current SOP 50 10 8.1 includes updated change-of-ownership guidance.
That does not mean every partial buy-in qualifies. The business, buyer, ownership structure, repayment ability and participating lender requirements still matter.
Who Receives the Financing Proceeds?
In an ownership transaction, the use of proceeds needs to be clearly understood.
The capital may be used to purchase an interest from an existing owner, fund qualifying transaction expenses or address another permitted component of the deal depending on the financing structure.
Do not assume that capital raised for a company can automatically be used to purchase an owner’s personal shares without the transaction being structured appropriately.
What Should the Buyer Contribute?
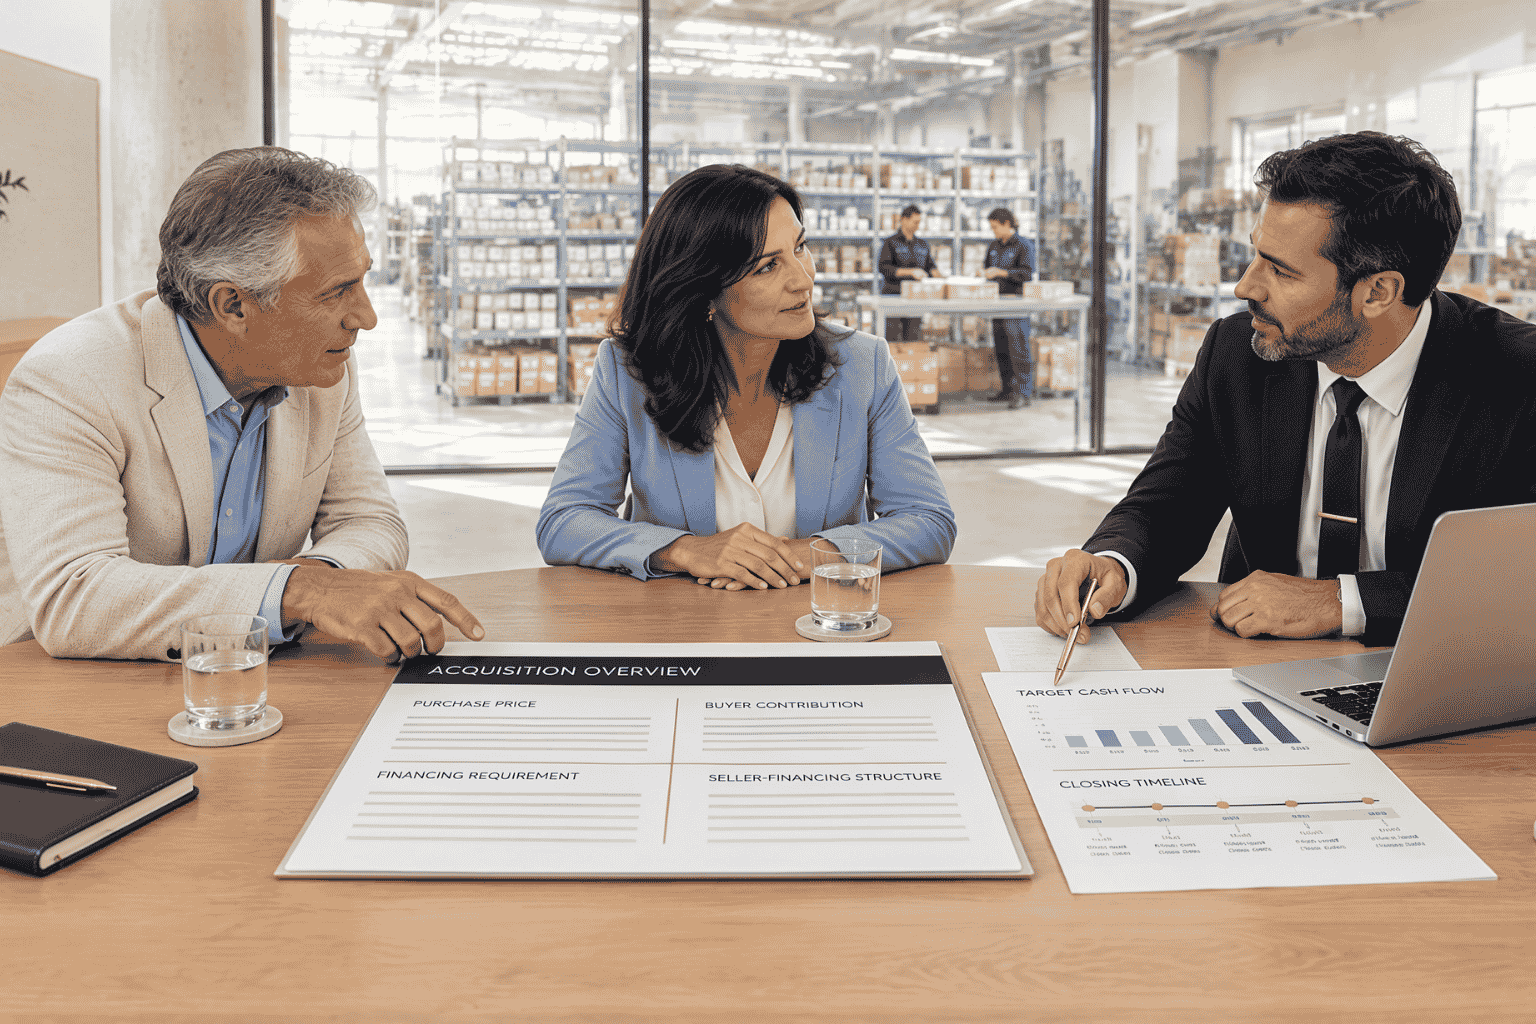
The incoming owner should know how much personal capital is available for the transaction and how much financing is required.
A buyer who has not calculated the contribution and funding gap is not yet ready for a meaningful financing discussion.
Why Does Company Cash Flow Matter?
The operating business may ultimately need to support the financing obligation.
Review annual revenue, sustainable cash flow, current debt and distributions to existing owners before assuming the company can comfortably support additional financing.
Existing Debt Must Be Included
A profitable company may already carry equipment financing, term debt, lines of credit or business credit-card obligations.
List those obligations and understand how another repayment requirement would affect available cash.
What Rights Will the New Owner Receive?
A financing review is different from legal due diligence, but the buyer should still understand the economic interest being purchased.
Ownership percentage, voting rights, management responsibilities, compensation and distribution policies can all affect the practical value of the investment.
Do Not Confuse Ownership Percentage With Repayment Ability
Buying 30% of a company does not mean the financing provider will automatically view only 30% of the company’s financial performance.
The lender will evaluate the actual transaction structure and the source expected to repay the financing.
What if the Existing Owner Stays in the Business?
That can provide continuity, but roles should be clear.
If both owners will receive compensation from the company, those expenses should be reflected realistically when evaluating future cash flow.
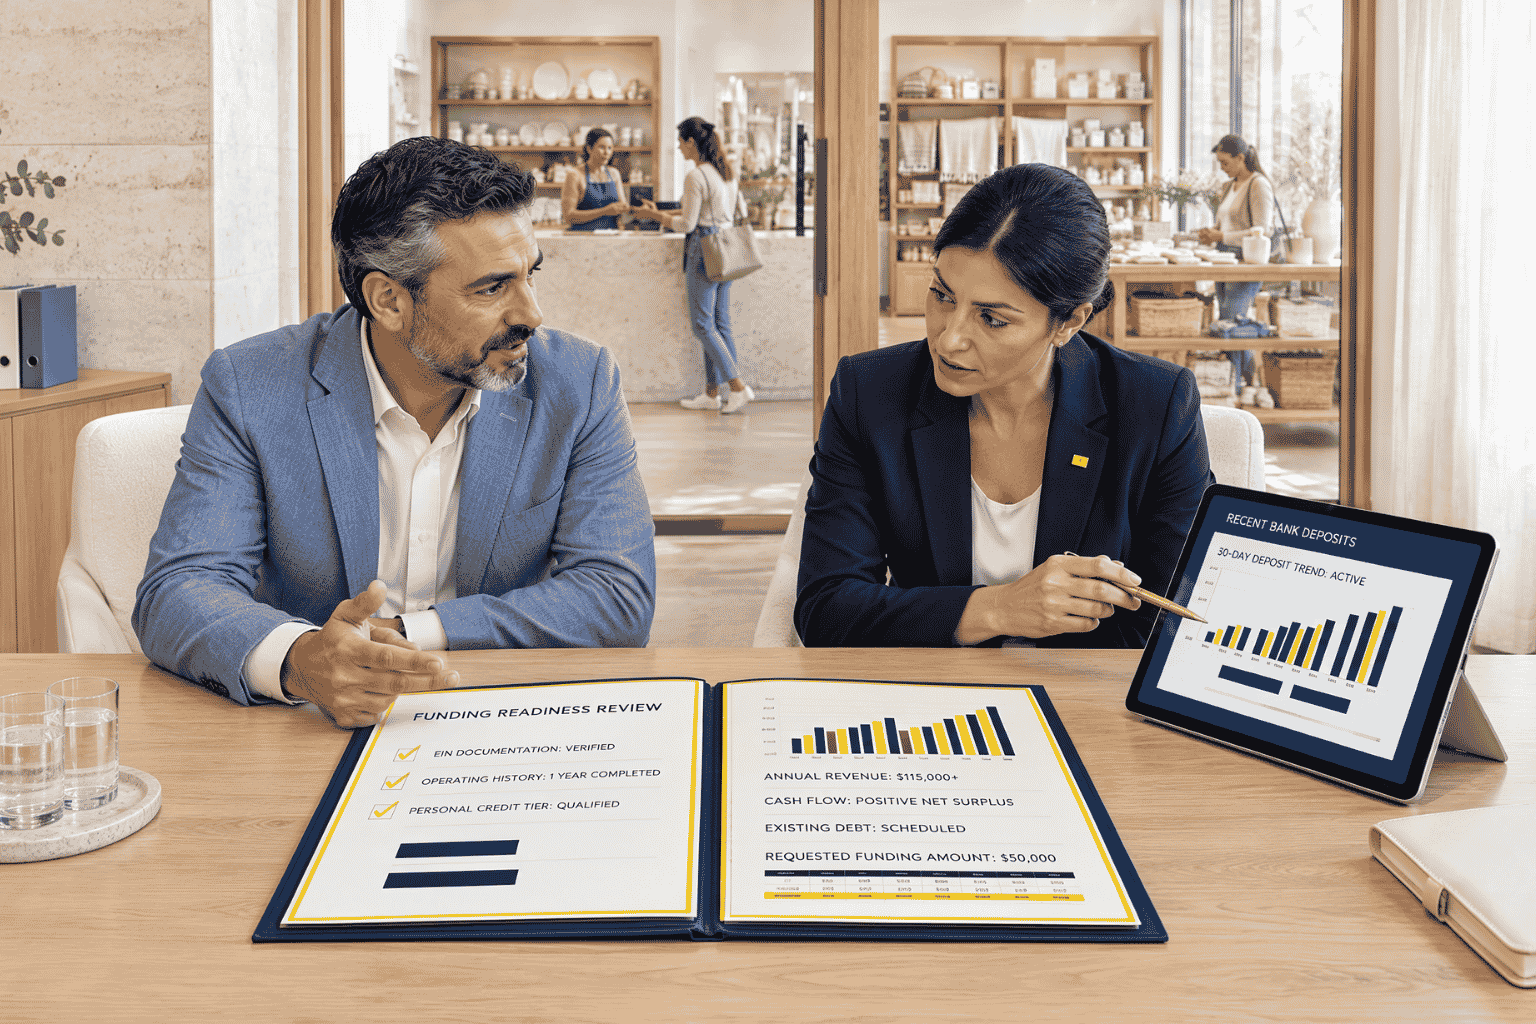
What Should Be Ready Before Funding Review?
- Total company valuation
- Percentage being purchased
- Purchase price for the ownership interest
- Buyer contribution
- Outside financing required
- Post-transaction ownership percentages
- Annual business revenue
- Business cash flow
- Existing company debt
- Buyer credit profile
Partial Ownership Financing Needs a Clear Transaction Story
A lender should be able to understand who owns the company before closing, who owns it afterward, how much money changes hands and how the financing will be repaid.
When those answers are unclear, the financing request can become difficult to evaluate even if the underlying business is profitable.
Buy the Right Stake, Not Just an Available Stake
For the incoming owner, financing should be only one part of the decision. The buyer should also understand governance, valuation, distributions and the economic rights attached to the ownership interest.
A financeable transaction is valuable only when the underlying ownership investment also makes business sense.
FAQs
Can a loan be used to buy part of an existing business?
Potentially. Financing options depend on the transaction structure, ownership change, business performance, buyer profile and provider requirements.
Can SBA 7(a) financing support a partial change of ownership?
Potentially. SBA permits qualifying partial changes of ownership under its 7(a) program, subject to current program and lender requirements.
What should a buyer prepare before financing an ownership buy-in?
Prepare the business valuation, percentage being purchased, purchase price, buyer contribution, ownership structure, company revenue, cash flow, debt and buyer credit profile.
 A partial ownership buy-in requires a clear valuation, purchase structure, buyer contribution and post-transaction ownership plan.