Business Acquisition Loan Due Diligence: 10 Financial Red Flags to Resolve Before Lender Review
A buyer can find the right company, agree on a reasonable purchase price and still lose valuable time when the financing review uncovers problems that should have been identified earlier.
Business acquisition financing is not based only on the buyer’s credit or the seller’s asking price. A lender may need to understand whether the target company’s financial performance, existing obligations and post-closing cash flow can realistically support the transaction.
If you have already identified a business to acquire and know the approximate purchase price, buyer contribution and outside funding requirement, complete the EIN Business Funding Quick Lead Pre-Qualification before relying on financing assumptions in the final deal structure.
1. Revenue Does Not Reconcile Across the Financial Records
The revenue shown in tax information, profit and loss statements, bank activity and seller-prepared summaries should tell a reasonably consistent story.
Small timing differences or accounting adjustments may have legitimate explanations. Large unexplained differences deserve investigation before the buyer uses those numbers to justify the purchase price or acquisition loan amount.
2. Seller Add-Backs Are Doing Too Much of the Work
Add-backs can be legitimate when expenses are truly nonrecurring, discretionary or specific to the current owner. But a business becomes harder to evaluate when most of its apparent cash flow depends on aggressive adjustments.
For every material add-back, buyers should ask whether the expense will genuinely disappear after closing.
3. The Seller Performs a Job the Buyer Must Replace
An owner-operated company may appear highly profitable partly because the seller performs management, sales, technical or operational functions personally.
If the buyer must hire a replacement employee after closing, that new compensation expense should be included when estimating sustainable future cash flow.
4. Existing Business Debt Is Incomplete or Unclear
Buyers should identify all open business loans, lines of credit, equipment obligations and business credit-card balances.
For each obligation, determine the current balance, payment, collateral if applicable and what happens to the debt at closing.
A transaction structured as though the company is debt-free can change materially if previously unidentified obligations appear during lender review.
5. Bank Deposits Do Not Support the Revenue Story
Business bank activity can provide a current view of operating cash flow. If the seller reports strong current sales while deposits appear substantially weaker, the buyer should understand why.
Seasonality, multiple bank accounts or timing differences can produce legitimate variations, but material gaps should be reconciled rather than ignored.
6. Customer Concentration Is Extremely High
A business may generate healthy revenue while depending heavily on one or two customers.
If a major customer leaves after ownership changes, repayment capacity can deteriorate quickly. Buyers should understand how much revenue depends on key relationships and whether those relationships are likely to continue.
7. Major Equipment Will Need Replacement Soon
Historical cash flow may look attractive because the seller has delayed capital expenditures.
If vehicles, machinery, refrigeration, technology or other critical assets will need replacement shortly after closing, the buyer should include those costs when calculating the complete acquisition funding requirement.
8. The Buyer Has Budgeted Nothing for Post-Closing Working Capital
Closing the acquisition does not pause payroll, supplier payments, inventory purchases, insurance or normal operating expenses.
A buyer who uses nearly all available cash for the acquisition contribution can become financially strained immediately after taking ownership.
Estimate the first 60 to 90 days of operating liquidity separately from the purchase price.
9. The Purchase Price Depends on Future Growth That Has Not Happened Yet
Future contracts, expansion plans and projected revenue may help explain the opportunity, but financing should not depend entirely on performance that has not yet occurred.
Buyers should understand whether the business works financially based on a reasonable current operating profile.
10. The Buyer Has Not Calculated the Actual Funding Gap
A strong financing request separates each major source and use of capital:
- Total purchase price
- Buyer contribution
- Seller financing, if applicable
- Existing debt that must be addressed
- Outside acquisition financing required
- Equipment or improvement costs
- Post-closing working capital
The actual outside financing requirement can therefore be very different from the headline purchase price.
What Should Be Ready Before Lender Review?
Buyers should organize the transaction before submitting a serious funding request. At minimum, understand the target company’s annual revenue, cash flow, outstanding debt, ownership, major assets and the proposed purchase structure.
The buyer should also know the current personal credit profile, contribution available and amount of capital being requested.
Due Diligence Protects the Financing Plan Too
Financial due diligence is not only about deciding whether the company is worth buying. It also helps determine whether the acquisition can be financed without placing unrealistic pressure on the business after closing.
Finding a problem before lender underwriting gives the buyer more time to renegotiate price, change the capital structure, request seller participation or walk away from a transaction that no longer makes financial sense.
FAQs
What financial information should a buyer review before seeking acquisition financing?
Review available financial statements, revenue, bank activity, existing debt, seller add-backs, major asset needs and post-closing working-capital requirements.
Can strong revenue overcome heavy existing business debt?
Not automatically. Funding providers may evaluate how much cash remains after operating expenses and existing obligations before determining whether the business can support new acquisition debt.
Should working capital be included in a business acquisition funding plan?
Yes. Buyers should estimate the operating cash the company may need immediately after closing in addition to the amount required to complete the purchase.
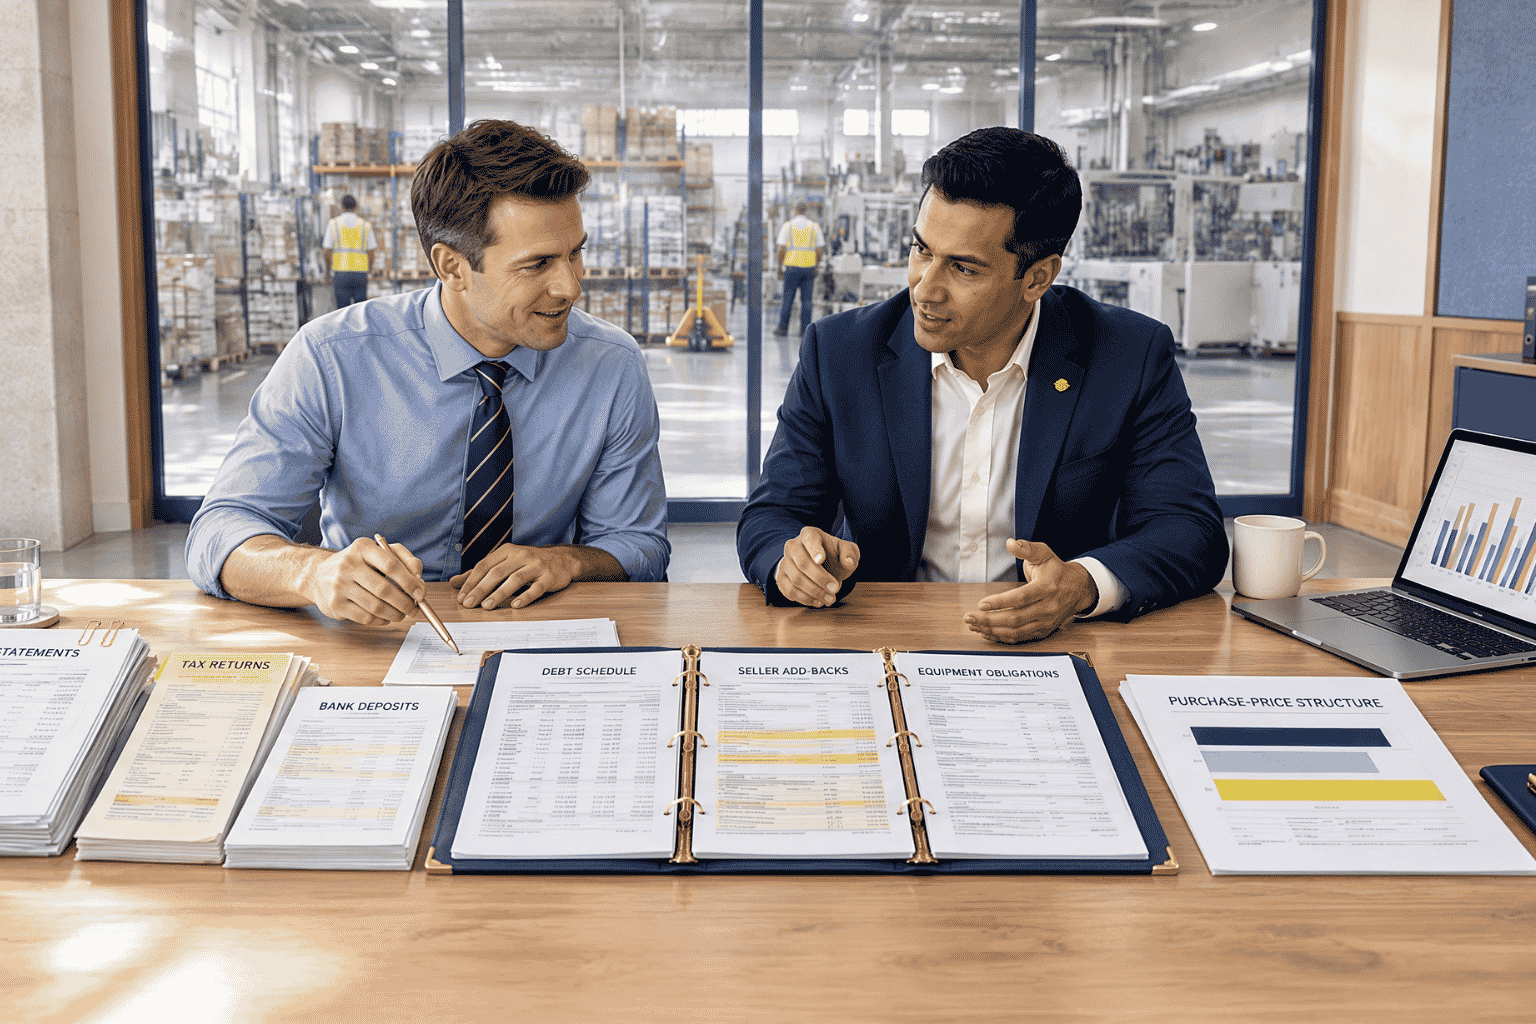 Resolving financial red flags before lender review can reduce acquisition financing problems later in the transaction.