Business Acquisition Financing With an EIN: How Much Cash Should a Buyer Keep After Closing?
Business acquisition financing is often discussed as a simple equation: purchase price minus buyer cash equals the amount that needs to be financed. In practice, that calculation can leave an important number out—the cash the buyer should still have available after the transaction closes.
A buyer who contributes nearly every available dollar toward the purchase can acquire a profitable company and still face an immediate liquidity problem. Payroll continues. Suppliers need to be paid. Inventory may need to be replenished. Equipment can require repairs. Customers may pay later than expected.
If you have already identified a business, know the approximate purchase price and are trying to determine the financing gap, complete the EIN Business Funding Quick Lead Pre-Qualification using the actual transaction numbers.
Start With the Entire Acquisition, Not Just the Asking Price
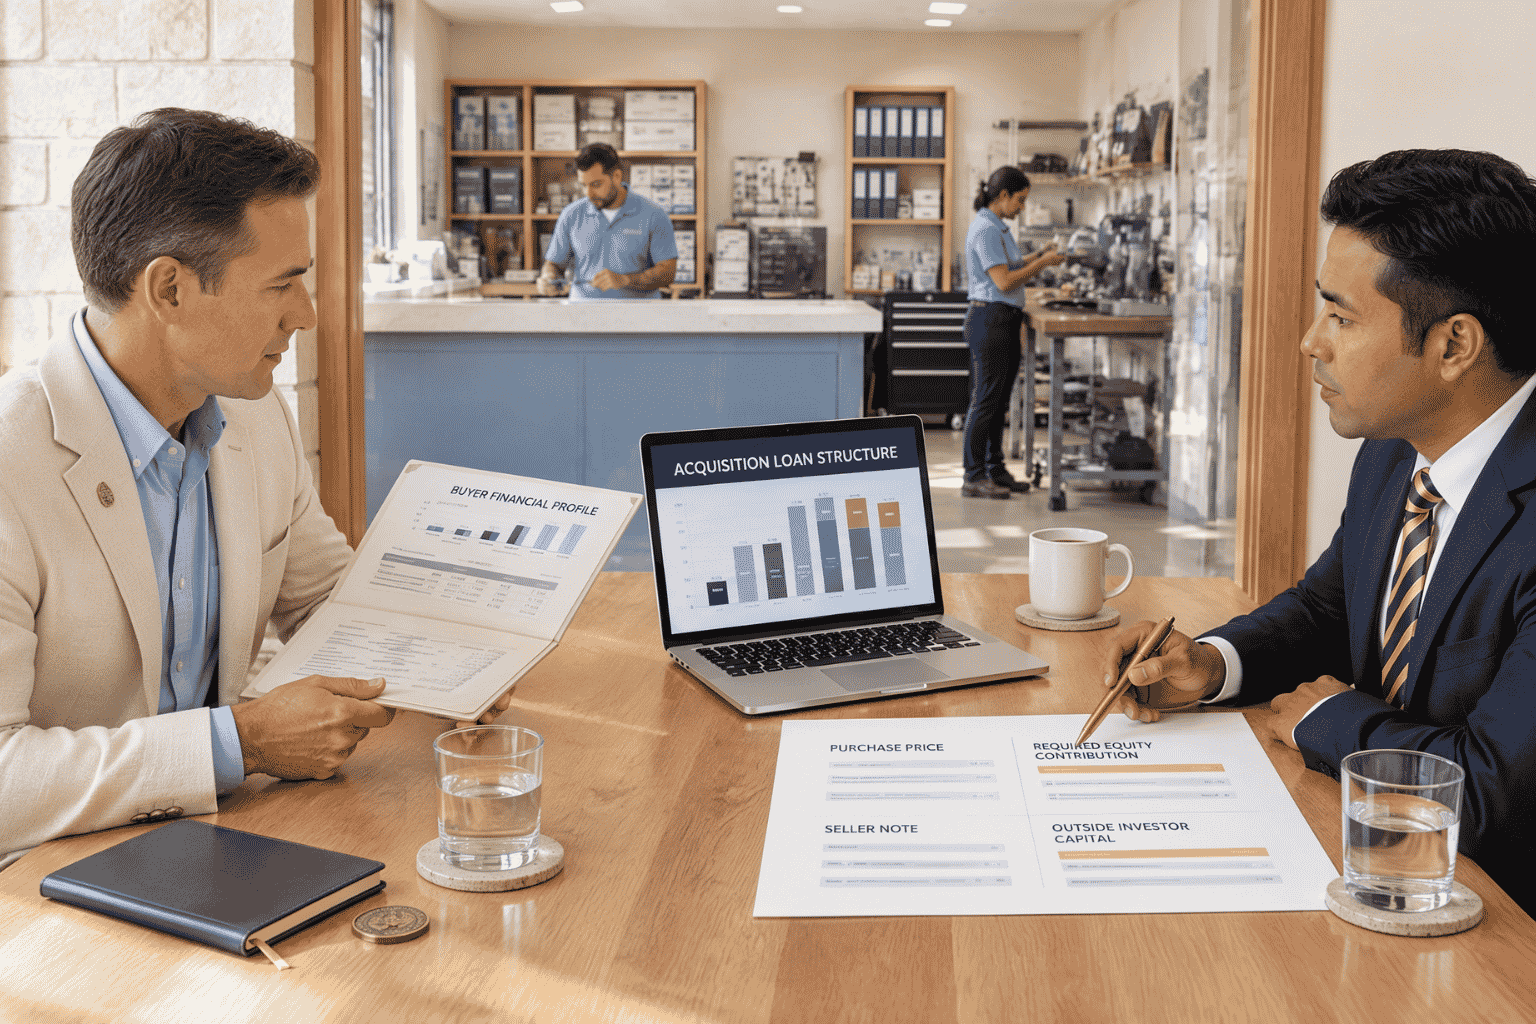
The seller’s asking price is only one component of the capital requirement. Buyers should build a complete sources-and-uses picture before deciding how much cash to contribute.
- Business purchase price
- Buyer cash contribution
- Outside acquisition financing
- Seller financing, if applicable
- Transaction and closing expenses
- Immediate equipment or vehicle needs
- Inventory requirements
- Post-closing operating liquidity
The objective is to understand how much money is required to close the transaction without leaving the new owner financially exposed on day one.
Why Keeping Cash After Closing Matters
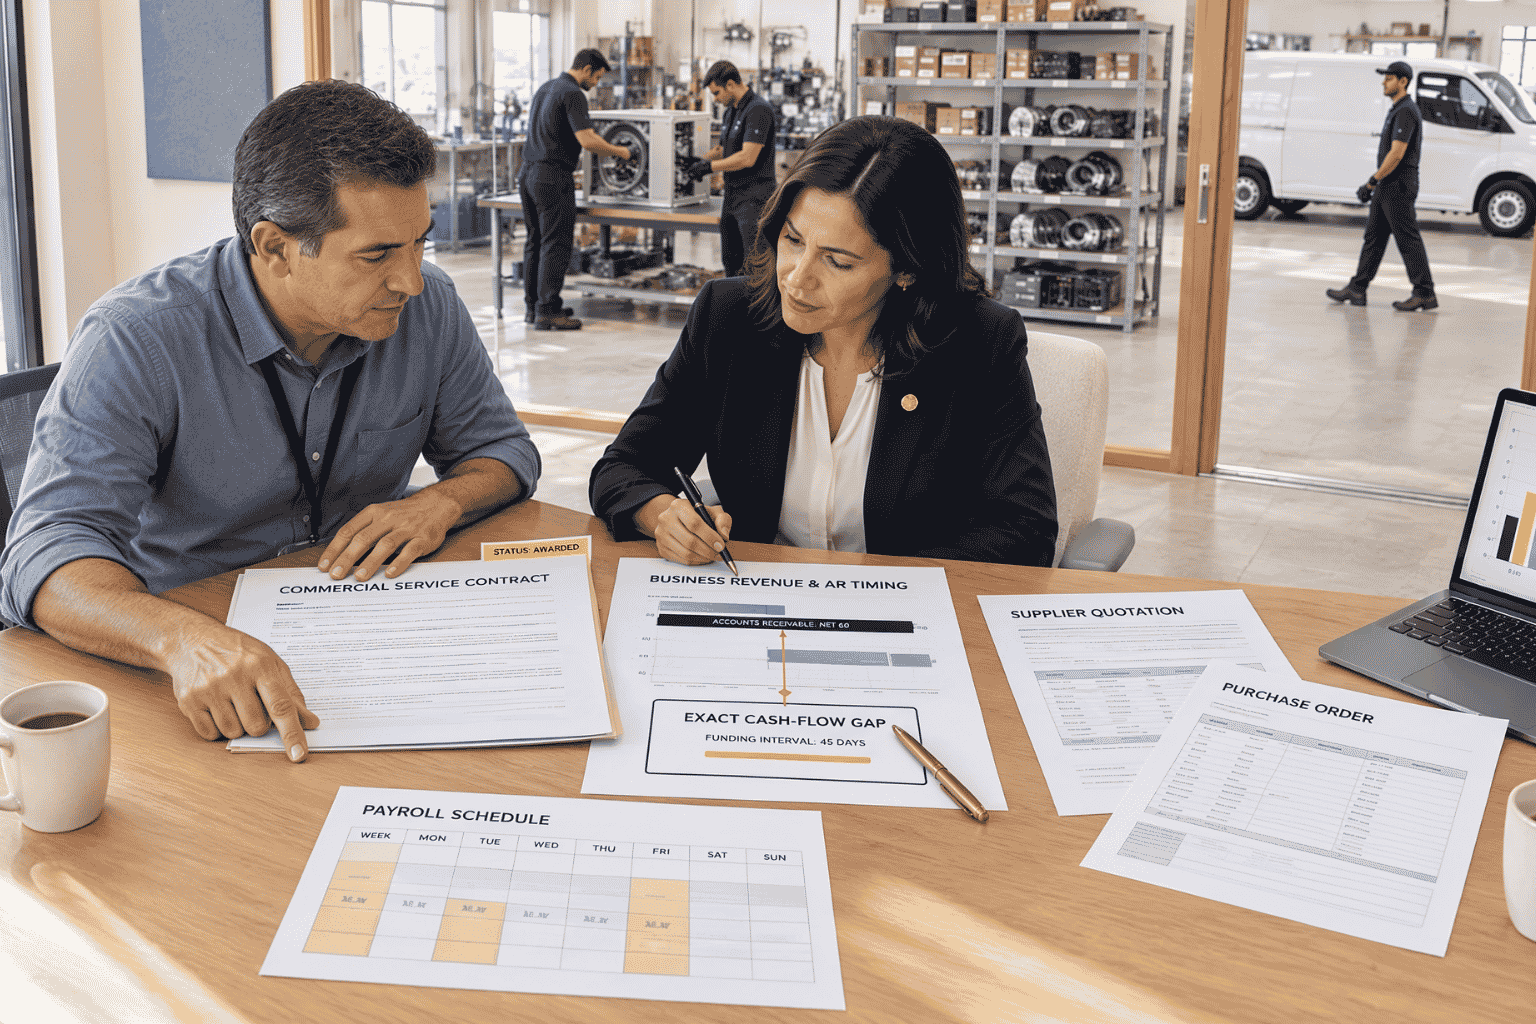
A business can produce strong annual revenue while still experiencing short-term cash fluctuations. Customers may pay in 30 or 60 days while payroll and suppliers must be paid sooner.
That timing difference becomes especially important during an ownership transition. Even a well-run company can experience temporary disruption while customers, employees, vendors and banking relationships adjust to the new owner.
A buyer should therefore evaluate not only whether the purchase can be financed, but whether the business will have enough liquidity after the financing begins.
Do Not Assume Historical Cash Automatically Transfers to the Buyer
The amount of cash remaining inside the business at closing depends on the transaction structure.
A buyer should understand which assets and liabilities are included, how working capital is being treated and what cash will actually be available when ownership changes.
Those details should be addressed clearly with the buyer’s legal, accounting and transaction professionals rather than assumed from historical financial statements.
Calculate the Post-Closing Operating Requirement
Build a practical operating budget for the period immediately following closing.
Consider payroll, rent, utilities, inventory, insurance, supplier obligations, marketing, maintenance, fuel, software subscriptions and any other recurring costs required to keep the business operating normally.
If customers typically pay slowly, include that timing in the calculation.
What if the Business Needs Equipment Immediately?
Equipment can create a second financing need shortly after the acquisition.
A buyer purchasing a transportation business may discover that several vehicles need replacement. A manufacturer may need machinery upgrades. A restaurant may need refrigeration or kitchen equipment.
Where practical, identify these asset needs before closing rather than using the buyer’s remaining liquidity unexpectedly afterward.
Seller Financing Does Not Eliminate the Need for Cash
A seller note can reduce the amount of outside financing needed at closing, but it still creates a future repayment obligation.
The buyer should understand how the seller-financed portion interacts with the acquisition loan and the company’s cash flow.
Seller financing should therefore be included in the complete post-closing debt picture rather than treated as free capital.
Existing Company Debt Can Change the Calculation
Identify business loans, equipment obligations, credit lines and other debt associated with the target company.
Determine which obligations will be satisfied at closing, which remain relevant to the business and how they affect available cash flow.
A company with healthy revenue but substantial debt obligations can have much less financial flexibility than its top-line sales suggest.
How Much Should the Buyer Contribute?
There is no single contribution percentage that applies to every acquisition financing structure.
The appropriate amount depends on the financing product, lender requirements, purchase price, buyer profile, target-company cash flow and transaction structure.
The more useful question is whether the contribution leaves enough liquidity for the business to operate safely after closing.
Do Not Borrow More Simply to Keep Extra Cash
Preserving liquidity does not mean maximizing debt unnecessarily.
Every additional dollar financed creates another repayment obligation. Buyers should balance the value of maintaining operating cash with the cost and repayment burden of the financing.
The transaction should work financially without relying on overly optimistic revenue growth immediately after closing.
What Should a Buyer Prepare Before Funding Review?
- Purchase price
- Buyer contribution available
- Seller-financed amount, if any
- Outside financing required
- Target-company annual revenue
- Current business cash flow
- Existing company debt
- Major near-term equipment needs
- Post-closing operating cash requirement
- Current buyer credit profile
A Financeable Acquisition Must Still Be Operable After Closing
Getting enough money to complete the purchase is only the first test. The acquired company also needs enough liquidity to continue operating while the new owner begins making acquisition-related payments.
That is why acquisition financing should be structured around the complete transaction—not only the seller’s asking price.
If you have an active acquisition and already know the purchase price, contribution and approximate funding gap, use the EIN Business Funding pre-qualification to begin evaluating the financing requirement before committing all available cash to closing.
FAQs
Should a buyer use all available cash as the acquisition contribution?
Not automatically. The buyer should also consider post-closing payroll, inventory, supplier payments, equipment needs and other operating expenses.
Can working capital be part of a business acquisition financing plan?
Potentially, depending on the financing structure and provider. Buyers should calculate the operating-capital requirement separately from the purchase price.
Does seller financing remove the need for acquisition working capital?
No. Seller financing may reduce the cash required at closing, but the business still needs liquidity for operations and the seller note creates another repayment obligation.
 A successful acquisition financing plan should preserve enough liquidity for the business to continue operating after ownership changes.