Won a Large B2B Contract but Need Cash First? Compare Working Capital, PO Financing and Invoice Financing
Winning a large commercial contract should be good news. But for many growing businesses, the first problem appears before the first dollar of customer revenue arrives.
The company may need to purchase materials, pay suppliers, add employees, cover payroll or fulfill a large order weeks before the customer makes payment. That creates a specific funding need: financing the gap between when the business must spend cash and when the customer pays.
Which Financing Product Fits a New B2B Contract?
The answer depends primarily on where the cash gap occurs.
- Working capital may fit when the business needs operating cash for payroll, suppliers, inventory or other short-term expenses.
- Purchase order financing may be worth evaluating when a confirmed customer order requires the business to pay a supplier before the order can be fulfilled.
- Invoice financing may become relevant after the business has delivered the product or service and is waiting for a qualified commercial customer to pay an invoice.
These products address different stages of the same business cycle. Choosing the wrong one can make a legitimate funding request harder to evaluate.
Start With the Customer Payment Timeline
Before seeking financing, map the transaction from beginning to end.
When must the business pay suppliers? When is payroll due? When will the work be completed? When can the customer be invoiced? Are the customer’s terms Net-30, Net-45 or Net-60?
The funding requirement should be based on this timing gap rather than simply on the total value of the contract.
A $500K Contract Does Not Necessarily Mean You Need $500K
The amount of capital required may be much smaller than the contract value.
For example, a company may win a $500,000 contract but need only $120,000 to cover materials and payroll before the first progress payment is received.
That $120,000 cash gap is a more useful starting point for a financing discussion than the headline value of the contract.
When Working Capital May Fit
Working-capital financing can be relevant when the business needs cash to support normal operations while waiting for contract revenue.
The EIN Business Funding guidance identifies approximately 600+ personal credit, six to twelve months in business and roughly $50,000 to $100,000 in annual revenue as common working-capital benchmarks.
Actual requirements vary by provider, and meeting these benchmarks does not guarantee funding.
When Purchase Order Financing May Fit
Purchase order financing is more transaction-specific. It may be worth evaluating when the business has a legitimate purchase order from a commercial customer but lacks sufficient cash to pay the supplier required to fulfill it.
Important factors can include the customer, supplier, order value, gross margin and fulfillment structure.
A future sales opportunity or unsigned proposal is not the same as a documented purchase order.
When Invoice Financing May Fit
Once the company has delivered the goods or completed the service and issued an eligible B2B invoice, the funding question changes.
The company is no longer financing production. It is financing the waiting period between invoicing and customer payment.
Invoice financing can therefore be useful when cash is tied up in qualified commercial receivables while payroll, suppliers and new orders continue.
What if the Business Already Has Debt?
Prepare all open business loans, lines of credit and business credit-card obligations.
Existing debt can affect the amount of additional repayment the company can reasonably support. Providers may review current balances, payments, cash flow and other obligations alongside the new contract.
Do Not Rely Only on Projected Contract Revenue
A signed contract can strengthen the business case, but the company should still present its current financial profile accurately.
Annual revenue, operating history, recent deposits, cash flow, credit and existing debt can all matter.
The financing request should not assume that every expected customer payment will arrive exactly on schedule.
What Should Be Ready Before Funding Review?
- Contract or purchase order value
- Customer payment terms
- Supplier quotation or material costs
- Payroll requirement
- Expected invoice dates
- Exact cash-flow gap
- Annual business revenue
- Recent business deposits
- Current credit profile
- Existing business debt
Use the Contract to Calculate the Funding Need
A strong funding request explains exactly why the company needs capital, how much is required and when customer cash is expected to arrive.
That is considerably more useful than asking generally for the maximum amount available.
If your business has already won a commercial contract and the cash gap is preventing you from fulfilling it, complete the EIN Business Funding Quick Lead Pre-Qualification using the actual contract, revenue and funding requirement.
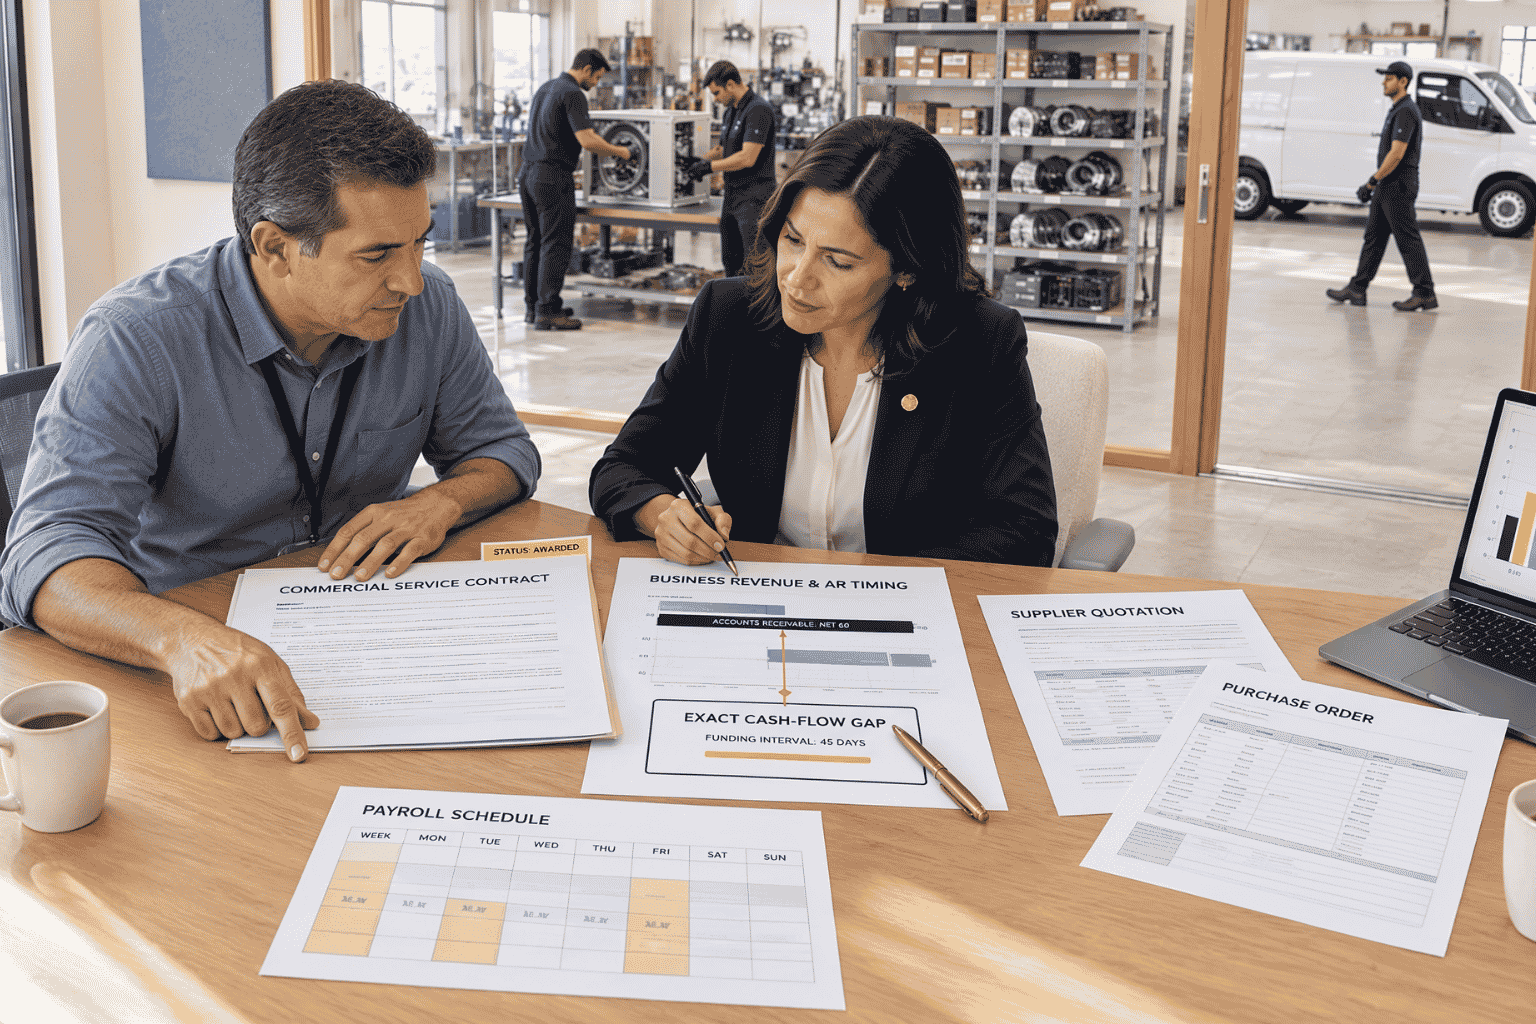 The right contract-financing option depends on whether cash is needed before fulfillment, after invoicing or throughout the operating cycle.