Business Line of Credit for Payroll: Can a Growing Service Company Fund New Hires Before Client Revenue Arrives?
A growing service business can face an unusual problem: the company has enough work to hire more people, but the employees must be paid before the new client revenue arrives.
Consulting firms, agencies, IT services companies, contractors and other labor-intensive businesses can encounter this gap when customer invoices are paid 30, 45 or 60 days after the work is performed.
Why Payroll Growth Creates a Financing Need
Hiring increases cash outflow immediately. Employees generally expect regular payroll regardless of when customers pay the business.
If a company adds ten employees to serve a new account, payroll can increase significantly before the first invoice from that account is collected.
That timing gap can create a recurring working-capital requirement.
When Can a Business Line of Credit Fit?
A line of credit may be worth evaluating when the funding need repeats rather than occurring only once.
The business can potentially draw capital during the payroll gap, repay it as customer cash arrives and use the line again according to the financing terms.
That can make revolving credit conceptually different from a fixed-term loan used for one major project.
What Does a Traditional Line-of-Credit Profile Look Like?
The EIN Business Funding guidance identifies common traditional business line-of-credit benchmarks of approximately:
- 720+ personal credit
- One to two years in business
- $100,000 to $250,000+ annual revenue
- Positive cash flow
- Established business checking account
Traditional lenders may also review business and personal tax returns, profit and loss statements and business bank statements.
What if the Business Does Not Meet Traditional Bank Benchmarks?
Alternative working-capital or online financing may use different profiles.
The EIN Business Funding guidance identifies approximately 600 to 680+ personal credit, six to twelve months in business and roughly $50,000 to $250,000+ annual revenue as common online or alternative financing ranges.
Consistent deposits and business bank statements can also matter.
Calculate the Payroll Gap—Not the Annual Payroll
A business usually does not need to finance an entire year of payroll.
The more useful number is the maximum amount of payroll and related operating expense that must be covered before customer payments arrive.
For example, a company may have $80,000 in monthly payroll but need only $120,000 of revolving capacity to manage the timing gap created by Net-60 customers.
Client Payment Terms Matter
A service business paid immediately needs less working capital than one whose customers routinely pay in 45 or 60 days.
Review actual customer-payment behavior, not only the payment terms written in the contract.
If customers regularly pay late, the funding requirement may be larger than expected.
Why Revenue Alone Is Not Enough
A service company can have substantial annual revenue and still experience payroll pressure if receivables grow faster than available cash.
The provider may evaluate cash flow, deposits and existing obligations in addition to headline sales.
Existing Debt Can Reduce Revolving Capacity
Prepare current business loans, credit cards and existing lines of credit.
A company already carrying substantial monthly obligations may have less capacity to support another financing facility.
What if the Business Has a Signed New Client Contract?
A legitimate contract can explain why the company is hiring, but projected client revenue should not be treated as guaranteed cash.
The provider may still evaluate current business performance and whether the company could support repayment if the client pays more slowly than expected.
Should Invoice Financing Be Considered Instead?
Potentially, particularly after the business has completed work and issued eligible B2B invoices.
Invoice financing and a line of credit solve related but different problems. One is tied more directly to receivables; the other can provide broader revolving access to capital.
What Should a Growing Service Company Prepare?
- Current annual revenue
- Recent monthly deposits
- Existing payroll
- Projected payroll after hiring
- Number of employees being added
- Customer payment terms
- Current credit profile
- Time in business
- Existing debt
- Requested line amount
Do Not Hire Based Only on Financing Availability
A credit line can help bridge timing, but it should not be used to support permanently unprofitable hiring.
The new employees should be tied to real operating demand, existing clients or a credible growth plan that produces enough gross profit to support both payroll and financing costs.
Use Revolving Capital for a Revolving Problem
If the payroll gap appears every month because customers pay after employees must be paid, a revolving financing structure may deserve consideration.
If the company has a single one-time hiring expense, another structure may fit more naturally.
If your service company has real client revenue but payroll is growing faster than customer cash arrives, complete the EIN Business Funding Quick Lead Pre-Qualification using current revenue, credit, business age, debt and the actual payroll gap.
FAQs
Can a business line of credit be used for payroll?
Potentially, depending on the provider and permitted use of funds. A revolving line may be relevant when payroll timing creates a recurring cash-flow gap.
What are common traditional line-of-credit benchmarks?
The EIN Business Funding guidance identifies approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ annual revenue and positive cash flow as common benchmarks.
Should a business borrow enough to cover a full year of payroll?
Not automatically. The business should calculate the actual timing gap between payroll obligations and customer collections rather than financing more than necessary.
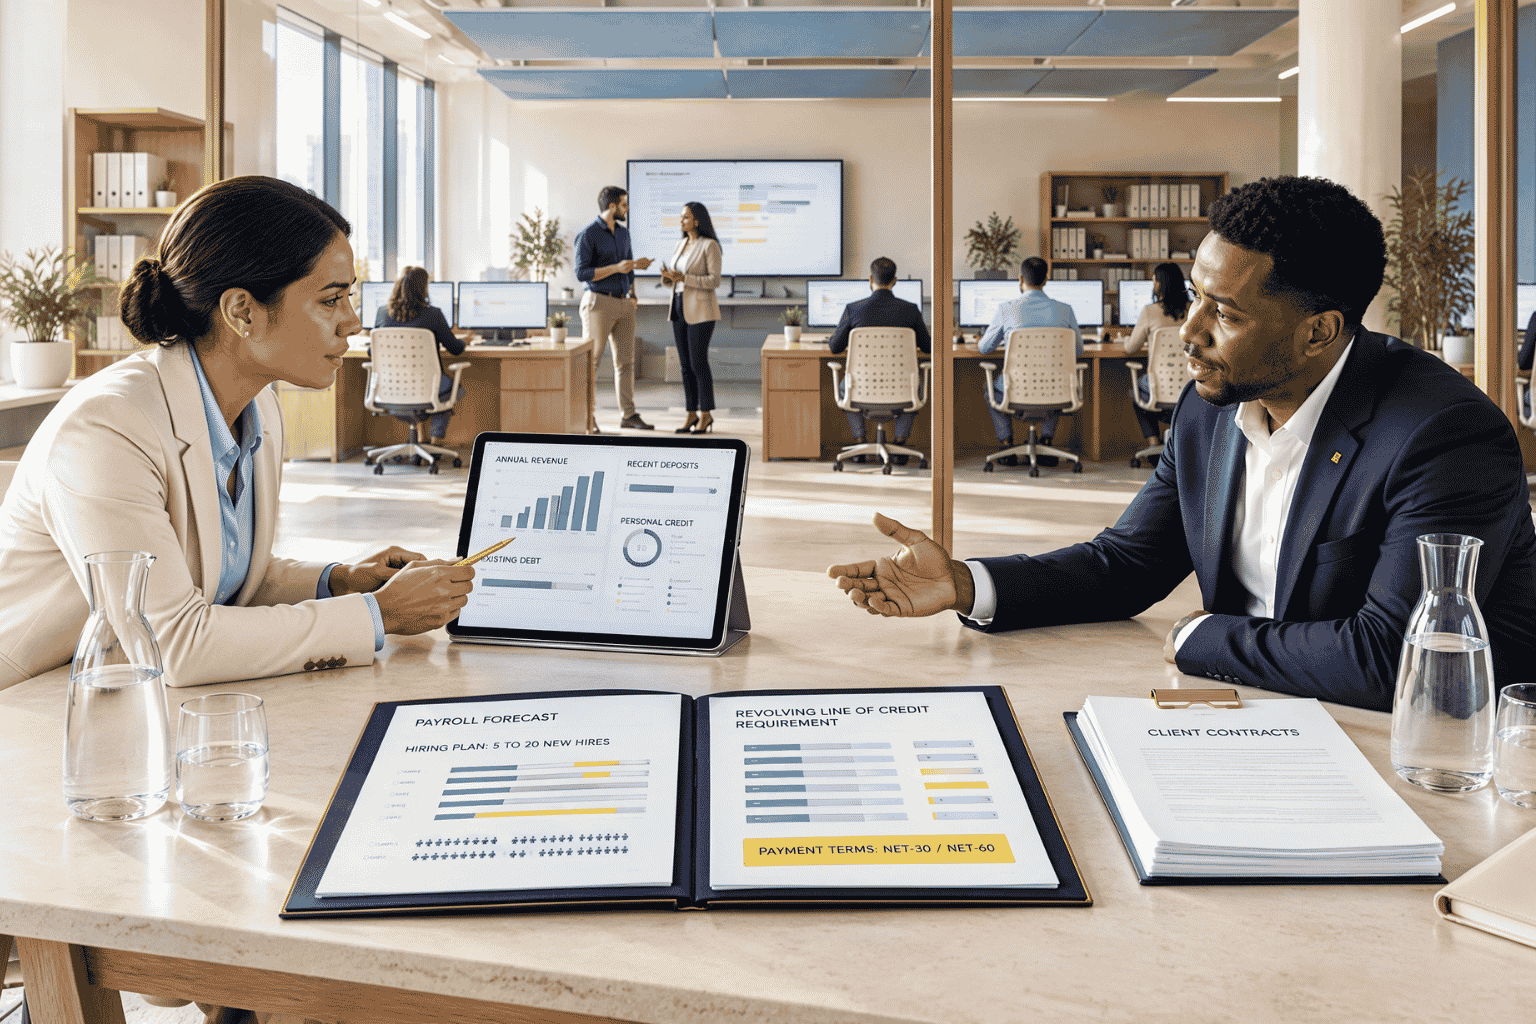 Growing service businesses can face recurring payroll gaps when employees must be paid before B2B customers pay invoices.