Business Funding With 680 Credit: Which Financing Options May Be Worth Checking?
If your personal credit score is around 680 and your business needs capital, you may be close to qualification ranges used by several different financing categories. But credit score alone does not determine which option fits.
For a faster initial screen, complete the EIN Business Funding Quick Lead Pre-Qualification with your credit range, time in business, annual revenue and requested funding amount.
What Business Funding Options Commonly Consider 680 Credit?
Online or alternative small-business loans commonly use personal-credit ranges around 600 to 680+, with approximately six to twelve months in business and around $50,000 to $250,000+ in annual revenue depending on the provider.
Term loans also commonly use credit ranges around 600 to 680+, together with one or more years in business, approximately $100,000+ in annual revenue and positive cash flow.
What About Working Capital?
Working-capital financing may commonly consider approximately 600+ personal credit, six to twelve months in business and around $50,000 to $100,000 in annual revenue.
Consistent business activity and cash flow remain important even when the stated credit threshold is lower than traditional bank financing.
Could 680 Credit Be Relevant to SBA Financing?
The funding guidance identifies approximately 680 to 700+ personal credit as a common range for SBA financing, although individual lender and program requirements vary.
SBA lenders may also examine repayment ability, owner investment, business history, business plan and collateral for some loans.
What Usually Requires Stronger Credit?
Traditional business lines of credit commonly look for approximately 720+ personal credit, one to two years in business, approximately $100,000 to $250,000+ in annual revenue and positive cash flow.
Business credit cards may commonly favor personal credit around 740+.
What Should You Prepare Besides Your Credit Score?
Have your annual business revenue, time in business, banking information, existing business debt and exact use of funds ready. Those details can materially change which financing category is worth exploring.
If your credit is around 680 and you have an active business funding need, complete the EIN Business Funding pre-qualification to compare potential funding paths using your actual profile.
Questions Business Owners Ask
Can I get business funding with a 680 credit score?
Potentially. Several financing categories commonly use ranges that include approximately 680, but revenue, operating history, cash flow and debt also matter.
Is 680 enough for an SBA loan?
The funding guidance identifies approximately 680 to 700+ as a common SBA credit range, but lender and program requirements vary.
Will 680 usually qualify for a traditional business line of credit?
Traditional lines of credit commonly use stronger benchmarks around 720+ personal credit along with established revenue and business history.
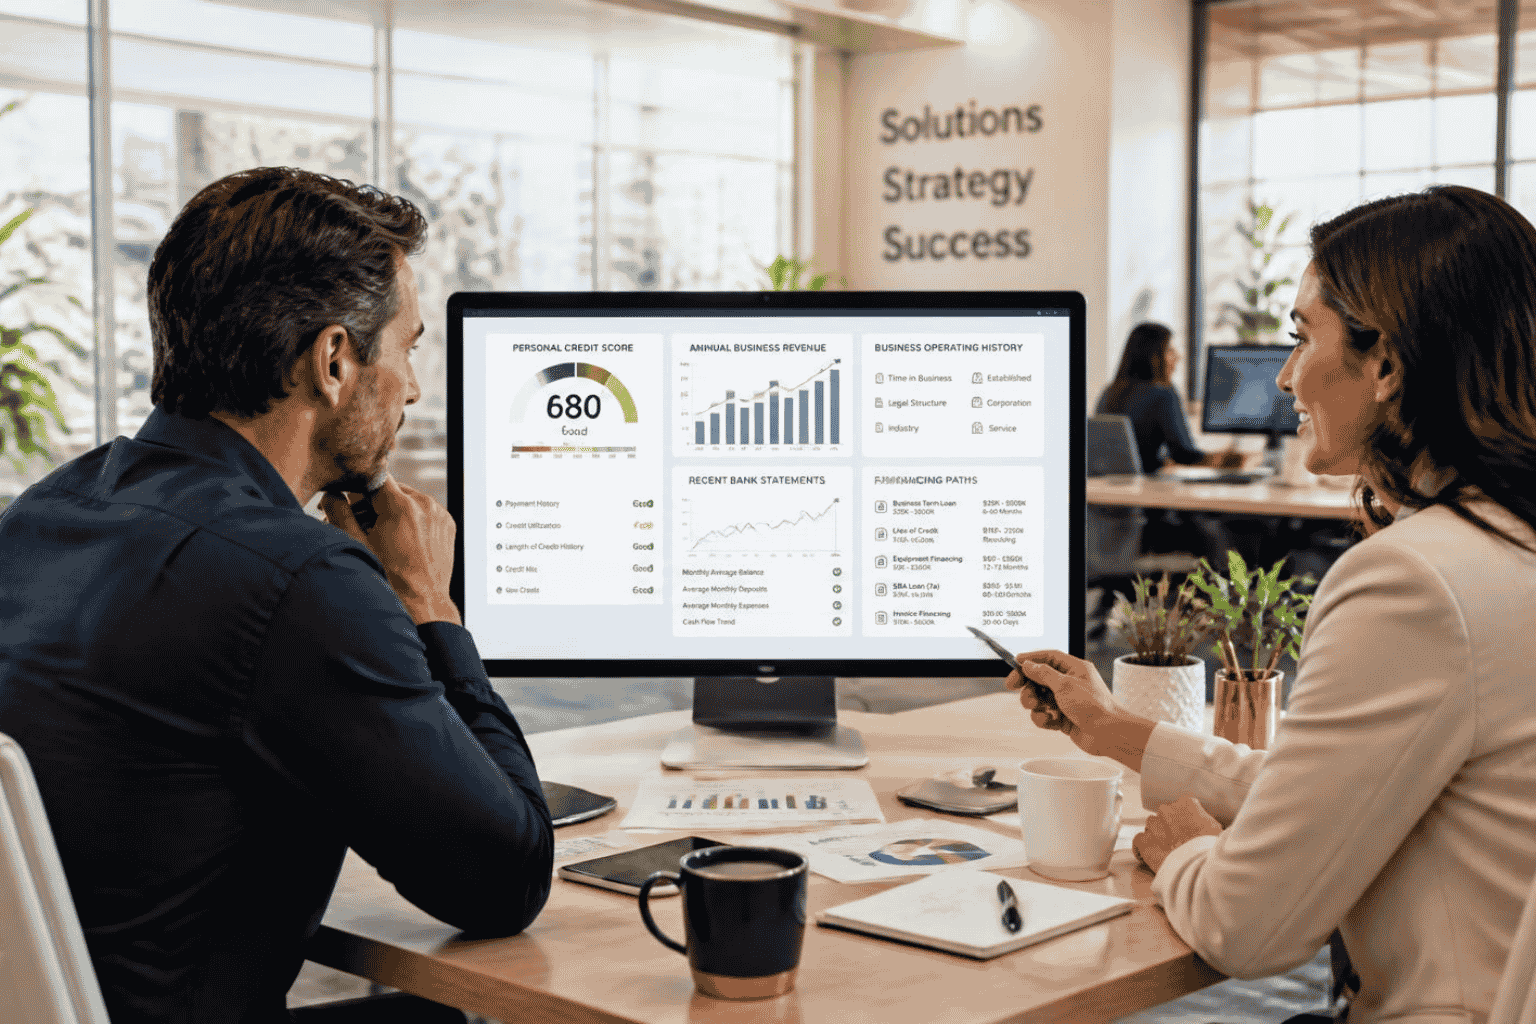 A credit score around 680 may fall within several business-financing ranges, but revenue, cash flow and operating history also matter.