Business Expansion Loan: Term Loan or Line of Credit? Compare the Qualification Profiles
When a business needs capital for expansion, the first question should not always be, “Which lender will give me the most money?” A better starting point is understanding whether the funding need is better suited to a fixed term loan or revolving line of credit.
If you already know your expansion budget, complete the EIN Business Funding Quick Lead Pre-Qualification with your requested amount, annual revenue, credit profile and time in business.
When May a Business Term Loan Fit Expansion?
A term loan can be worth evaluating when the business has a defined one-time capital requirement and wants to repay the financing over an agreed term.
Typical term-loan benchmarks include approximately 600 to 680+ personal credit, one or more years in business, around $100,000+ in annual revenue and positive cash flow.
When May a Business Line of Credit Fit?
A line of credit may be more relevant when a company wants revolving access to capital rather than funding one single expense.
Traditional business lines of credit commonly have stricter benchmarks, including approximately 720+ personal credit, one to two years in business, around $100,000 to $250,000+ annual revenue and positive cash flow.
What Documentation May a Traditional Line of Credit Require?
Funding providers may request business tax returns, personal tax returns, profit and loss statements and business bank statements.
They may also evaluate debt-service coverage, existing business debt, industry risk and cash-flow consistency.
What If Your Business Does Not Fit Traditional Bank Requirements?
Other financing categories may use different standards. Online business loans and working-capital products can sometimes consider shorter operating histories or lower personal-credit ranges.
How Should You Define the Expansion Need?
Be specific about whether the capital is for a new location, inventory, equipment, marketing, payroll, additional staff or another expansion expense.
If the project contains multiple types of expenses, separating them can help determine whether one financing product or a combination of funding structures is more appropriate.
What Should You Have Ready?
Prepare your current Experian FICO score, annual revenue, time in business, banking information, existing debt, requested amount and exact use of funds.
If your company is actively expanding, complete the EIN Business Funding pre-qualification to evaluate potential financing paths.
Questions Business Owners Ask
Is a term loan or line of credit better for business expansion?
It depends on whether the business needs a defined amount for a specific project or recurring access to capital and whether its qualification profile fits the product.
What are common term-loan benchmarks?
Approximately 600 to 680+ personal credit, one or more years in business, $100,000+ annual revenue and positive cash flow are common benchmarks.
What are common traditional line-of-credit benchmarks?
Approximately 720+ personal credit, one to two years in business and $100,000 to $250,000+ annual revenue are commonly associated with traditional business lines of credit.
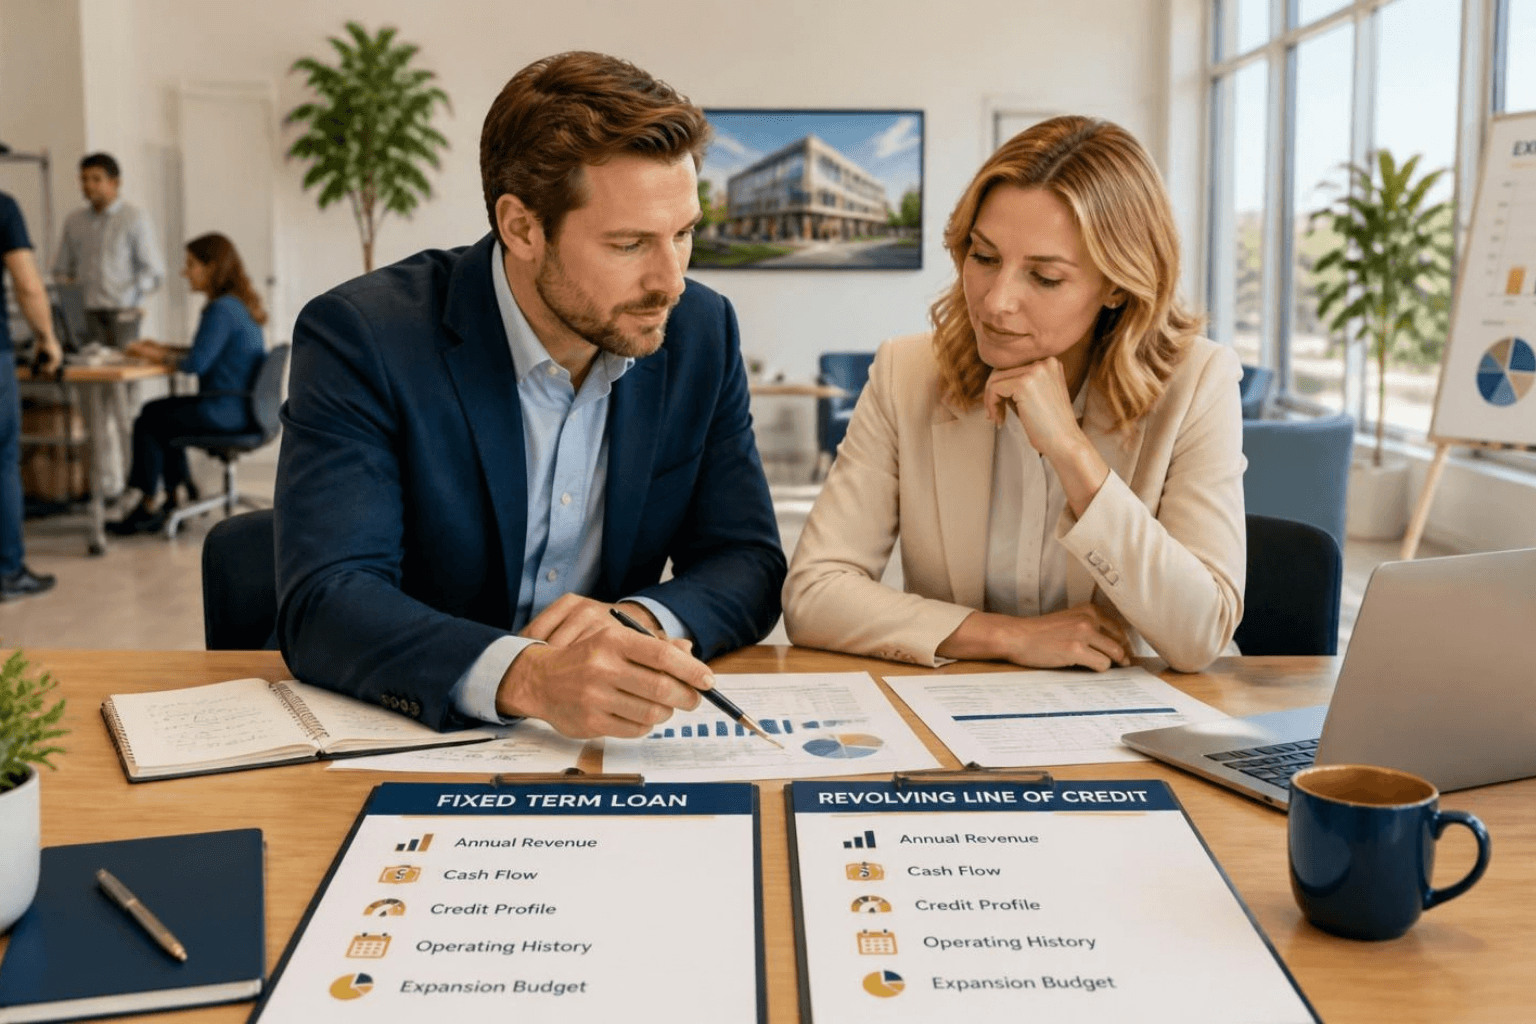 Term loans and traditional business lines of credit can use very different qualification profiles.