Business Loans Using EIN: What Changes After 2 Years in Business and $250K+ Revenue?
Business owners frequently search for business loans using an EIN, but the EIN is only one part of a lender-ready business profile. The financing discussion can look very different once a company has meaningful operating history, revenue and consistent cash flow.
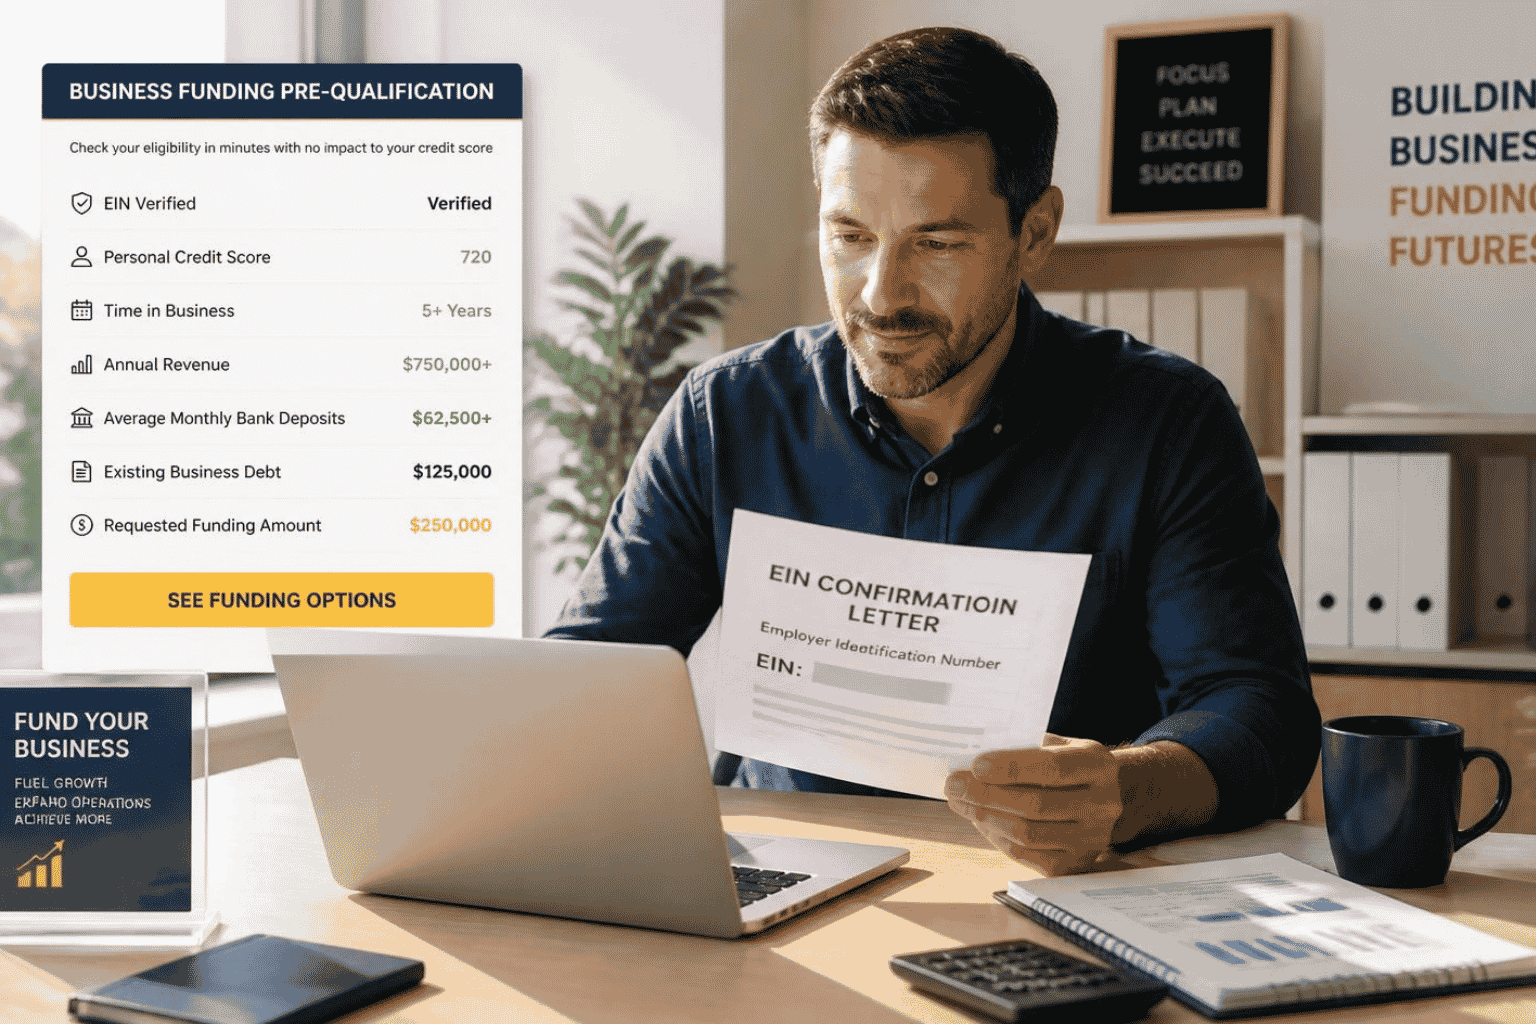
If your business is established and currently needs capital, complete the EIN Business Funding Quick Lead Pre-Qualification with your actual revenue, time in business, credit profile and requested amount.
Does Having an EIN Help You Qualify for a Business Loan?
An EIN identifies the business and may be required or relevant during the application process, but lenders commonly evaluate additional information such as personal credit, business credit if established, time in business, revenue, cash flow and debt obligations.
Why Do 2+ Years in Business Matter?
A longer operating history can give funding providers more information about the company’s revenue consistency, banking activity, financial performance and repayment ability.
What Does $250K+ Annual Revenue Change?
The EIN Business Funding guidance describes a generally competitive borrower profile as approximately 700+ personal credit, two or more years in business, $250,000+ in annual revenue and positive, consistent cash flow.
That does not guarantee approval, but it can make a business more competitive across multiple financing categories.
What Other Factors Strengthen the Profile?
- Organized financial statements and tax returns
- Established business bank account
- Legal business entity
- No recent bankruptcies, tax liens or major delinquencies
- Manageable existing business debt
- Clear use of funds
What Financing Categories May Be Worth Exploring?
Depending on the borrower and use of funds, an established company may evaluate term loans, traditional business lines of credit, SBA-related financing, equipment financing or other business funding options.
What Should You Have Ready?
Prepare your EIN, formation date, ownership percentage, annual revenue, business banking information, current Experian FICO score, existing debt, funding amount and use of funds.
If your company has crossed the two-year and $250,000-revenue stage and needs capital now, complete the EIN Business Funding pre-qualification rather than assuming the EIN alone determines what is available.
FAQs
Can I get a business loan using my EIN?
An EIN may be part of the application, but lenders commonly evaluate credit, revenue, business history, cash flow, existing debt and other underwriting factors.
Is $250,000 in annual revenue a strong business funding benchmark?
The EIN Business Funding guidance identifies $250,000+ annual revenue, two or more years in business, 700+ personal credit and positive consistent cash flow as part of a generally competitive borrower profile.
Does meeting those benchmarks guarantee business funding?
No. Final eligibility depends on the financing product, provider and complete borrower profile.
 An EIN matters, but stronger revenue, operating history, cash flow and credit can broaden the financing paths worth evaluating.