SBA 7(a) Loan Eligibility: Why Owner Equity and “Credit Elsewhere” Can Matter
SBA 7(a) financing is government-backed, but it is still underwritten by participating lenders. Business owners should understand that eligibility involves more than simply having an established company or good credit.
If you are actively considering SBA financing, complete the EIN Business Funding Quick Lead Pre-Qualification with your funding need, business history, annual revenue and current credit profile.
What Are Typical SBA 7(a) Considerations?
The EIN Business Funding guidance identifies several common factors:
- For-profit U.S. business
- Applicable SBA size requirements
- Reasonable owner equity investment
- Demonstrated ability to repay
- Good personal credit, often around 680 to 700+
Why Does Owner Equity Matter?
A lender may expect the owner to have a meaningful financial commitment to the transaction or business purpose being financed. The appropriate contribution depends on the transaction and lender requirements.
What Does “Credit Elsewhere” Mean in the Funding Guidance?
The guidance notes that SBA 7(a) applicants generally should not be able to obtain similar financing on reasonable terms elsewhere.
That requirement is one reason SBA financing should not automatically be treated as interchangeable with every conventional business loan.
Can Collateral or a Personal Guarantee Be Required?
The funding guidance notes that collateral may be required for larger loans and that owners with 20% or more ownership generally provide a personal guarantee.
What Should You Prepare?
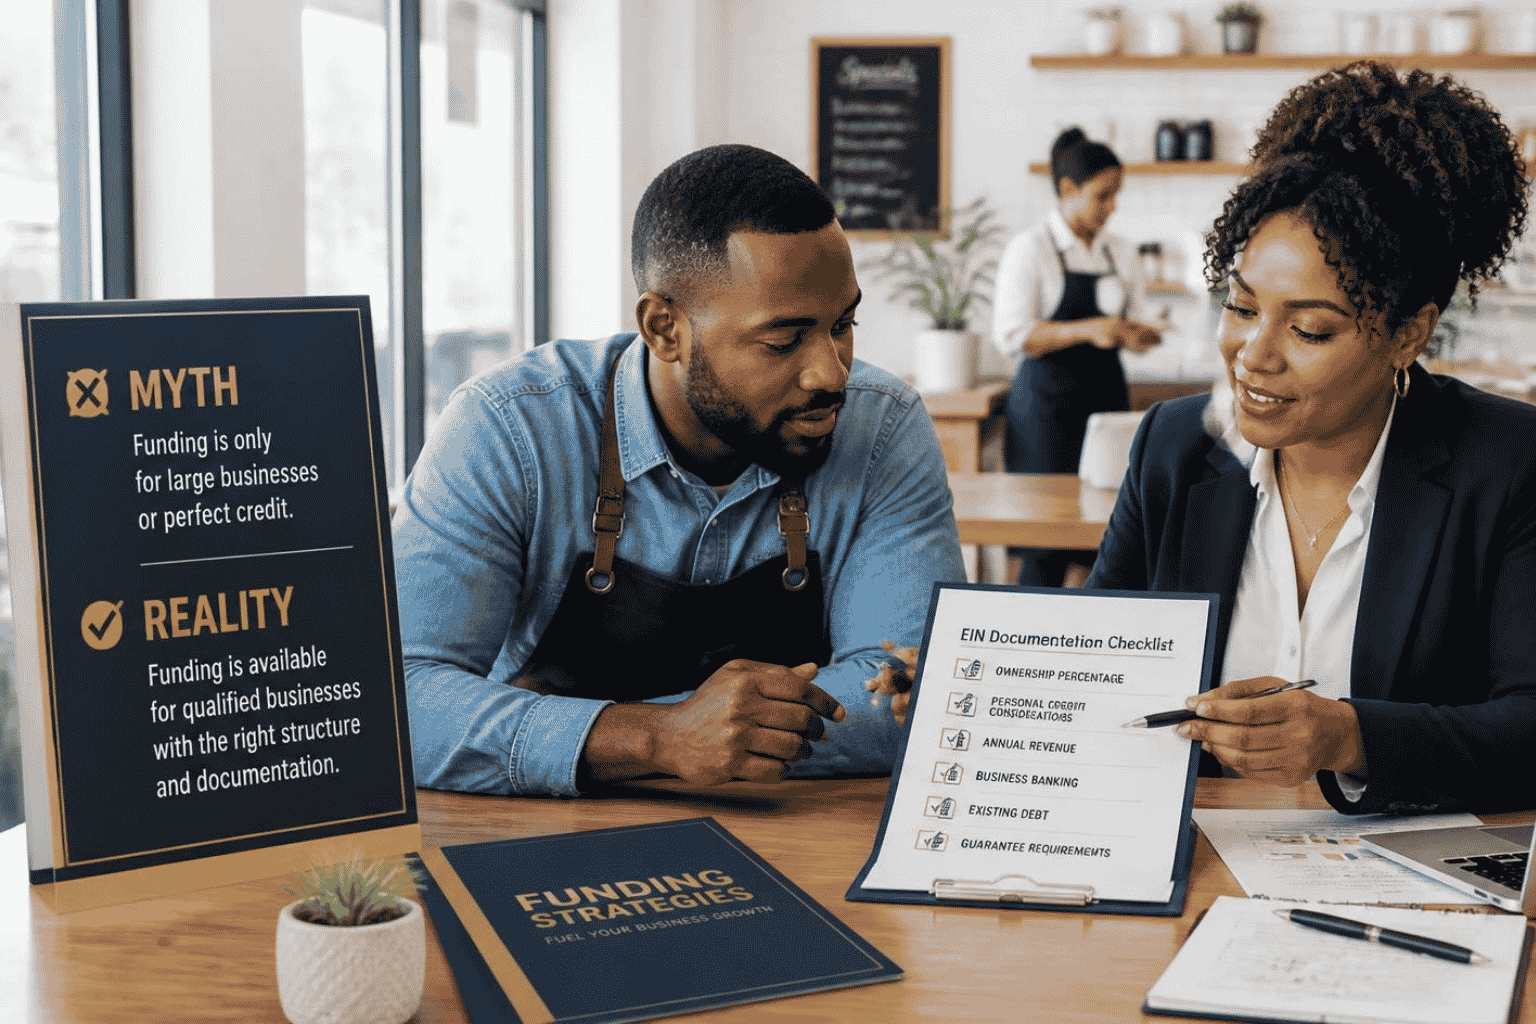
Have your entity information, ownership percentages, annual revenue, financial records, existing debt, current credit profile, requested amount and use of funds ready before beginning a serious lending discussion.
If SBA financing appears relevant to your business need, complete the EIN Business Funding pre-qualification for an initial funding review.
FAQs
What personal credit is commonly associated with SBA 7(a) financing?
The EIN Business Funding guidance identifies approximately 680 to 700+ as a common range, although lender requirements vary.
Does an SBA 7(a) borrower usually need owner equity?
Reasonable owner equity investment is identified as a typical SBA 7(a) consideration.
Can SBA financing be available when similar financing is reasonably available elsewhere?
The funding guidance states that applicants generally cannot obtain similar financing on reasonable terms elsewhere, subject to applicable program and lender requirements.
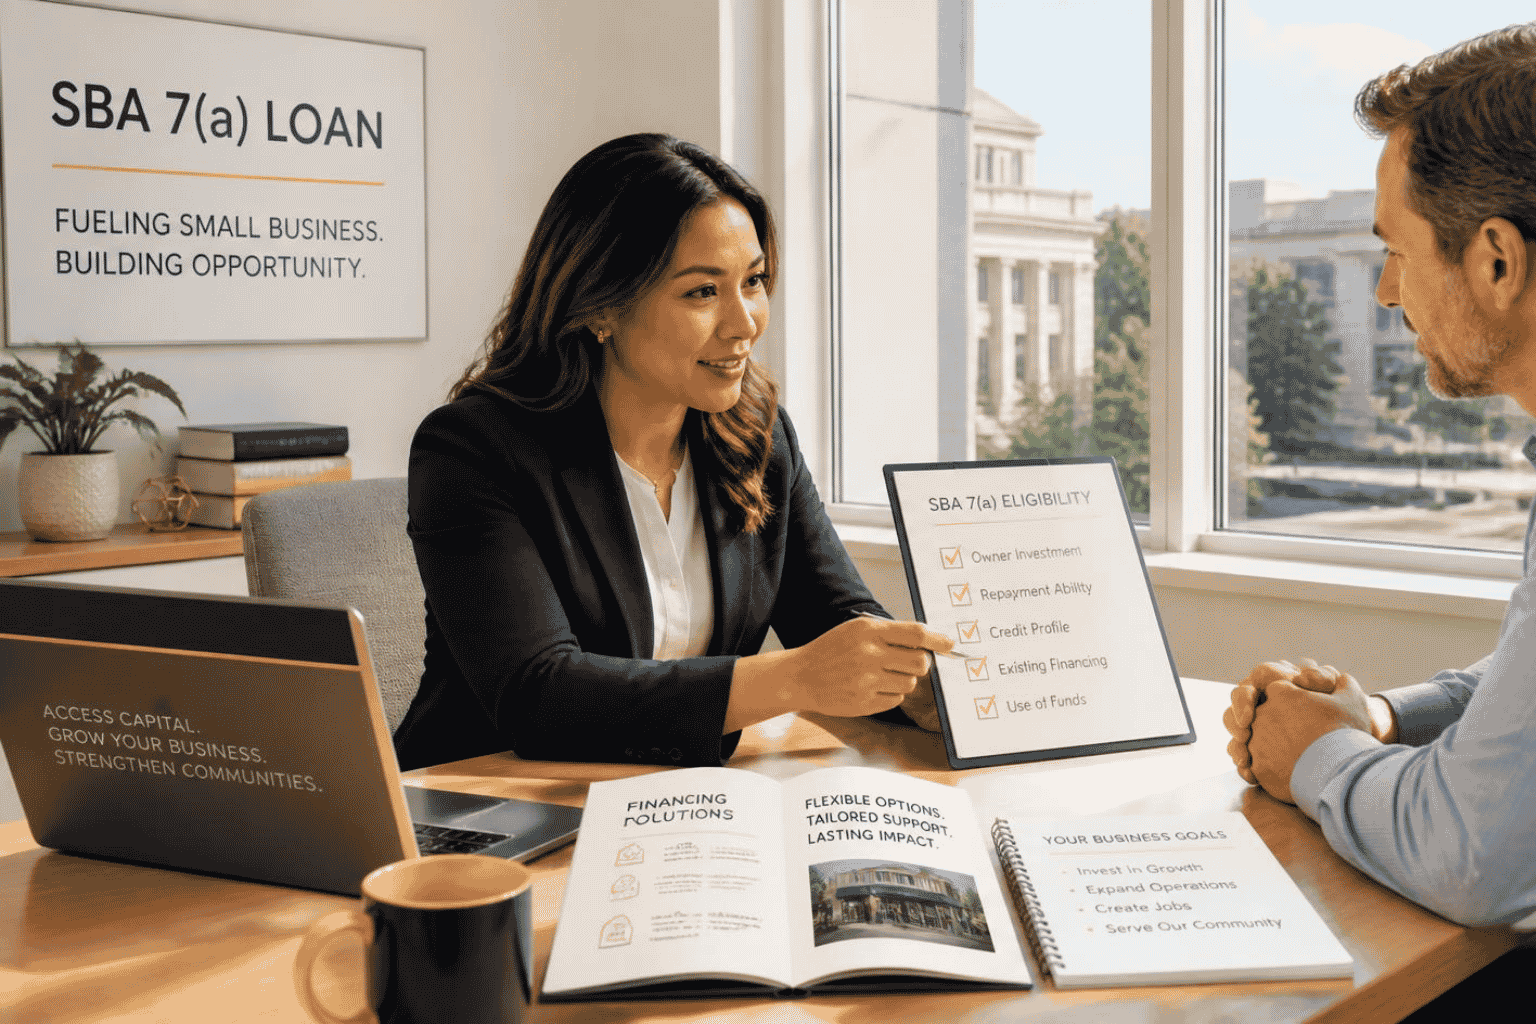 SBA 7(a) eligibility can involve owner equity, repayment ability, credit and availability of comparable financing.