Business Loan With Bad Credit and an EIN: Which Funding Profiles May Still Be Reviewed?
Business owners often search for a business loan with bad credit and an EIN because they want to know whether the business itself can carry more of the qualification burden. An EIN is important business information, but it does not automatically replace credit, revenue, cash-flow or repayment review.
If your business needs capital now and your credit is less than ideal, complete the EIN Business Funding Quick Lead Pre-Qualification with your actual credit score, time in business, revenue and funding need.
Does Bad Credit Automatically Mean No Business Funding?
No. Different financing categories use different borrower profiles. However, lower credit can reduce the number of products worth evaluating and may affect pricing or other terms.
What If Your Credit Is Around 600?
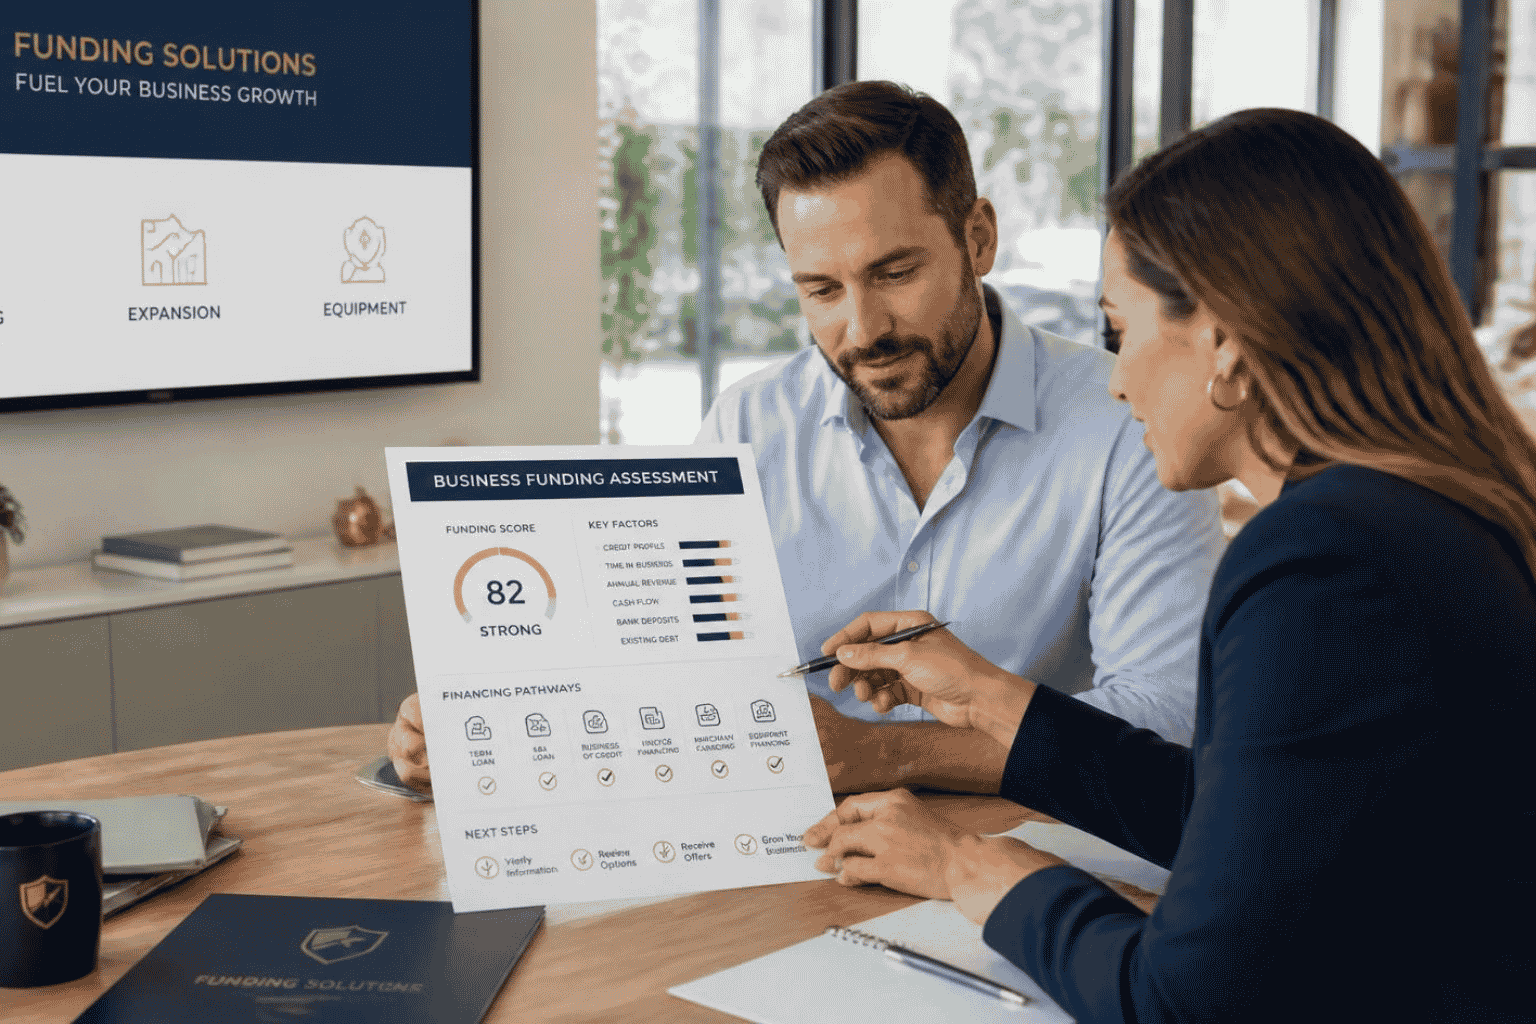
The EIN Business Funding guidance identifies approximately 600+ personal credit as a common benchmark for working-capital financing, together with six to twelve months in business and approximately $50,000 to $100,000 in annual revenue.
What About Online or Alternative Business Loans?
Online or alternative small-business financing commonly uses credit ranges around 600 to 680+, six to twelve months in business and approximately $50,000 to $250,000+ in annual revenue.
Consistent deposits and business bank statements may also matter.
What If Credit Is Closer to 500–600?
Merchant cash advances may consider borrowers in approximately the 500 to 600+ credit range when the business has regular card sales and consistent monthly revenue.
They are generally among the more expensive financing categories, so business owners should review the total cost and repayment structure carefully.
What Does the EIN Actually Do?
The EIN identifies the business for tax and application purposes. Funding providers may still evaluate personal credit, business credit if established, operating history, revenue, cash flow, debt and other underwriting factors.
What Should You Have Ready?
Prepare your EIN, formation date, annual revenue, business bank information, current Experian FICO score, existing debt, requested funding amount and specific use of funds.
If your business is generating revenue and you have an immediate capital need, complete the EIN Business Funding pre-qualification so the request can be reviewed against your actual profile.
FAQs
Can I get a business loan with bad credit and an EIN?
Potentially. An EIN alone does not determine approval, but some financing categories may consider lower-credit borrowers when revenue, deposits and operating history support the request.
What business funding options may consider credit around 600?
Working-capital and some online or alternative financing may use approximately 600+ credit benchmarks depending on the provider and complete borrower profile.
Does an EIN eliminate the need for personal credit?
No. Funding providers may still evaluate personal credit together with business revenue, cash flow, debt and operating history.
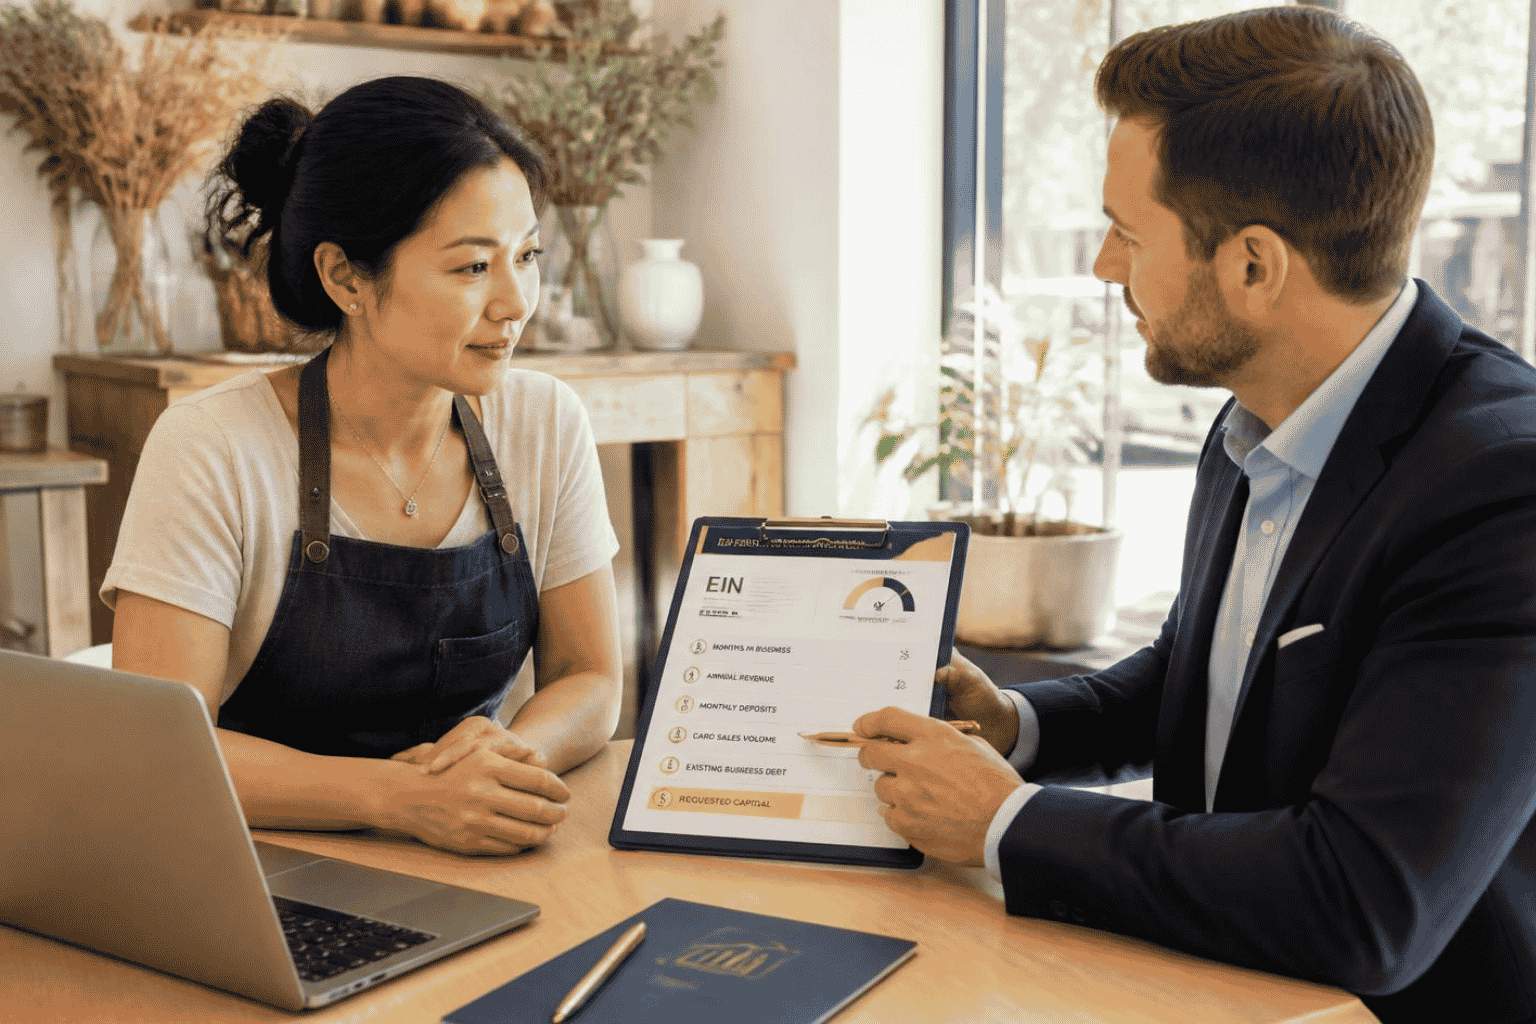 Lower credit can narrow the funding options, but revenue, deposits and operating history can still matter in the review.