Business Acquisition Financing Lenders: 8 Numbers to Have Ready Before You Ask for Terms
Searching for business acquisition financing lenders is usually not the first step in financing a purchase. The first step is understanding the transaction well enough to give a lender something meaningful to evaluate.
A buyer who says, “I found a business for $1 million and need a loan,” has provided only one number. Acquisition financing usually depends on several numbers working together.
If you already have an active acquisition target, complete the EIN Business Funding Quick Lead Pre-Qualification using the real transaction details rather than a general estimate.
1. What Is the Actual Purchase Price?
Start with the agreed price or the current negotiated price.
If the seller is asking $1.2 million but the buyer expects to offer $950,000, those are materially different transactions.
Financing should be evaluated against the deal that is realistically expected to close.
2. How Much Cash Can the Buyer Contribute?
The buyer should know how much liquid capital is actually available for the transaction.
Do not count money that is needed for family expenses, unrelated obligations or the buyer’s entire emergency reserve without considering the consequences.
The contribution should be evaluated together with the cash the buyer needs to retain after closing.
3. Is the Seller Financing Any Part of the Purchase?
A seller note can change the acquisition capital structure significantly.
For example, a transaction might include buyer cash, outside acquisition financing and a seller-financed portion.
However, the terms of the seller note matter. A lender may need to understand payment timing, standby provisions where relevant and how the seller obligation interacts with senior financing.
4. What Is the Target Company’s Annual Revenue?
Revenue helps show the scale of the business being acquired.
A $2 million purchase of a company producing substantial recurring revenue presents differently from a similarly priced company with much lower sales and aggressive growth projections.
Revenue should be supported by available financial records rather than based solely on the seller’s marketing summary.
5. What Is the Sustainable Cash Flow?
This is one of the most important numbers.
The acquired business ultimately needs to pay employees, suppliers and operating expenses while also supporting the proposed acquisition debt.
Buyers should examine normalized earnings carefully, especially when seller add-backs are being used to justify valuation.
6. How Much Existing Debt Does the Company Have?
Identify business loans, equipment financing, credit lines, credit-card balances and other material obligations.
Determine which debt will be paid at closing and which obligations affect the business afterward.
Existing debt can change both the purchase structure and the amount of cash flow available for acquisition financing.
7. How Much Working Capital Is Needed After Closing?
Do not assume the purchase price is the complete funding need.
The business may need immediate liquidity for payroll, inventory, accounts payable, repairs, marketing or seasonal expenses.
A buyer who commits nearly every available dollar to closing can become financially constrained even after acquiring a profitable company.
8. What Is the Buyer’s Current Credit Profile?
The buyer’s credit can affect the financing categories and structures worth considering.
Know the current profile before speaking with lenders instead of discovering an unexpected issue after the transaction has advanced.
Credit is not the only factor in acquisition financing, but it can be an important one.
Why These Numbers Should Be Reviewed Together
No single number answers the financing question.
A business may have strong cash flow but an aggressive purchase price. A buyer may have excellent credit but insufficient contribution. A seller may offer financing, but the company may already carry substantial debt.
The transaction becomes clearer only when the numbers are considered together.
What About 100% Business Acquisition Financing?
Searches for 100% acquisition financing are common, but buyers should avoid building a transaction around the assumption that no equity or outside capital will ever be required.
Different lenders and programs have different structures, and the complete deal must still meet underwriting requirements.
A better starting point is to determine what capital the buyer can realistically bring and what financing gap actually remains.
Do Not Ask Every Lender for the Same Deal Without Pre-Screening
Different acquisition financing providers may serve different transaction sizes, borrower profiles and deal structures.
Submitting an incomplete deal broadly can consume time without improving the probability of closing.
Organizing the transaction first makes lender conversations more focused.
What Documents May Eventually Be Needed?
Document requirements vary, but buyers should expect serious acquisition underwriting to involve financial records related to the target business and information about the buyer.
The initial funding discussion does not require posting sensitive personal information publicly. Sensitive information should be provided only through the appropriate secure process when required.
A Good Lender Conversation Starts With a Financeable Deal
Before asking, “Which acquisition lender will approve this?” ask whether the purchase price, contribution, cash flow, debt and working-capital plan create a reasonable transaction.
That analysis can reveal problems early enough to renegotiate the price, change the funding structure or request seller participation.
FAQs
What information do business acquisition financing lenders usually need first?
Buyers should at least know the purchase price, contribution, seller financing, target-company revenue and cash flow, existing debt, working-capital need and buyer credit profile.
Can seller financing reduce the outside acquisition loan requirement?
Potentially. A seller-financed portion can change the capital structure, although its terms must work with the rest of the financing.
Should working capital be calculated separately from the purchase price?
Yes. The company still needs operating liquidity after the acquisition closes.
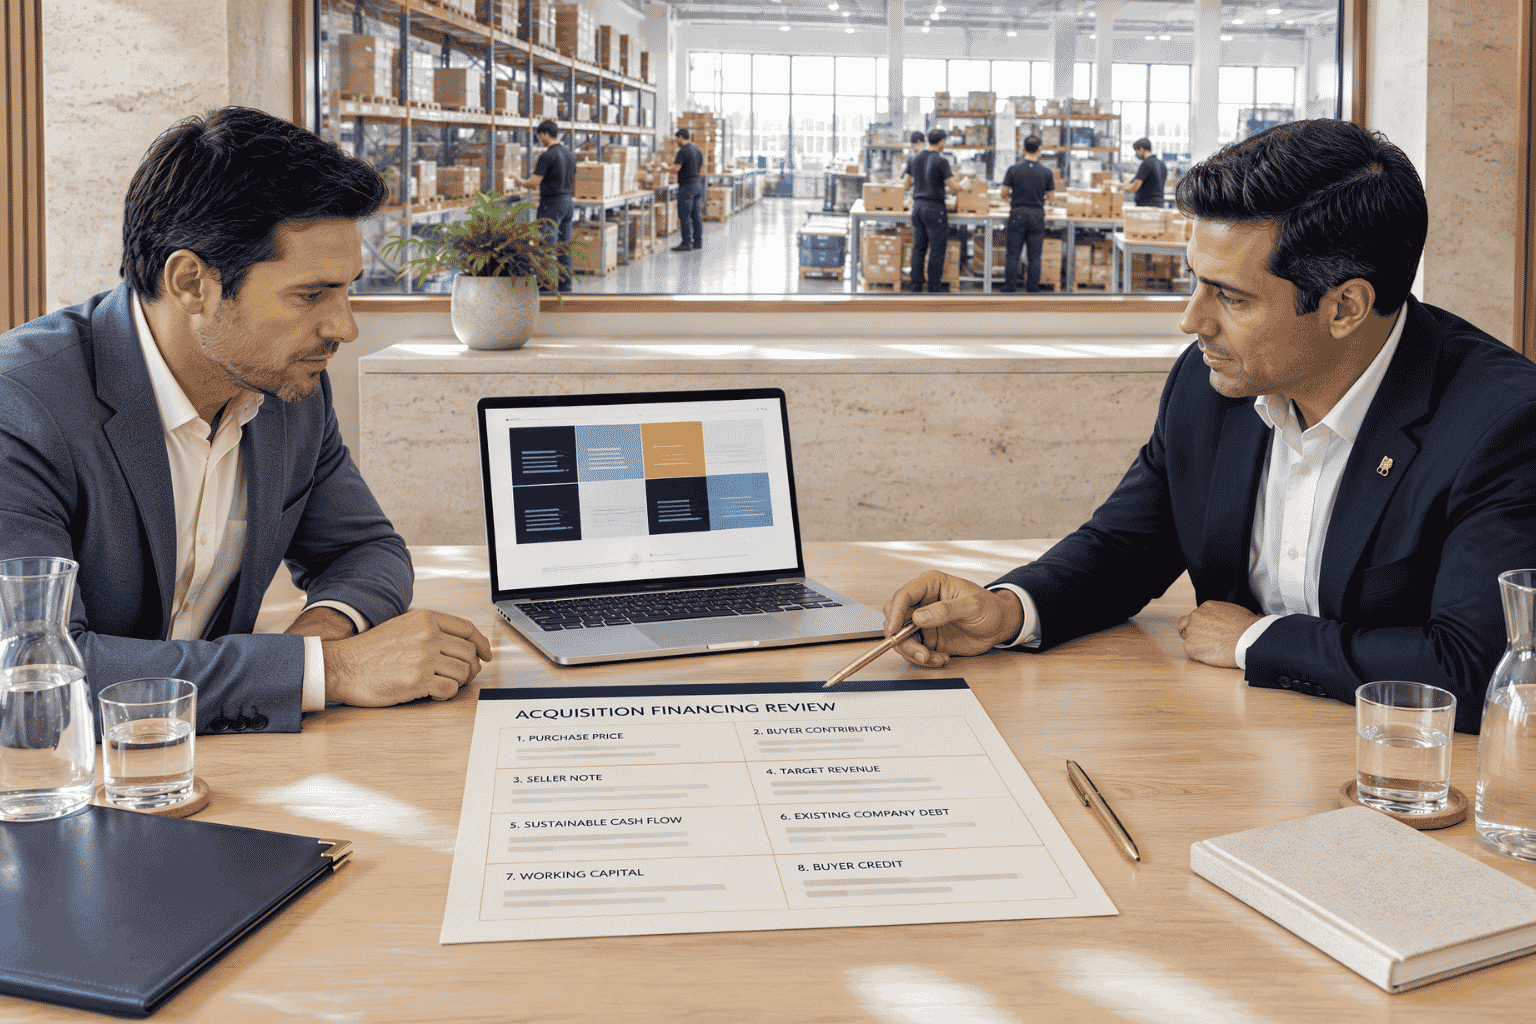 Buyers can have more productive lender discussions when the purchase price, contribution, cash flow and funding gap are already clear.