Holiday Growth Capital: Should Business Owners Use Cash or Financing for Inventory, Payroll and Marketing?
The holiday season can put business owners in a difficult capital-allocation position. Sales opportunities may be increasing at the same time the business needs more inventory, additional employees, expanded shipping capacity and a larger marketing budget.
The owner may have cash available—but using all of it to chase seasonal growth can leave the company with very little liquidity if sales arrive later than expected.
Business financing can preserve cash, but borrowing also creates a repayment obligation and financing cost.
If your business has a defined holiday growth opportunity and you already know the amount required, complete the EIN Business Funding Quick Lead Pre-Qualification using the actual funding need and current business profile.
Start With the Total Holiday Growth Budget
Do not decide whether to use cash or financing until the complete seasonal requirement is visible.
The budget may include:
- Inventory
- Temporary or permanent payroll
- Digital advertising
- Shipping and packaging
- Supplier deposits
- Warehouse or storage costs
- Technology or point-of-sale upgrades
- Emergency operating reserve
Once these costs are listed, the business can calculate how much can safely be funded internally.
Cash Is Not Free if Using It Creates Liquidity Risk
Owners often think paying cash automatically avoids financing cost and is therefore the cheapest option.
That is true only if the business can comfortably operate after the cash is spent.
If using $100,000 for seasonal inventory leaves the company unable to cover payroll, taxes or supplier obligations, the loss of liquidity creates its own risk.
Financing Is Not Free Either
Preserving cash through borrowing can be valuable, but the business must repay the financing.
The owner should compare the expected profit from the seasonal investment with the complete cost of the capital.
Borrowing should not turn a low-margin promotion into an unprofitable transaction.
Separate Inventory From Payroll
Inventory can potentially convert into revenue when products sell. Payroll is consumed as work is performed.
The business should understand how much capital is tied to products and how much is supporting labor.
That distinction can help determine which financing structure fits each need.
Marketing Needs Its Own Budget
Holiday advertising can become expensive as businesses compete for customer attention.
Do not automatically increase advertising simply because financing is available.
Use historical conversion data, customer acquisition cost and gross margins where available to determine whether additional marketing spend is likely to produce enough profitable revenue.
How Much Cash Should the Business Keep?
There is no universal reserve percentage that fits every company.
Owners should consider ordinary payroll, rent, suppliers, taxes, debt payments and unexpected expenses.
The business should remain capable of operating if holiday sales underperform projections.
Calculate the Funding Gap Instead of the Maximum Loan
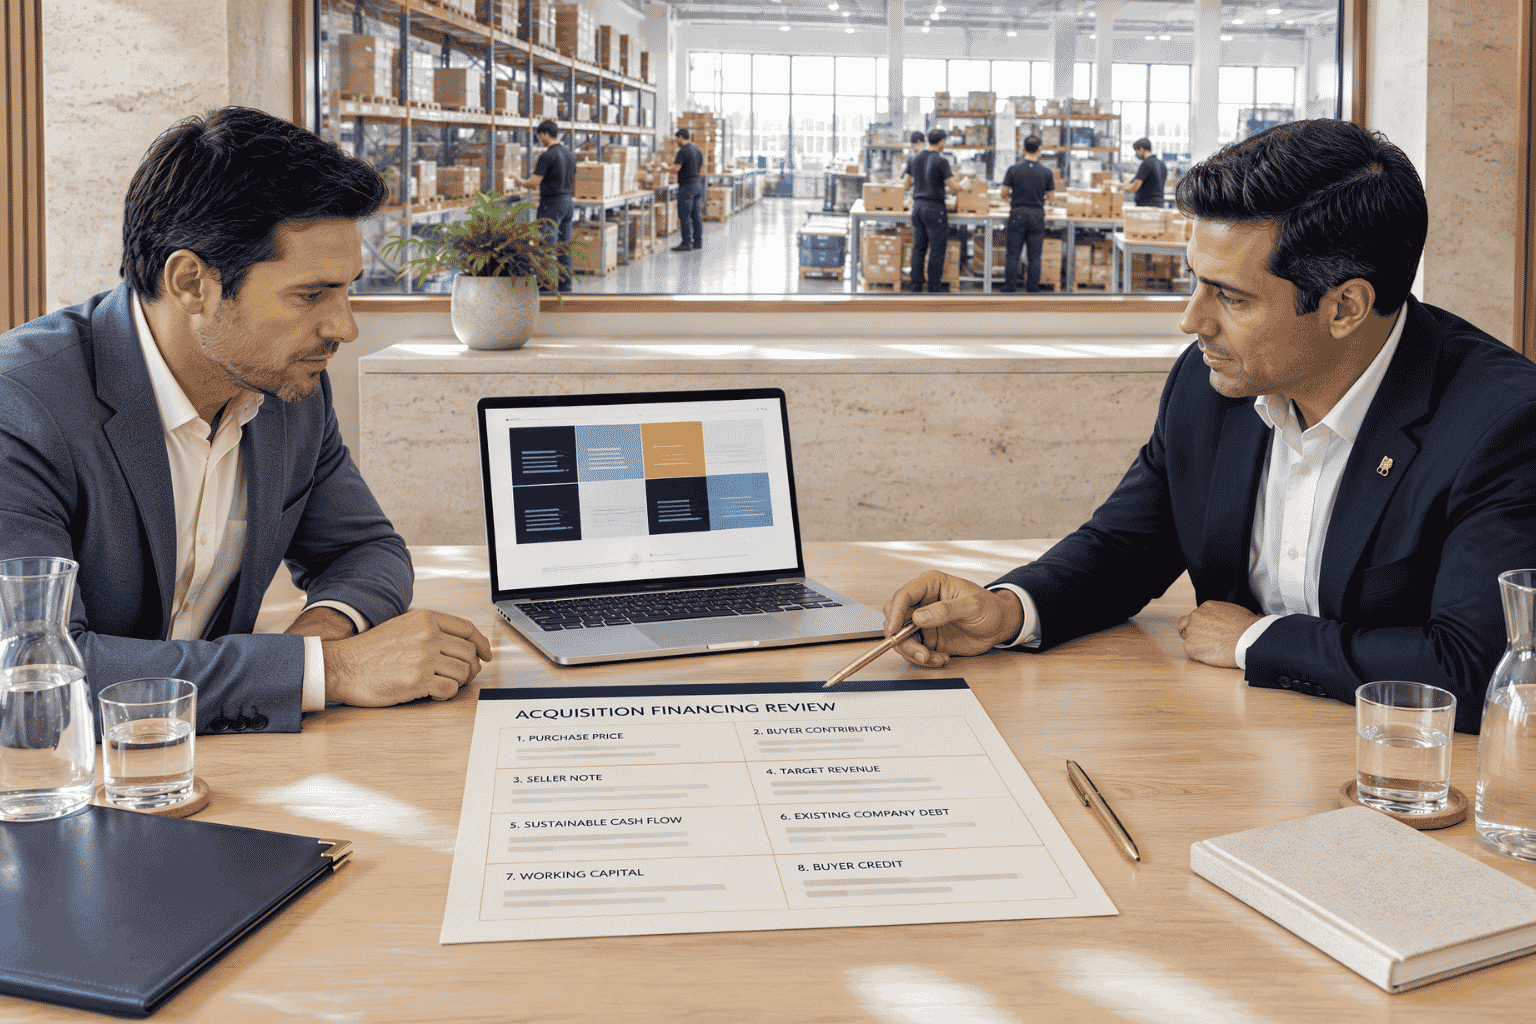
Suppose the total seasonal growth plan requires $150,000.
If the business can safely contribute $60,000 without reducing operating reserves below a comfortable level, the financing gap may be approximately $90,000.
That produces a more disciplined funding request than borrowing the maximum amount offered.
What if the Business Has Strong Revenue but Limited Cash?
This situation is common in growing businesses.
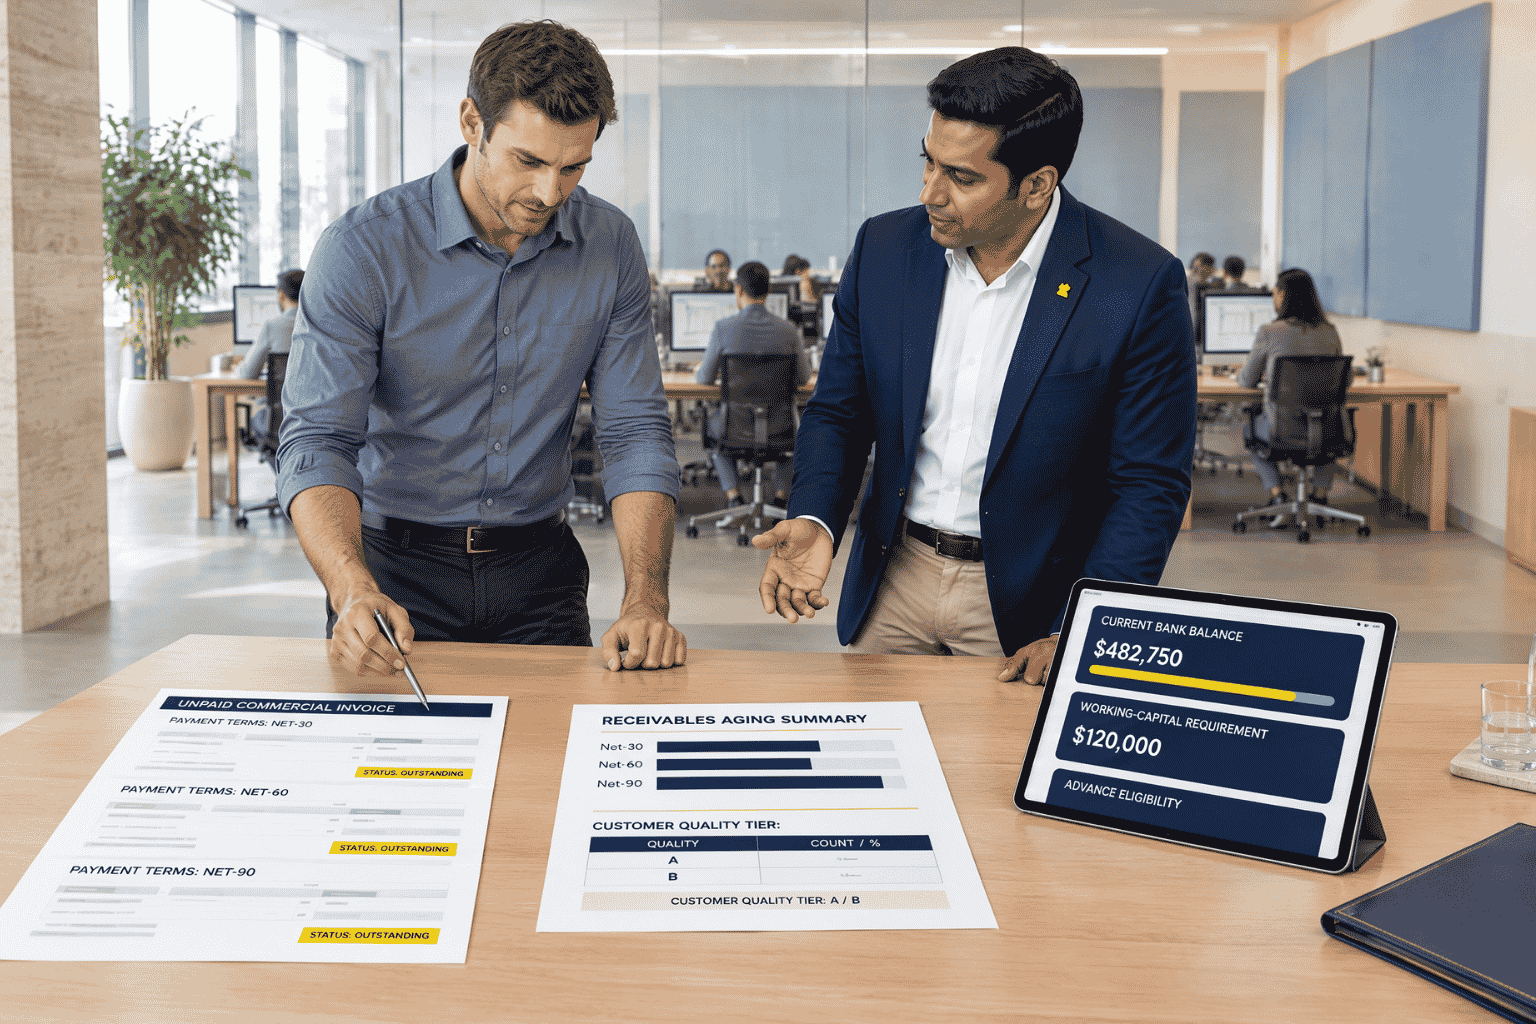
Revenue may be increasing while cash remains tied up in inventory or accounts receivable.
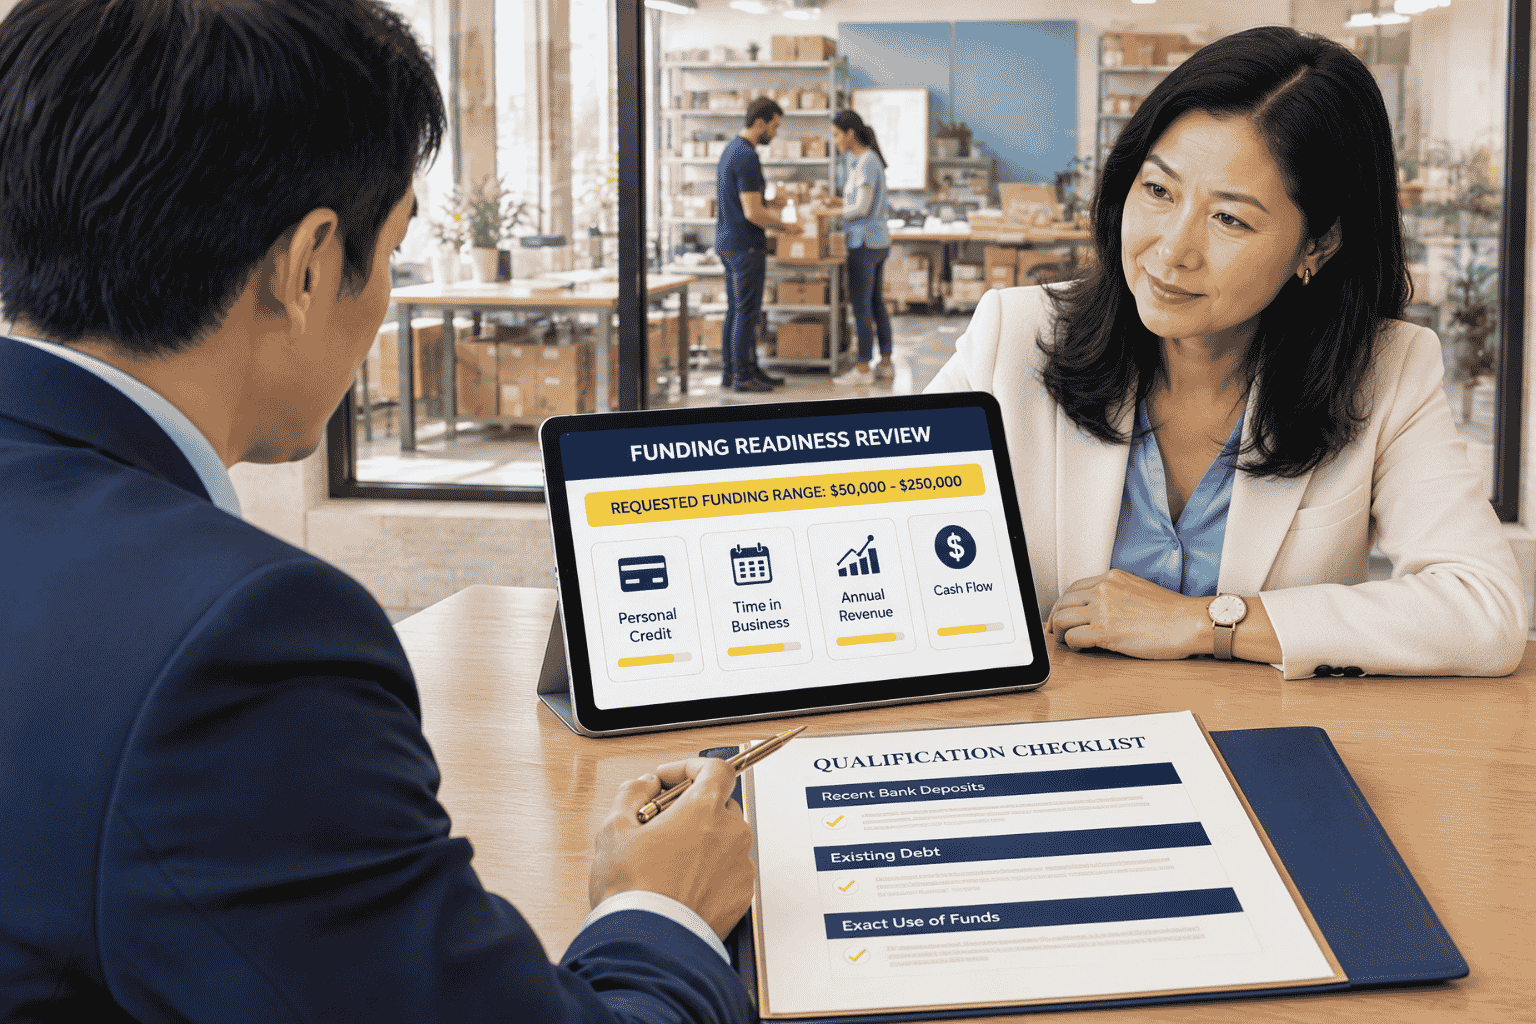
A financing provider may evaluate annual revenue, recent deposits, cash flow, business age, credit and existing debt to determine whether additional capital may be supportable.
Do Not Ignore Existing Debt
Seasonal growth can feel temporary, but the financing payment may continue after the holiday rush ends.
Review current loans, lines of credit, equipment financing and business credit-card balances before adding another obligation.
The company should be able to make payments during slower months—not only during peak holiday revenue.
What if the Business Is Growing Faster Than Expected?
Unexpected demand can be a good problem, but rapidly increasing inventory and payroll can consume cash faster than sales are collected.
The owner should distinguish between profitable growth and growth that is creating an unsustainable working-capital requirement.
Financing can bridge timing, but it cannot permanently correct an unprofitable business model.
Use Financing for a Measurable Opportunity
The strongest request ties capital to a specific result.
For example:
- $50,000 for confirmed inventory replenishment
- $25,000 for temporary seasonal payroll
- $15,000 for proven holiday advertising campaigns
- $10,000 for packaging and fulfillment
A clear budget helps the owner understand how the borrowed money is expected to produce revenue.
What Should Be Ready Before Funding Review?
- Total seasonal growth budget
- Cash the business can safely contribute
- Minimum operating cash reserve
- Financing amount required
- Annual business revenue
- Recent monthly deposits
- Current cash flow
- Existing business debt
- Current credit profile
- Expected repayment source
Owner Capital and Outside Financing Can Work Together
The decision does not always need to be all cash or all debt.
A business may use part of its own cash while financing the remaining seasonal requirement.
This can reduce borrowing while still preserving enough liquidity for normal operations.
The Holiday Season Is Temporary—The Balance Sheet Remains
Owners should avoid making a short-term sales opportunity create a long-term cash-flow problem.
The best holiday-growth plan considers what the company will look like in January and February after seasonal revenue normalizes.
If the expected profit comfortably supports the financing and the business retains enough operating cash, external capital may be worth evaluating. If the economics are weak, borrowing more does not improve the opportunity.
FAQs
Should a business use cash or financing for holiday inventory?
It depends on available liquidity, expected profitability, financing cost and how much operating cash the business needs to retain.
Can holiday payroll be financed?
Potentially, depending on the product and provider. Payroll may be part of a legitimate working-capital requirement.
Should a business borrow the maximum amount available for holiday growth?
Not automatically. The financing request should be based on the actual funding gap and an amount the business can reasonably repay.
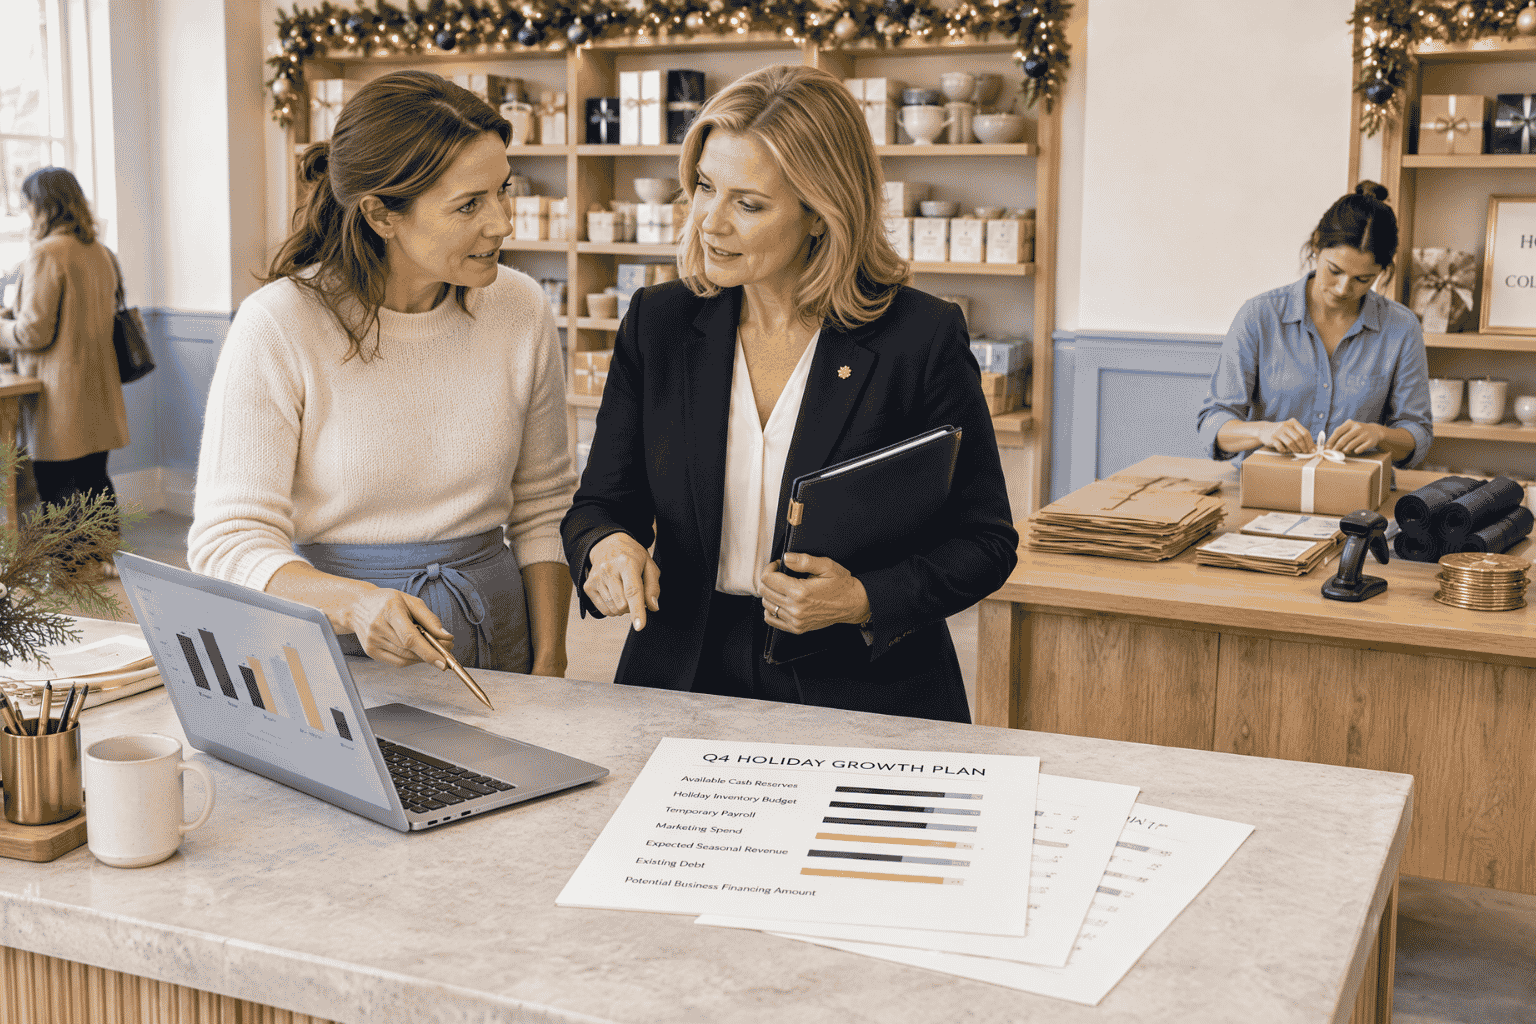 Holiday growth financing should preserve enough operating liquidity while keeping repayment obligations manageable after peak season ends.