Cargo Van Financing With EIN: What Delivery and Service Businesses Should Prepare Before Buying Vehicles
A cargo van can directly support revenue for delivery companies, contractors, repair businesses, mobile service providers and other field-based companies. When a business needs one van—or several—the vehicle purchase can become a major capital decision.
Owners searching for a business auto loan with an EIN should understand the same important distinction that applies across many business-funding products: the EIN identifies the company, but the financing provider can still evaluate the complete borrower and business profile.
If you already have a vehicle quote and the purchase is ready to move forward, complete the EIN Business Funding Quick Lead Pre-Qualification using the actual vehicle cost and current business information.
Start With the Vehicle Quote
Have the year, type, purchase price and number of vehicles being acquired available.
If the van requires shelving, refrigeration, specialized tools, wraps or other upfitting, identify those expenses separately from the base vehicle price.
Why Separate Upfitting From the Vehicle?
A service van can require significant customization before it begins producing revenue.
A plumber may add tool storage. A refrigerated-delivery company may require temperature-control equipment. A mobile medical or technical service may require specialized interior systems.
Separating those costs helps show exactly how much capital is required for the vehicle and how much is needed for additional equipment.
Does an EIN Mean the Auto Loan Is EIN-Only?
No. EINBF’s historical organic search data includes both “business auto loan EIN only” and “business auto loan with EIN,” which shows that owners actively search using this language.
The financing review can still include personal credit, business credit if established, operating history, annual revenue, cash flow, existing debt and industry.
Why Does Time in Business Matter?
A company with several years of revenue and established banking history gives the provider more operating information than a newly formed business.
That does not mean a newer company automatically has no financing path, but different providers can use different requirements.
Why Revenue Matters for a Revenue-Producing Vehicle
The provider may want to understand whether the current business can support the vehicle payment rather than relying entirely on the revenue the new van is expected to create.
Future contracts and projected routes can support the business story, but current financial performance remains important.
What Existing Vehicle Debt Should Be Disclosed?
If the company already finances trucks, vans or other vehicles, include those obligations with the rest of the business debt.
Additional vehicles increase both productive capacity and fixed repayment obligations.
One Van and a Fleet Expansion Are Different Requests
Financing one replacement van can be a relatively defined equipment need. Adding five or ten vehicles can materially change payroll, insurance, fuel, maintenance and other operating expenses.
A fleet expansion should therefore include the broader operating impact rather than only the purchase price of the vehicles.
Do Not Hide Working Capital Inside the Vehicle Request
If new vans also require hiring drivers, purchasing inventory, paying additional insurance or covering operating costs before new customers pay, identify that capital separately.
The physical vehicle and the company’s operating cash needs may fit different financing structures.
What Should Be Ready Before Funding Review?
- Vehicle quotation
- Number of vans being purchased
- Upfitting or equipment costs
- Legal business name and EIN
- Business formation date
- Annual business revenue
- Recent business deposits
- Current credit profile
- Existing vehicle and business debt
- Requested financing amount
Should You Buy the Vehicle With Cash Instead?
That depends on the company’s liquidity. Paying cash eliminates a new financing payment but reduces the money available for payroll, inventory and other operating requirements.
A company with substantial reserves can make a different decision from a growing business where the vehicle purchase would consume most available cash.
Use the Vehicle Purchase to Define the Funding Request
Rather than asking how much business financing is available, start with the actual vehicle cost and any required upfitting.
That creates a specific capital need that can be evaluated against the company’s revenue, credit, cash flow and existing obligations.
If your delivery or field-service business has an active cargo-van purchase, complete the EIN Business Funding pre-qualification with the vehicle quote and current business profile.
FAQs
Can a business seek cargo van financing with an EIN?
Potentially. The EIN is part of the business profile, but providers may also evaluate credit, business history, revenue, cash flow and existing debt.
Should vehicle upfitting costs be separated from the van purchase?
Yes. Specialized shelving, refrigeration, tools or other equipment can represent additional project costs and should be identified clearly.
Should hiring and fuel costs be included in the vehicle financing amount?
Not automatically. Those operating expenses may represent a separate working-capital need from the physical vehicle purchase.
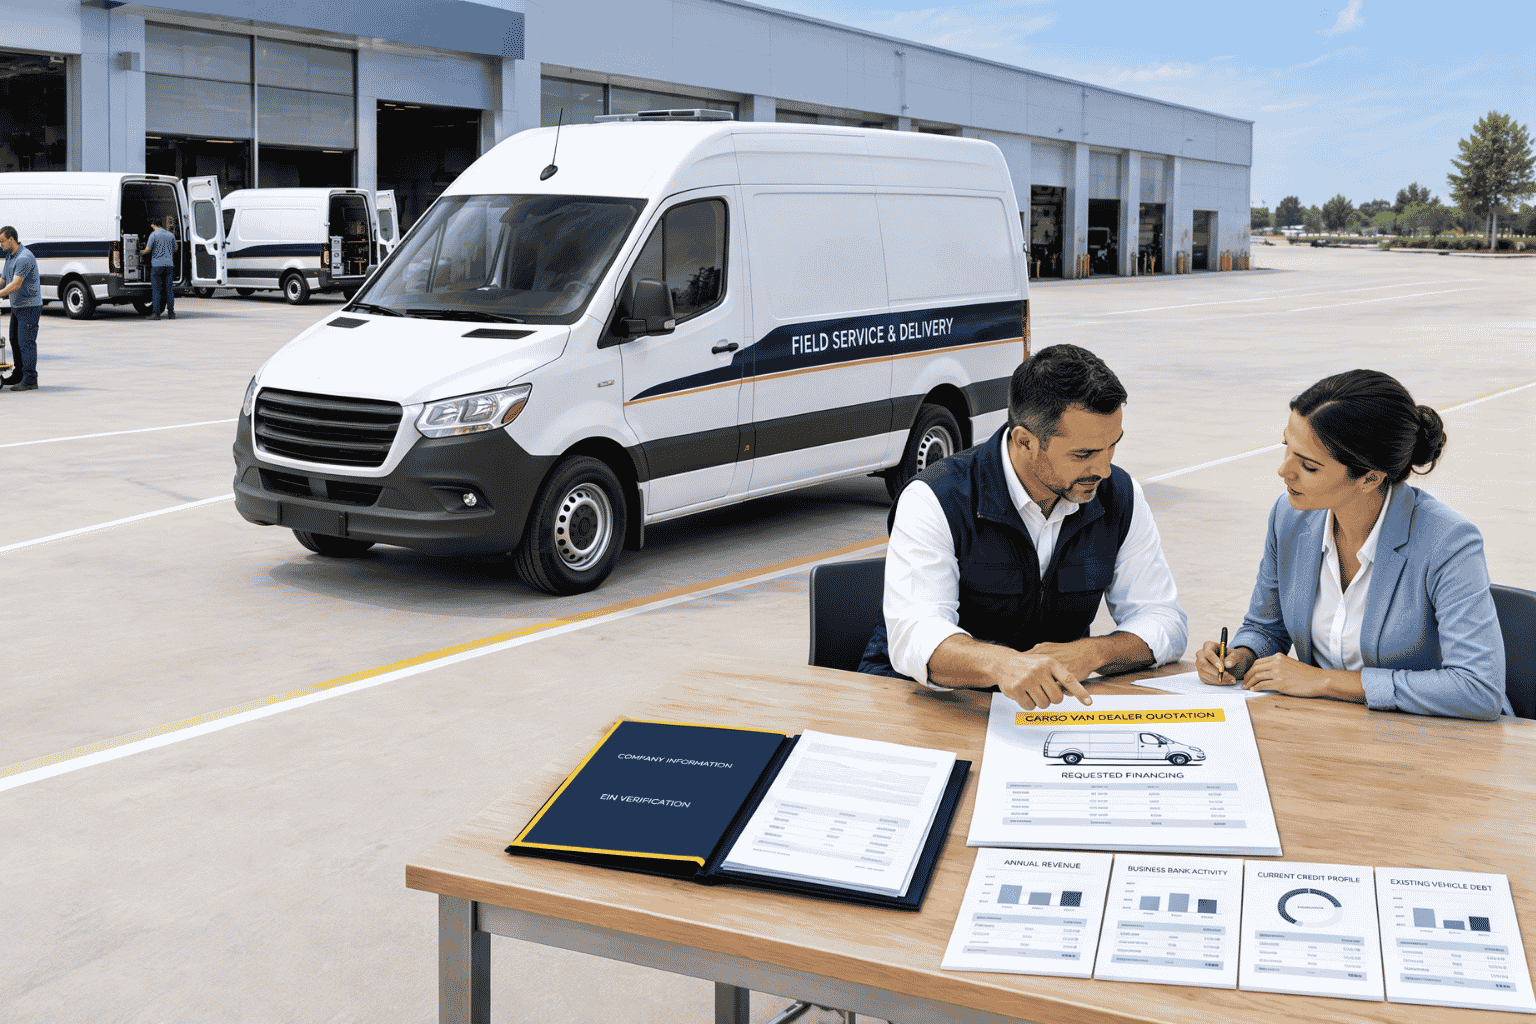 Commercial vehicle financing can depend on the vehicle purchase and the broader financial profile of the business behind it.