Business Acquisition Financing: How Seller Add-Backs Affect the Financeable Purchase Price
A business can look very different depending on whether the buyer focuses on reported profit or on adjusted earnings after seller add-backs. That difference matters when the purchase depends on business acquisition financing.
A seller may reasonably identify expenses that will disappear after ownership changes, but buyers should not assume every adjustment automatically becomes cash available to repay acquisition debt.
If you have already identified a business and know the approximate purchase price and funding requirement, complete the EIN Business Funding Quick Lead Pre-Qualification using the actual transaction numbers.
What Is a Seller Add-Back?
An add-back is generally an expense shown in the company’s historical financial results that the seller argues should be added back when estimating normalized earnings.
The reasoning is that the expense is either owner-specific, discretionary, nonrecurring or otherwise unlikely to continue under the buyer’s ownership.
Why Do Add-Backs Matter to Acquisition Financing?
Acquisition debt ultimately has to be supported by business cash flow. If adjusted earnings are overstated because questionable expenses were added back, the buyer can end up paying a price that the company’s real operating performance does not comfortably support.
That can affect both valuation and the amount of financing a lender is willing to consider.
Which Add-Backs Deserve Closer Review?
Buyers should distinguish between expenses that truly disappear and expenses that may continue after closing.
- Owner compensation above or below a market replacement level
- Personal expenses run through the company
- One-time professional fees
- Nonrecurring repairs or unusual costs
- Related-party expenses
- Travel, vehicles or benefits tied primarily to the current owner
- Temporary expenses that may actually recur
The label “add-back” should not end the analysis. The buyer should understand what created the expense and what will happen after ownership changes.
What if the Buyer Must Replace the Seller?
This is particularly important in owner-operated businesses. If the seller performs sales, management, technical work or another essential role, the buyer may need to perform that work personally or hire someone after closing.
If a replacement employee must be hired, the cost of that employee can reduce the cash flow available to support acquisition financing.
Do Not Value the Business on Add-Backs Alone
The buyer should compare adjusted earnings with actual revenue, operating expenses, bank activity, tax information and other available financial records.
A valuation based on aggressive adjustments can create a purchase price that looks reasonable on paper but produces weak debt-service capacity after closing.
Existing Business Debt Can Change the Picture
Identify all open business loans, lines of credit, equipment obligations and business credit-card balances.
Determine which obligations will be paid at closing, which remain with the company and whether any liabilities reduce the cash flow available to the buyer.
Separate Purchase Price From Financing Need
Even after agreeing on a valuation, the buyer still needs to build the actual capital structure.
- Total purchase price
- Buyer contribution
- Seller financing, if applicable
- Outside acquisition financing required
- Transaction expenses
- Post-closing working capital
The amount being financed may therefore differ substantially from both the seller’s asking price and the buyer’s negotiated purchase price.
Why Post-Closing Working Capital Still Matters
A business may show attractive normalized earnings and still require meaningful operating cash immediately after closing.
Payroll, inventory, rent, supplier payments, insurance and ordinary expenses continue while the buyer is transitioning customers, employees and vendors.
Do not use every available dollar solely to complete the acquisition.
What Should Buyers Ask About Every Material Add-Back?
For each significant adjustment, ask three questions: Was the expense actually incurred? Why is it considered nonrecurring or discretionary? Will a comparable expense exist after closing?
If the answer to the third question is yes, the buyer should be cautious about treating the full amount as additional future cash flow.
Strong Cash Flow Is More Valuable Than an Aggressive Adjustment Schedule
A transaction does not become more financeable merely because additional expenses are labeled as add-backs. Sustainable operating performance is ultimately more important than maximizing adjusted earnings.
For buyers seeking outside capital, conservative assumptions can help identify a financing problem before it becomes a closing problem.
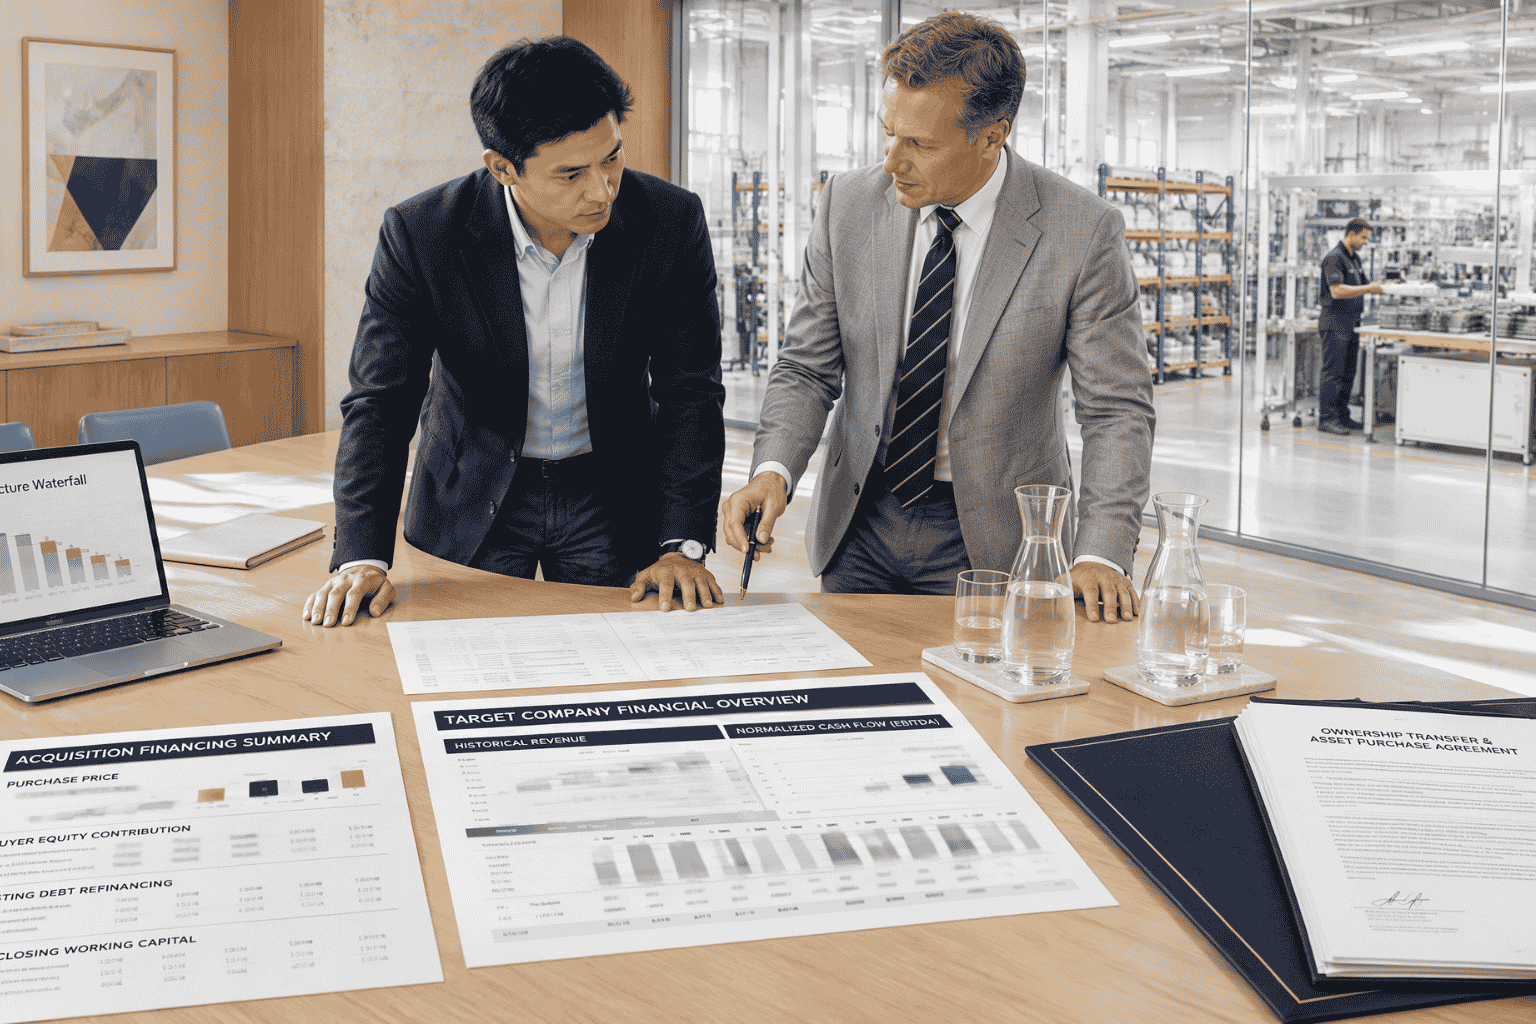
What Should Be Ready Before Funding Review?
- Purchase price
- Historical business revenue
- Reported earnings
- Proposed seller add-backs
- Normalized operating expenses
- Existing business debt
- Buyer contribution
- Outside financing requirement
- Post-closing working-capital requirement
The objective is to understand whether the company can support the proposed transaction after realistic operating expenses—not merely whether an adjusted earnings calculation supports the asking price.
FAQs
Do lenders automatically accept all seller add-backs?
No. A funding provider may evaluate whether an adjustment is reasonable, documented and genuinely unlikely to continue after the acquisition.
Can seller add-backs increase the value of a business?
They can affect normalized earnings used in valuation, but buyers should verify whether the adjusted expenses genuinely disappear after closing.
Why do add-backs matter to acquisition financing?
Acquisition debt must ultimately be supported by sustainable business cash flow, so overstated adjusted earnings can result in an unrealistic purchase price or financing request.
 Seller add-backs can affect valuation, but buyers should distinguish sustainable cash flow from expenses that may continue after closing.