Fed Holds Rates at 3.75%–4.00%: Should Small Businesses Apply for Financing Now or Wait?
The Federal Reserve held the federal funds target range at 3.75% to 4.00% at its October 28, 2026 meeting. For business owners, that immediately raises a practical question: should the company apply for financing now, or wait in hopes that borrowing conditions improve?
There is no universal answer. The timing decision should start with the business need rather than an attempt to predict the next Federal Reserve move.
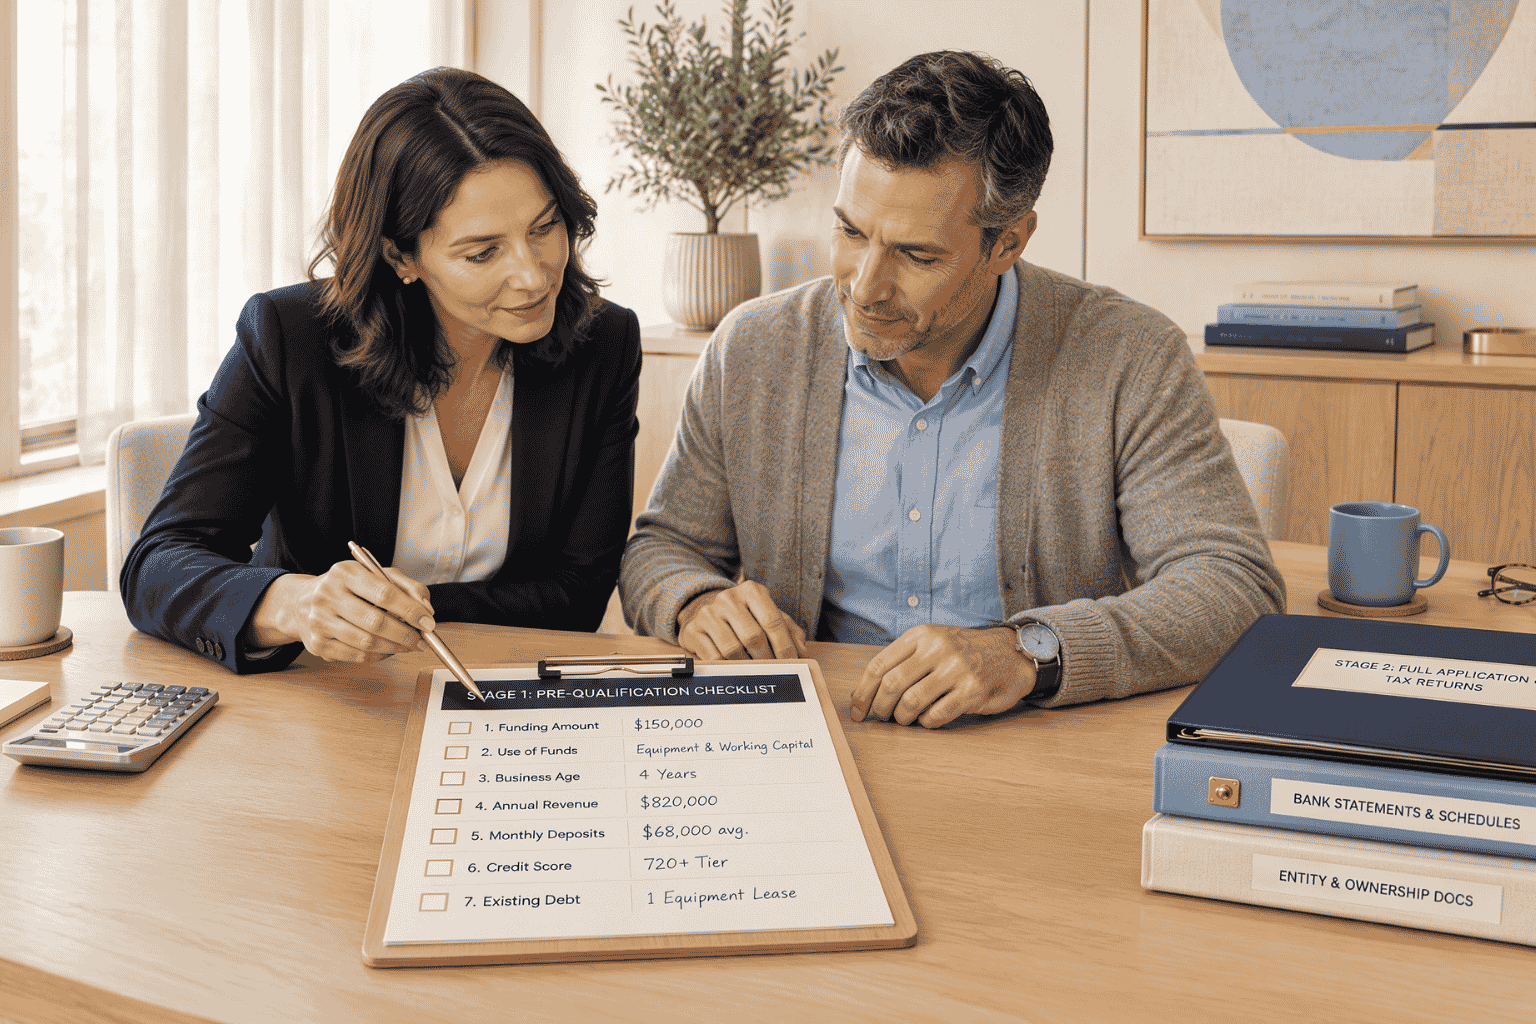
If your company has an active capital requirement today, complete the EIN Business Funding Quick Lead Pre-Qualification using the amount needed, use of funds, revenue, credit and existing debt.
What Did the Federal Reserve Do?
On October 28, the Federal Open Market Committee maintained the federal funds target range at 3.75% to 4.00%.
The federal funds rate is not the interest rate every small business receives, but monetary policy influences the broader cost of credit and benchmark rates used throughout financial markets.
Does a Fed Hold Mean Your Business Loan Rate Will Not Change?
No. Business financing pricing depends on much more than the Federal Reserve’s target rate.
The lender, financing product, borrower credit, business revenue, cash flow, collateral where applicable, repayment structure, term and overall risk can all affect the cost of capital.
Should a Business Wait for Lower Rates?
Waiting can make sense when the funding need is optional and the company has flexibility. But waiting also has a cost if delaying capital prevents the business from purchasing required equipment, fulfilling orders, increasing inventory or addressing a real operating need.
The relevant question is whether the economic benefit of the financing justifies its current cost.
When Waiting May Be Reasonable
A business may have more flexibility to delay when:
- The planned investment is optional
- Current equipment remains adequate
- There is no immediate inventory or payroll gap
- The project does not have a fixed deadline
- The company expects its borrower profile to improve materially soon
When Waiting Can Cost the Business More
Delaying financing can become expensive when the capital addresses an immediate revenue-producing need.
For example, a contractor may lose a project without necessary equipment, a retailer may miss a seasonal inventory window or a manufacturer may continue losing production time because an essential machine needs replacement.
The financing decision should compare the cost of borrowing with the cost of not acting.
Do Not Focus Only on the Interest Rate
Two financing offers can have similar headline rates and very different economics.
Review the repayment frequency, fees, loan term, prepayment structure, collateral or personal-guarantee requirements where applicable and total dollars expected to be repaid.
How Does Credit Affect the Rate Decision?
A stronger borrower profile can give the business more financing categories to compare.
The EIN Business Funding guidance describes a generally competitive profile as approximately 700+ personal credit, two or more years in business, $250,000+ annual revenue and positive, consistent cash flow.
Meeting those benchmarks does not guarantee financing, but stronger borrowers may have more flexibility to compare products and pricing.
What About a Business With 600–680 Credit?
Alternative or online financing may use different credit and operating-history thresholds from traditional banks.
For those borrowers, the decision may be less about waiting for a small change in benchmark interest rates and more about improving the overall funding profile.
Use of Funds Should Drive the Loan Structure
A long-lived asset such as equipment should not automatically be financed the same way as a short seasonal inventory need.
Match the financing structure to what the capital is expected to accomplish and how long the business will benefit from the expenditure.
What Should Owners Review Before Applying?
- Exact amount needed
- Specific use of funds
- Current credit profile
- Annual revenue
- Current cash flow
- Existing business debt
- Expected return or operating benefit from the capital
- How quickly the funding is actually needed
Rate Forecasting Should Not Replace Business Planning
No business owner can know with certainty where rates will be several months from now.
A financing decision based entirely on predicting the next policy move can delay a useful investment or encourage unnecessary borrowing.
The better approach is to determine whether the business needs capital now, can support repayment now and has an economic reason to deploy the funds now.
Apply Based on the Business Case
If a company can wait without sacrificing revenue, operations or a time-sensitive opportunity, waiting may be reasonable.
If the capital is necessary to solve a documented business problem or pursue a measurable opportunity, the current financing options should be evaluated on their actual terms rather than rejected solely because benchmark rates might change later.
FAQs
What is the current federal funds target range?
The Federal Reserve maintained a target range of 3.75% to 4.00% at its October 28, 2026 meeting.
Does a Fed rate hold mean every business loan rate stays the same?
No. Business-loan pricing also depends on the lender, product, borrower qualifications, repayment structure and other underwriting factors.
Should a small business wait for rates to fall before borrowing?
It depends on the urgency and economics of the business need. Owners should compare the current financing cost with the cost or lost opportunity created by waiting.
 A steady federal funds rate does not make every business loan unchanged; borrower profile and loan structure still matter.