Selling Your Business? Plan the Ownership Transition Before You Go to Market
Thinking about selling your business?
It is easy to focus on valuation, buyers and the closing date.
But another question can matter just as much:
What happens the day after ownership changes?
Depending on the business and transaction, a buyer may expect some level of seller transition support after closing.
Owners can benefit from deciding in advance what they are realistically willing and able to provide.
Why Transition Planning Matters
A buyer is not only acquiring historical financial performance.
The buyer may also need to understand how the business actually operates.
That can include:
- Customer relationships
- Vendor relationships
- Employee responsibilities
- Operating procedures
- Technology and systems
- Scheduling and workflow
- Industry-specific knowledge
- Other owner-held knowledge
If too much of that information exists only in the seller’s head, the transition can become more difficult.
Decide How Long You Can Stay Involved
Some sellers want a clean exit immediately after closing.
Others may be willing to remain involved for a limited transition period.
There is no single correct arrangement.
The appropriate period depends on the business, the buyer, the transaction and the parties’ negotiated expectations.
Before going to market, sellers should think about what they are comfortable offering.
Training Can Be Part of the Handoff
A buyer may need help learning company-specific processes.
Potential transition topics could include:
- Daily operating routines
- Customer-service processes
- Vendor ordering
- Pricing practices
- Employee scheduling
- Inventory procedures
- Technology systems
- Reporting practices
The more organized the business is before the sale, the easier this information may be to transfer.
Customer Introductions May Matter
In some businesses, key customer relationships are closely connected to the owner.
A buyer may therefore want help introducing the new ownership or management team.
The seller should consider which relationships may require a deliberate handoff and how those introductions should be handled.
Customer communication should be coordinated carefully so the transaction remains confidential until the appropriate stage.
Vendor and Supplier Relationships Need Attention Too
Important suppliers may also need to understand the ownership transition.
A buyer may need information about:
- Primary vendors
- Ordering procedures
- Payment terms
- Key contacts
- Supply constraints
- Contractual arrangements
A seller who has managed those relationships personally should think about how they can be transferred to the buyer.
Employee Continuity Can Affect the Transition
Employees often carry important operational knowledge.
Depending on the transaction, a buyer may want to retain key staff after closing.
Sellers should understand who performs essential functions and which responsibilities would become difficult to replace quickly.
The timing and manner of employee communication should be handled carefully and in accordance with the transaction plan and applicable requirements.
Document What the Owner Knows
Many business owners perform tasks automatically because they have been doing them for years.
The buyer may not know those routines.
Before a sale, it can be useful to document important operating information such as:
- Standard procedures
- Recurring tasks
- Key contacts
- Important passwords and access processes
- Vendor information
- Customer-service practices
- Maintenance schedules
- Other business-specific knowledge
Sensitive information should still be handled securely and shared only at the appropriate transaction stage.
Think About the Owner’s Role Before the Sale
If the owner personally handles sales, customer relationships, purchasing, hiring, operations and major decisions, the buyer may view the transition differently from a business with an established management team.
Reducing unnecessary owner dependence before going to market can help make the business easier to transfer.
Transition Support Should Be Clearly Defined
If post-closing support becomes part of the transaction, the parties should define expectations clearly.
Questions may include:
- How long will the seller remain available?
- How many hours of support are expected?
- Will support be on-site or remote?
- What subjects will the seller cover?
- Will additional consulting be compensated?
- What happens after the agreed transition period ends?
These matters should be reflected appropriately in the transaction documents with advice from qualified legal counsel.
Do Not Promise More Than You Can Deliver
A seller may be eager to keep the deal moving.
But agreeing to an unrealistic transition commitment can create problems later.
If the seller plans to retire, relocate or begin another business, those plans should be considered before agreeing to an extended post-closing role.
A Good Transition Can Protect Business Continuity
The purpose of transition planning is not to keep the seller permanently involved.
It is to help important knowledge, relationships and responsibilities move from the seller to the buyer in an orderly way.
That can support continuity for customers, employees, vendors and the business itself.
Plan the Exit Before the Closing
Before listing a business for sale, ask:
- What knowledge exists only with me?
- Which customer relationships need introduction?
- Which vendors depend on my personal involvement?
- Who runs the business when I am away?
- How much training could a buyer reasonably need?
- How long am I willing to remain involved?
Those answers can help shape both the sale process and the eventual transition.
EIN Business Brokers provides a starting point for business owners preparing for a potential sale and planning the transaction process.
Transition expectations, buyer requirements, transaction structures, legal obligations and closing outcomes vary by business and transaction. Sellers should obtain appropriate legal, accounting, tax and other professional advice. Preparing a transition plan does not guarantee buyer interest, valuation or a completed sale.
Frequently Asked Questions
Do business sellers usually stay after closing?
It depends on the transaction. Some buyers may request a short training or transition period, while other transactions may require little seller involvement after closing.
What should a seller include in a business transition plan?
A transition plan may address training, operating procedures, customer and vendor introductions, employee responsibilities, systems access and other company-specific knowledge that the buyer may need.
Should post-closing seller support be documented?
Yes. If transition support is part of the transaction, the duration, scope, availability and any compensation should be clearly addressed in the applicable transaction documents with qualified legal counsel.
Can reducing owner dependence help before selling a business?
It can improve transferability by making important responsibilities, relationships and operating knowledge less dependent on one individual. The effect on buyer interest or valuation varies by business.
Take the Next Step
Subscribe on YouTube:
https://www.youtube.com/@enterpriseindustrynetwork
Thinking about selling your business?
Get Started with EIN Business Brokers:
https://www.einbb.com/get-started/
Exit. Acquire. Invest.
Explore Enterprise Industry Network
https://enterpriseindustrynetwork.com/
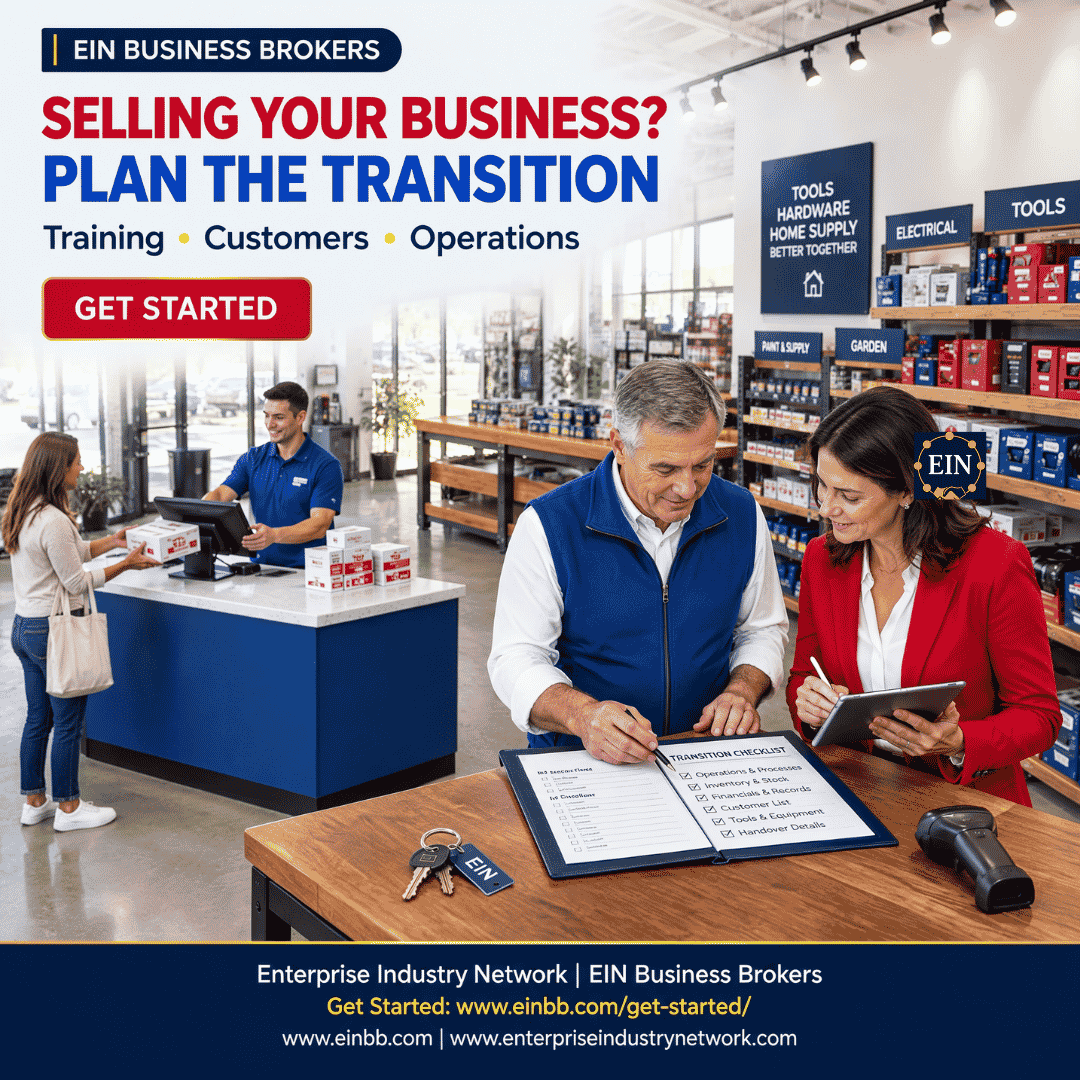 A business-sale transition may include training, customer introductions, operational handoff and a clearly defined period of seller support.