Invoice Financing for Holiday Cash Flow: Turn Net-30 and Net-60 Receivables Into Working Capital
A company can have one of its strongest sales periods of the year and still experience a serious cash-flow shortage.
This often happens in B2B businesses during the holiday season. The company ships products or completes services in November and December, but customers may not pay the invoices for 30, 45 or 60 days.
Meanwhile, payroll, suppliers, freight, rent and operating expenses continue immediately.
For businesses with eligible commercial receivables, invoice financing may be worth evaluating as a way to access working capital before customers pay.
If your business has outstanding B2B invoices and an active working-capital need, complete the EIN Business Funding Quick Lead Pre-Qualification with your current revenue, business age and use of funds.
What Creates the Holiday Receivables Gap?
Imagine a wholesaler ships $150,000 of products in late November.
The customers are reliable commercial buyers, but the invoices are payable in 45 days. The wholesaler still needs to pay employees, suppliers, freight and warehouse expenses in December.
The accounting records may show strong sales and substantial accounts receivable while the business bank account remains tight.
This is a timing problem rather than necessarily a profitability problem.
What Is Invoice Financing?
Invoice financing is a broad category of funding tied to eligible unpaid business invoices.
Depending on the structure, a provider may advance a portion of qualifying receivables before the customer pays. The specific terms, fees, repayment mechanics and customer-notification requirements can vary by provider.
The important point is that the financing is connected to real invoices generated from completed commercial transactions.
Which Businesses May Find It Useful?
Invoice-related funding is generally most relevant for businesses that sell to other businesses or organizations on payment terms.
Examples can include:
- Wholesalers
- Manufacturers
- Staffing companies
- Transportation and logistics companies
- Commercial contractors
- Business-service providers
- Suppliers
- Distributors
A consumer retailer collecting payment at the point of sale does not have the same receivables structure.
The Customer’s Credit Quality Can Matter
Invoice financing is different from a conventional unsecured business loan because the underlying receivable can be an important part of the financing decision.
A provider may therefore care about who owes the invoice and whether the customer has a history of paying commercial obligations.
A strong invoice from a credible customer can present differently from a disputed or overdue invoice from a financially weak customer.
New Invoices Are Different From Old Overdue Receivables
Businesses should not assume that every account receivable is financeable.
An invoice that is already substantially overdue may be viewed differently from a recent invoice issued under normal payment terms.
Prepare an accounts-receivable aging report so you understand which invoices are current and which are becoming problematic.
Invoice Financing Is Not the Same as a General Working Capital Loan
A working capital loan may be based more broadly on the overall business profile, including credit, operating history, revenue, cash flow and bank deposits.
Invoice financing is linked more directly to eligible receivables.
A company with strong unpaid B2B invoices but a temporary cash-flow gap may therefore want to compare the two structures.
Why the Holiday Season Can Make Receivables Financing Relevant
Holiday demand can create a sequence of expenses before receivables convert into cash.
The business may need to:
- Buy additional inventory
- Pay seasonal employees
- Fund freight and shipping
- Place supplier deposits
- Cover warehouse expenses
- Prepare for January operations
If customer invoices will not be paid until after the peak season, the company can experience a temporary liquidity shortage.
Do Not Finance Invoices That Are Not Real or Complete
Invoice financing depends on legitimate commercial receivables.
The invoice should generally relate to goods delivered or services completed according to the underlying business arrangement.
Businesses should not create premature or inaccurate invoices simply to seek funding. Accurate documentation protects both the company and the financing process.
Calculate the Actual Working-Capital Requirement
Do not automatically seek financing against every eligible invoice.
Determine the amount the business actually needs.
If the company has $200,000 of receivables but only needs $70,000 to bridge payroll and supplier payments, the funding requirement should be built around the real cash-flow gap.
Compare Cost With the Gross Profit Being Protected
Accessing receivables early has a cost.
The business should understand whether financing protects enough profitable sales to justify that cost.
If receiving cash earlier allows the company to accept additional profitable orders, avoid late supplier payments or maintain critical payroll, the financing may have strategic value.
If margins are already very thin, the financing cost deserves especially careful attention.
What About Customer Relationships?
Different invoice-financing structures can involve different levels of interaction with customers.
Business owners should understand whether customers will be notified, where payments will be directed and how the arrangement affects the company’s normal accounts-receivable process.
What Information Should the Business Prepare?
- Business legal name and EIN
- Time in business
- Annual revenue
- Accounts-receivable aging
- Eligible unpaid invoices
- Customer information
- Invoice payment terms
- Current business bank activity
- Existing debt
- Exact use of the requested funds
Invoice Financing Can Solve Timing—Not Weak Economics
A business that consistently loses money does not become healthy simply because receivables are financed earlier.
Invoice financing is most useful when the underlying sales are legitimate and profitable but customer-payment timing creates a temporary operating gap.
The company should still understand its margins, operating expenses and total debt obligations.
Plan for January Before December Ends
Many businesses focus heavily on funding the holiday rush but forget that January expenses arrive quickly.
Payroll, rent and supplier payments continue even if customer payments from December have not yet arrived.
Businesses with substantial Net-30 and Net-60 receivables should understand the January cash position before the holiday season ends.
FAQs
Can invoice financing help with holiday working capital?
Potentially. Eligible B2B receivables may support financing that provides earlier access to cash before customers pay.
Is invoice financing only for businesses with bad credit?
No. Businesses can use invoice financing primarily because of customer-payment timing, even when the company itself is financially healthy.
Are overdue invoices always eligible?
No. Eligibility depends on the provider, invoice quality, customer and other factors. Current receivables may be treated differently from substantially overdue invoices.
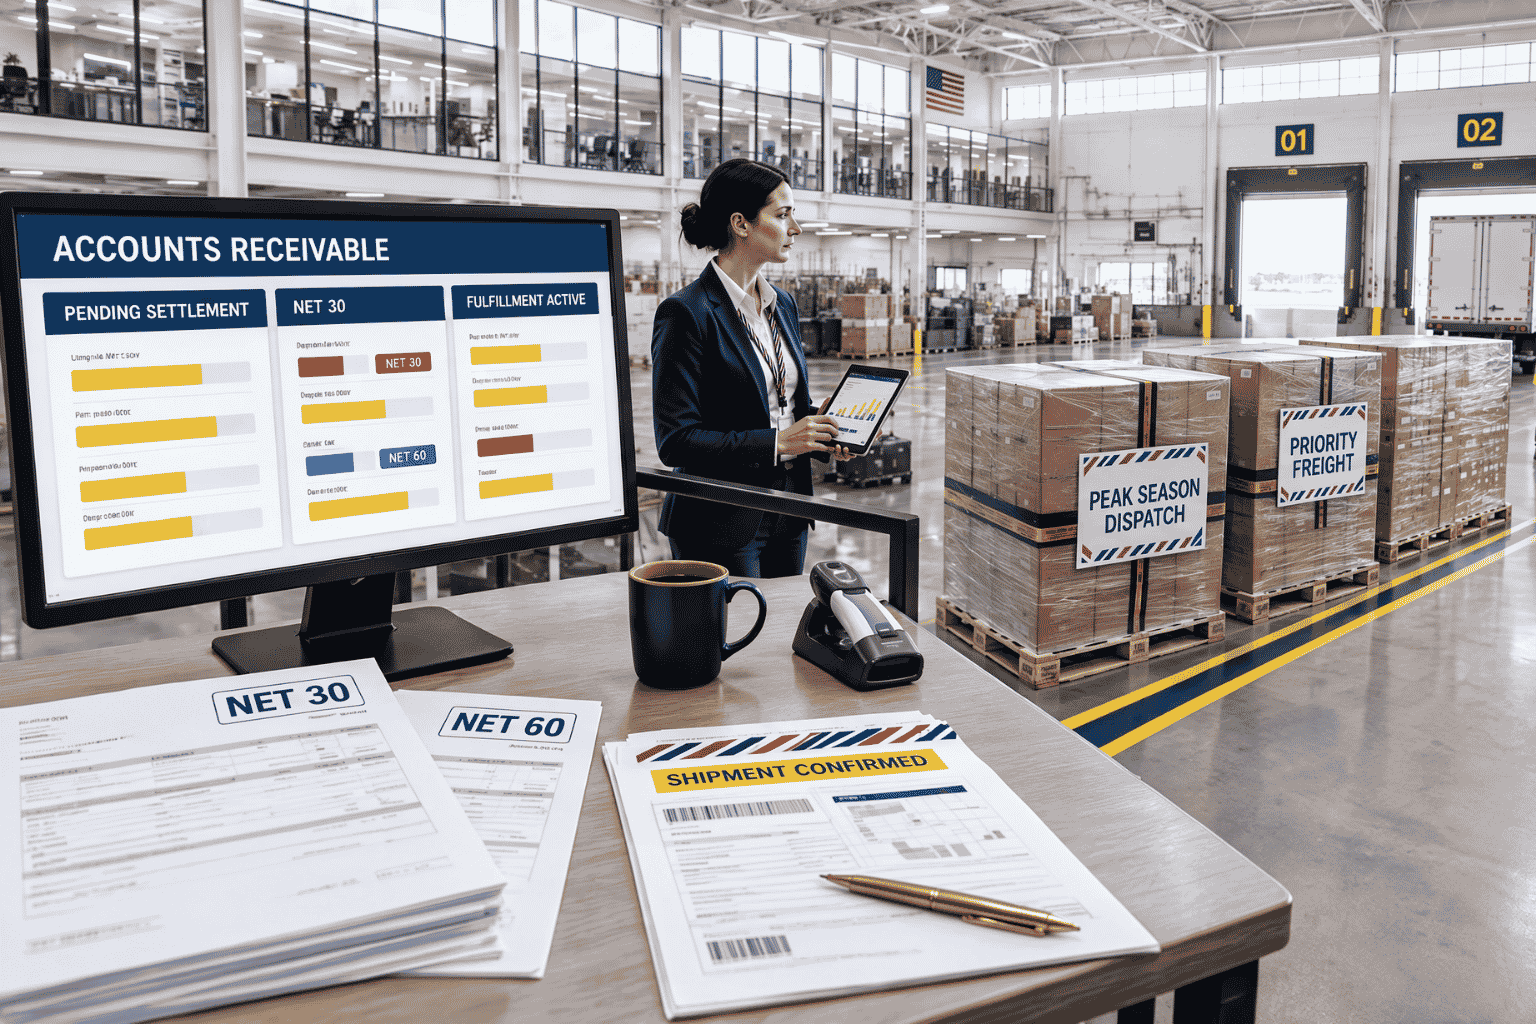 Invoice financing may help eligible B2B businesses bridge the gap between completing holiday orders and receiving customer payments.