Need Business Funding Before the Holiday Rush Peaks? Prepare These 9 Items Before You Apply
Urgency is common during the holiday season.
A supplier may require payment. Inventory may be selling faster than expected. Payroll may be approaching. A vehicle or piece of equipment may need replacement. A large customer may not pay an invoice until January.
When the funding need becomes urgent, owners often begin submitting applications immediately.
But a faster application is not necessarily a better application. Providing incomplete or inconsistent information can make the financing process harder.
If your company has an active funding requirement, complete the EIN Business Funding Quick Lead Pre-Qualification after organizing the following information.
1. Know the Exact Amount Needed
Do not begin with “I want the maximum available.”
Calculate the real business requirement.
If the company needs $35,000 for inventory, $15,000 for payroll and $10,000 for freight, the total need may be approximately $60,000.
If the business can safely contribute $20,000 without creating another cash shortage, the external funding gap may be closer to $40,000.
2. Define the Use of Funds
Different business needs can fit different financing products.
Be specific about whether the money is for:
- Inventory
- Payroll
- Equipment
- Supplier payments
- Working capital
- A business acquisition
- Commercial vehicles
- Accounts-receivable timing
“General business purposes” may be accurate in some cases, but a more specific explanation usually makes the funding requirement easier to understand.
3. Know the Business Formation Date
Time in business can affect which financing categories are worth reviewing.
A company operating for six months has a different profile from a company operating for five years.
Do not estimate the business age. Use the actual formation and operating history.
4. Prepare Annual Revenue
Annual revenue helps show the scale of the company.
The requested financing amount should make sense relative to the business’s operating size and ability to repay.
A $250,000 request can represent a very different financing decision for a company generating $300,000 annually compared with one generating several million dollars.
5. Know Recent Monthly Deposits
Annual revenue tells the longer story. Recent bank deposits show what is happening now.
This can be particularly relevant during the holiday period when sales may increase sharply.
Understand whether recent deposits are stable, growing, seasonal or declining.
6. Check the Current Credit Profile
Do not rely on a score from several months ago if the financing request is significant.
Different financing products can serve different credit ranges, but credit still influences which options may be realistic.
A stronger score does not guarantee approval, and a weaker score does not automatically mean there are no options.
7. List Existing Business Debt
Prepare current loans, lines of credit, credit cards, equipment financing and other material obligations.
Know current balances and payments.
A provider may need to determine whether the business can support another obligation alongside the debt it already carries.
8. Understand Current Cash Flow
Revenue does not equal available cash.
A business may produce strong sales while spending heavily on inventory, labor, rent and existing debt.
The financing request should reflect the company’s real capacity to make additional payments.
9. Know When the Money Is Actually Needed
Urgent does not always mean “today.”
Determine the real deadline.
A supplier deposit may be due in three days. Payroll may be due next week. Equipment may not be delivered for another month.
The timing can help determine which financing categories are realistic.
Why Complete Information Matters During the Holiday Season
The late-year period can involve compressed schedules for business owners, accountants, lenders, vendors and other participants.
A financing request that begins with organized information can be easier to evaluate than one that requires repeated corrections and follow-up.
Do Not Change the Numbers From Application to Application
Revenue, funding amount, business age and debt information should be accurate and consistent.
Changing major facts to match what an owner thinks a lender wants to hear can undermine the credibility of the financing request.
Match the Product to the Need
A business needing inventory may consider working-capital products. A company purchasing machinery may evaluate equipment financing. A business with recurring cash gaps may look at a line of credit. A company with eligible unpaid B2B invoices may consider invoice financing.
The correct product depends on the borrower profile and business purpose.
Do Not Ignore the Cost Because the Need Is Urgent
Faster financing can sometimes cost more.
The owner should understand payment frequency, total financing cost, repayment period and whether the business can support the obligation after holiday revenue slows.
Prepare Before the Cash Balance Becomes Critical
The strongest time to evaluate business funding is often before the company reaches an emergency.
An owner with several weeks of planning time has more opportunity to compare products, correct missing information and determine whether borrowing is actually necessary.
Holiday Funding Should Solve a Defined Problem
A financing request should have a clear purpose and expected repayment source.
Inventory should convert into profitable sales. Receivables should turn into cash. Equipment should support business operations. Working capital should bridge a temporary gap.
The more clearly the owner can explain the problem and the amount needed to solve it, the more focused the funding conversation becomes.
FAQs
What information should I prepare before applying for business funding?
Know the amount required, use of funds, business age, annual revenue, recent deposits, current credit, existing debt, cash flow and funding deadline.
Should I apply to several lenders immediately if the need is urgent?
Not automatically. Organizing the borrower profile and matching the financing product to the actual need can make the process more focused.
Does holiday revenue guarantee approval?
No. Seasonal sales are only one part of the business profile. Providers may also evaluate credit, cash flow, business history, debt and other factors.
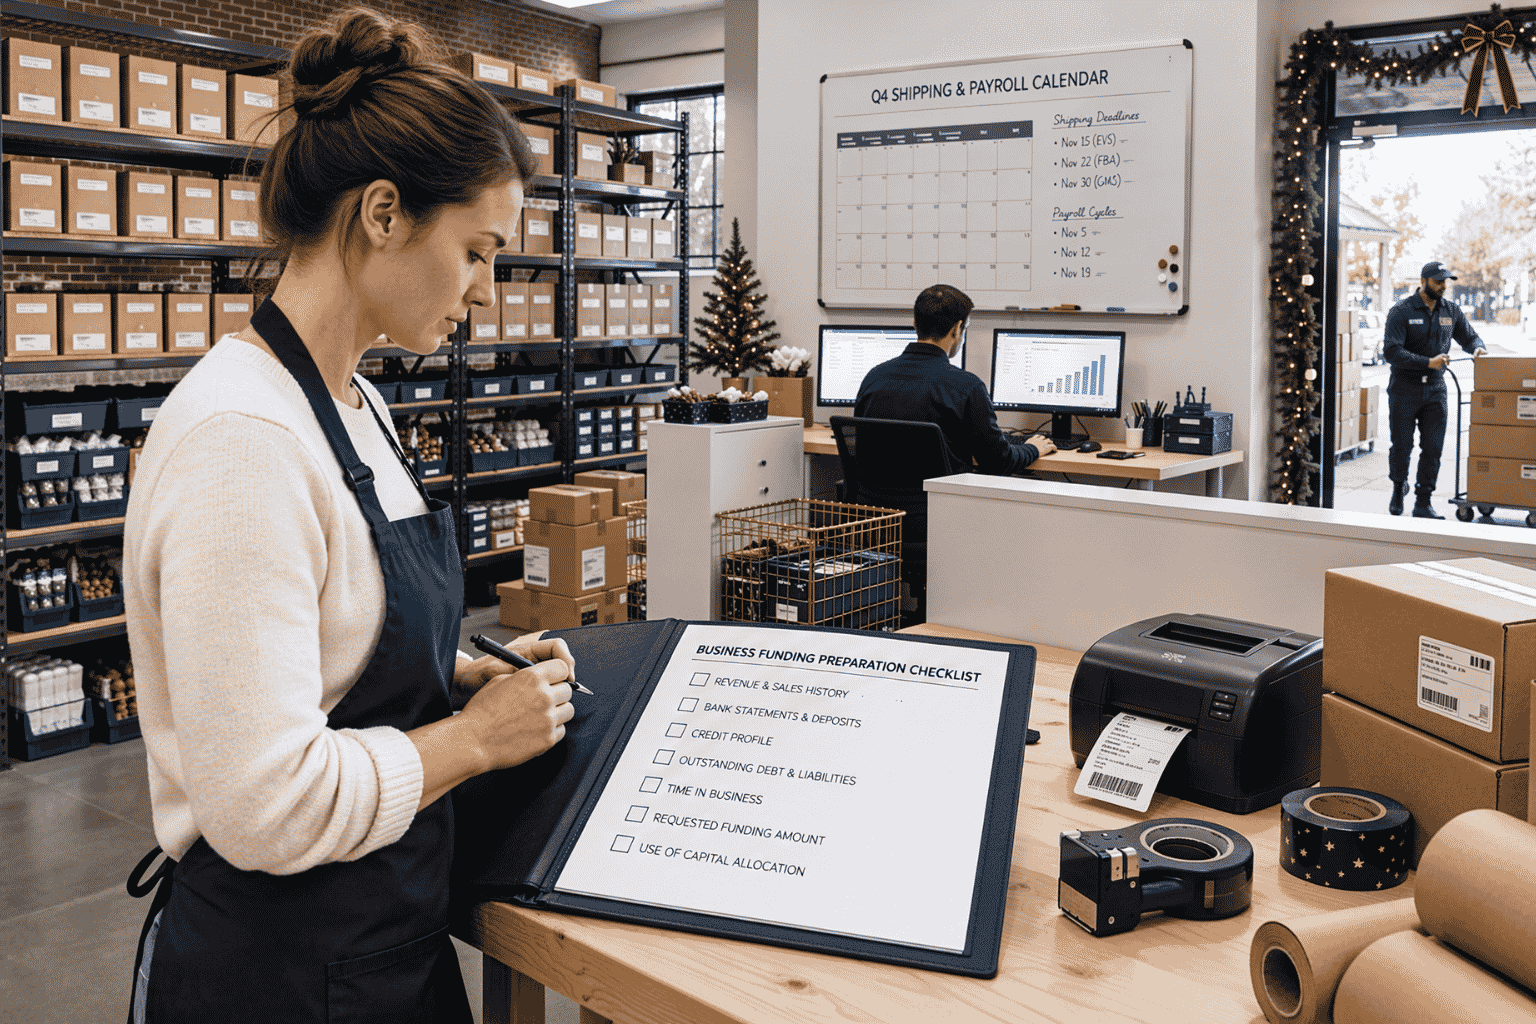 Organizing the borrower profile before applying can make an urgent holiday funding request clearer and easier to evaluate.