Business Funding With EIN Only and No Personal Guarantee: What Owners Should Know Before Applying
“EIN-only business funding” and “no personal guarantee” are two phrases business owners frequently use when looking for capital, but they describe different issues. An EIN identifies the business, while a personal guarantee concerns who may be responsible for the obligation.
If you are looking for business funding and want to understand which options may fit your current profile, start with the EIN Business Funding Quick Lead Pre-Qualification.
Does EIN-Only Mean No Personal Credit Review?
Not necessarily. The EIN Business Funding guidance identifies personal credit as a factor lenders commonly consider across business-financing categories.
An EIN does not automatically mean personal credit, ownership or repayment ability will be ignored.
Does No Personal Guarantee Mean No Underwriting?
No. Even when a financing structure does not require a personal guarantee, the provider may still evaluate business revenue, cash flow, deposits, existing debt, industry and operating history.
Which Products Commonly Involve a Personal Guarantee?
The funding guidance notes that business credit cards commonly involve a personal guarantee. For SBA 7(a), owners with 20% or more ownership generally provide a personal guarantee.
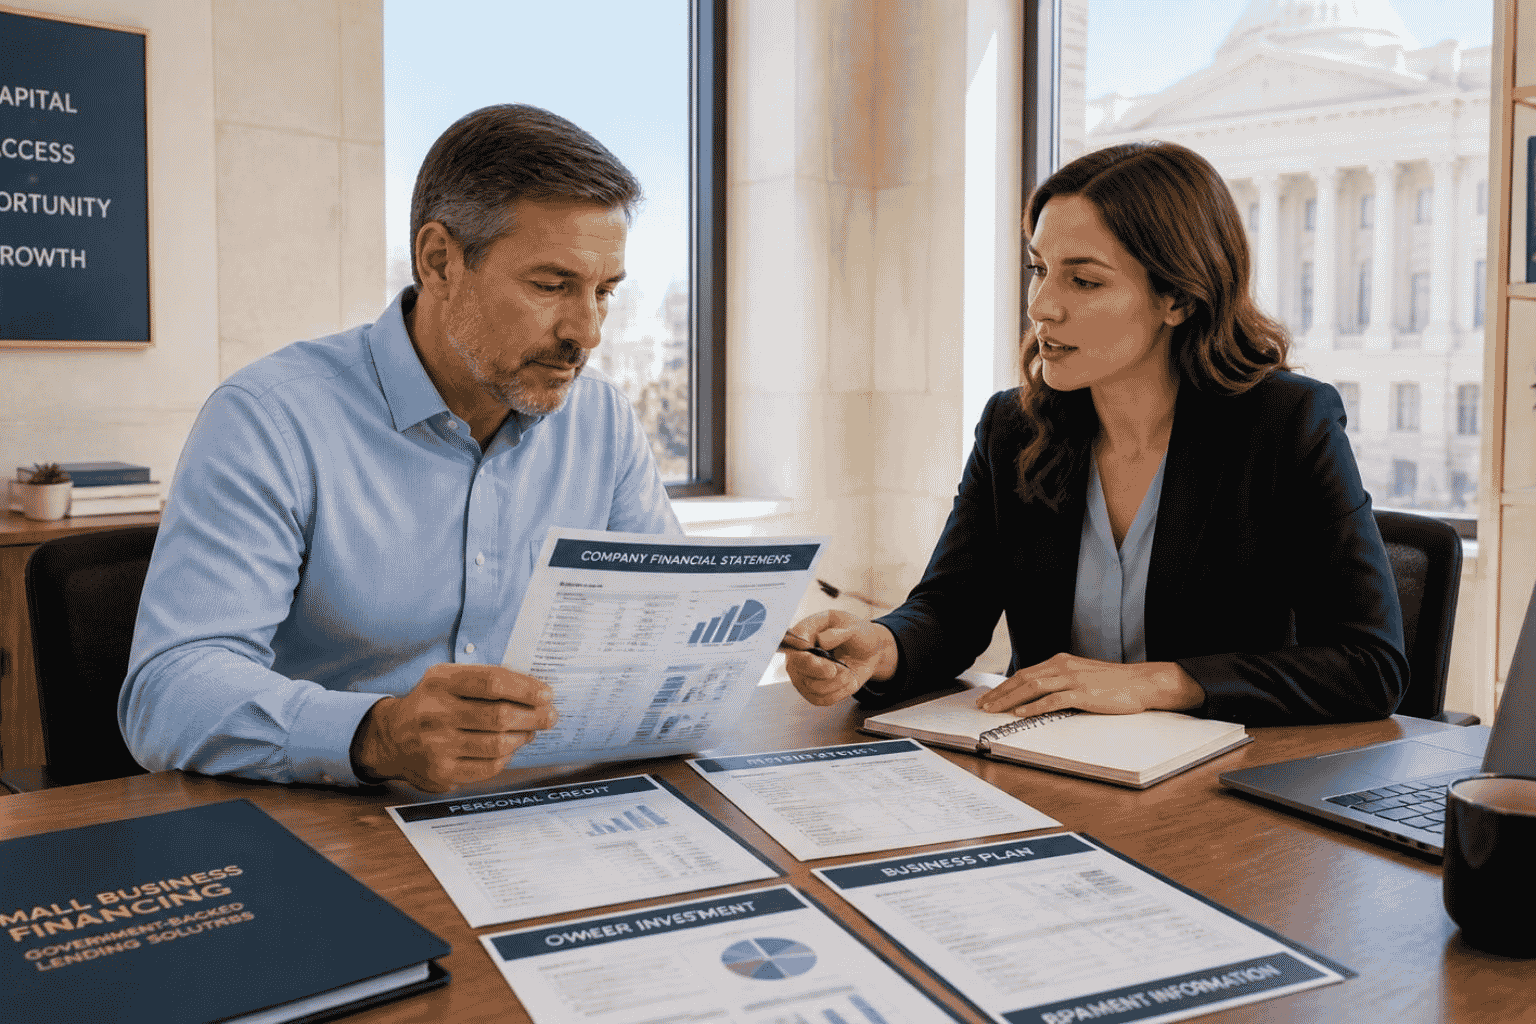
What Should an EIN-Based Applicant Have Ready?
- Legal business name
- EIN or Federal Tax ID
- Entity type and formation date
- Ownership percentage
- Annual business revenue
- Business banking information
- Current credit profile
- Existing business debt
- Requested amount and use of funds
Should You Reject Every Option That Requires a Personal Guarantee?
That is a business decision for the owner. The important step is understanding the actual terms, repayment obligation and risk before accepting financing.
If avoiding a personal guarantee is important to you, state that requirement clearly when completing the EIN Business Funding pre-qualification, while also providing your complete business profile.
FAQs
Does EIN-only business funding mean no personal credit check?
Not necessarily. Funding providers may still evaluate personal credit, business revenue, cash flow, operating history and other underwriting factors.
Does no personal guarantee mean no underwriting?
No. A funding provider may still review the complete business and borrower profile even when a personal guarantee is not required.
What information should I prepare for an EIN-based funding request?
Prepare your EIN, entity information, ownership percentage, annual revenue, banking information, credit profile, existing debt, requested amount and use of funds.
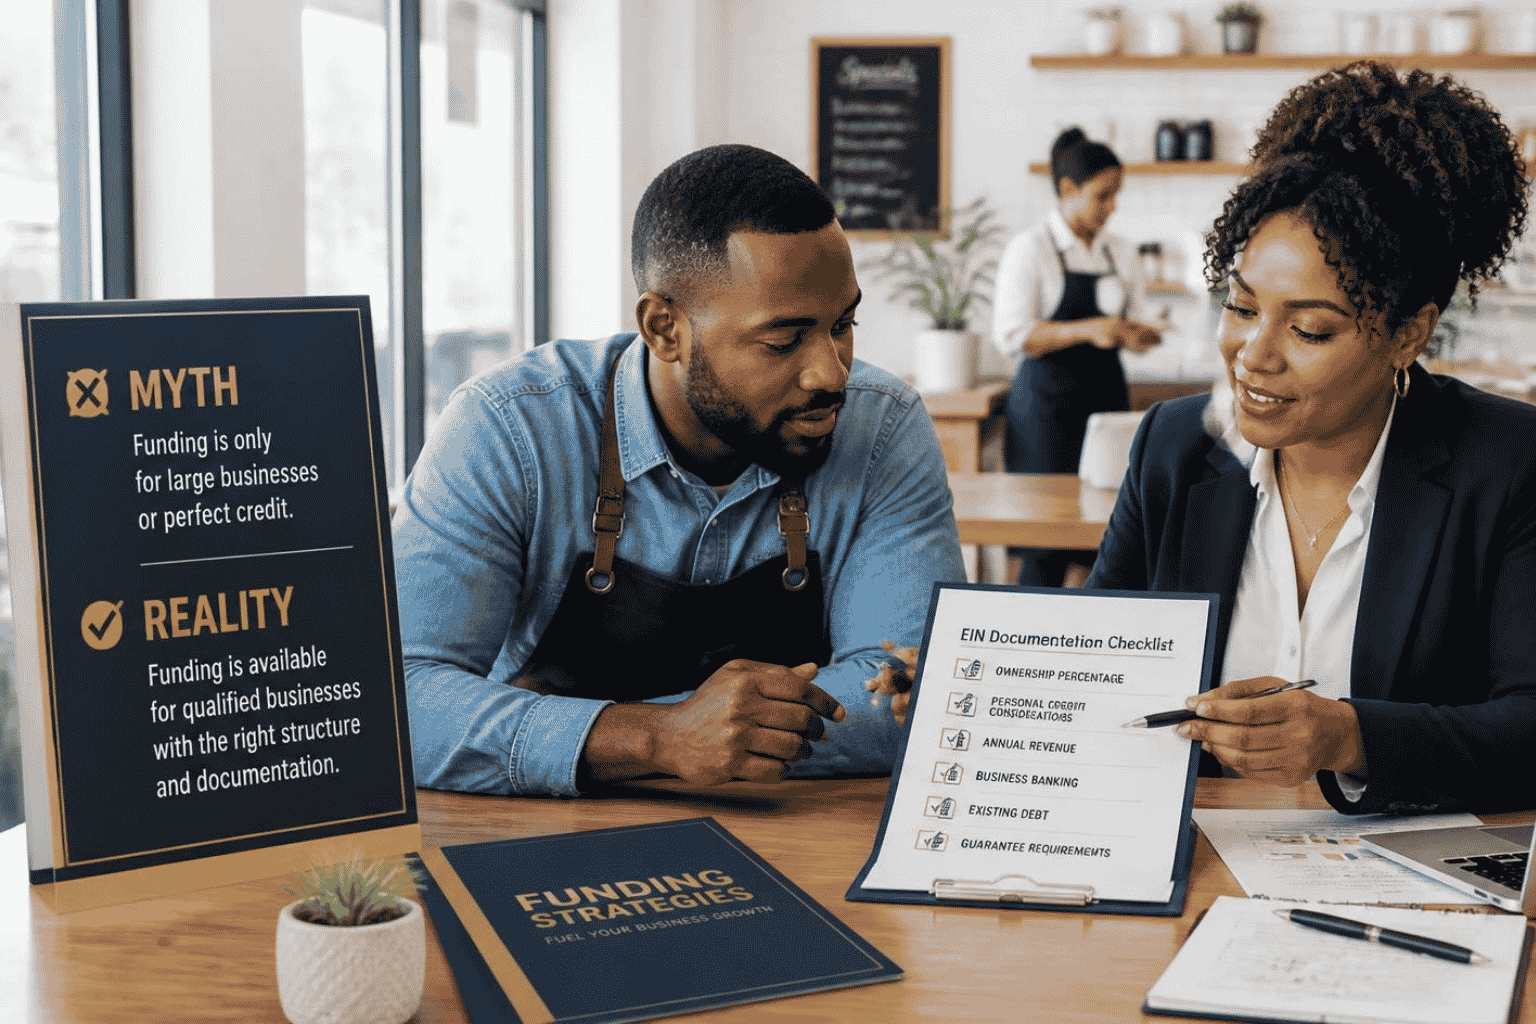 EIN-only funding and no-personal-guarantee financing are different concepts, and lenders may still evaluate the complete business profile.