Small Business Working Capital Loan With EIN: What Lenders Still Review Beyond the Tax ID
Business owners searching for a small business working capital loan with an EIN are often trying to answer one practical question: can the business qualify for capital based primarily on the company rather than the owner’s personal finances?
An EIN is an important part of the business application, but it does not automatically replace underwriting. Funding providers may still evaluate the broader business and borrower profile.
What Does an EIN Actually Establish?
An Employer Identification Number identifies the business for federal tax and other business purposes. It may be required or recommended in different financing applications, but the existence of an EIN by itself does not show revenue, repayment ability, operating history or cash flow.
What Are Common Working-Capital Benchmarks?
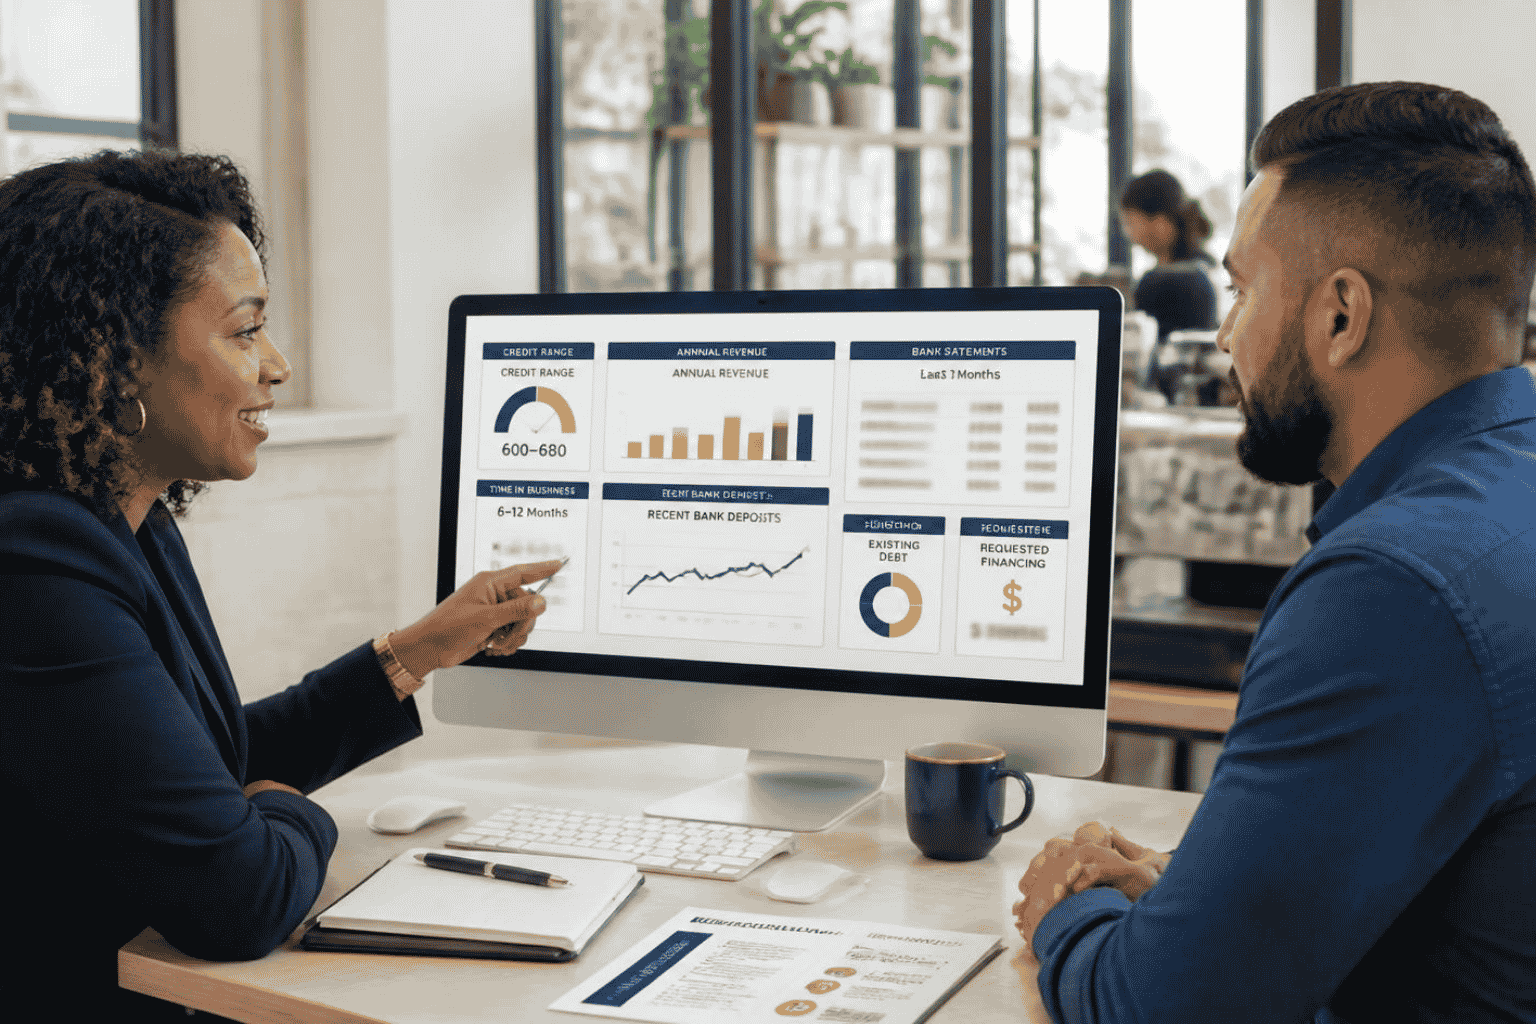
The EIN Business Funding guidance identifies approximately 600+ personal credit, six to twelve months in business and around $50,000 to $100,000 in annual revenue as common working-capital benchmarks.
Those numbers are not universal approval standards. Different providers may apply different requirements.
Why Do Recent Business Deposits Matter?
A funding provider may want to understand whether the company is actively generating revenue today. Recent deposits and business bank statements can provide a current view of business activity that annual revenue alone may not show.
What If the Business Has 600–680 Credit?
Depending on the complete profile, online or alternative business financing may also be worth evaluating. The funding guidance identifies approximately 600 to 680+ personal credit, six to twelve months in business and approximately $50,000 to $250,000+ annual revenue as common benchmarks for that broader category.
What Is the Working Capital Actually For?
A useful funding request should identify the purpose of the capital. Common operating needs can include inventory, payroll, supplier payments, marketing tied to established operations or another clearly defined short-term business expense.
A vague request for “as much money as possible” gives less information than a business owner who knows the exact cash gap and why it exists.
What Existing Debt Should Be Disclosed?
Prepare all open business loans, lines of credit and business credit cards. Existing obligations affect the overall repayment picture and should be included accurately during funding review.
What Information Should You Have Ready?
- Legal business name
- EIN
- Entity type
- Business formation date
- Ownership percentage
- Annual business revenue
- Recent business deposits
- Business banking institution
- Current credit profile
- Existing business debt
- Requested amount
- Specific use of funds
Does “Business Funding With EIN” Mean EIN-Only Financing?
No. Search language and underwriting language are not necessarily the same. A business owner may naturally search “working capital loan with EIN,” while the actual funding review still considers additional information.
This distinction matters because it allows owners to use the search phrase that matches their need without assuming that a tax ID alone determines eligibility.
When Should You Move From Research to Pre-Qualification?
If you know how much capital you need, why you need it and can provide current revenue, business history and credit information, you have enough information to begin a more focused funding review.
Complete the EIN Business Funding Quick Lead Pre-Qualification with your actual business profile rather than applying randomly across unrelated financing products.
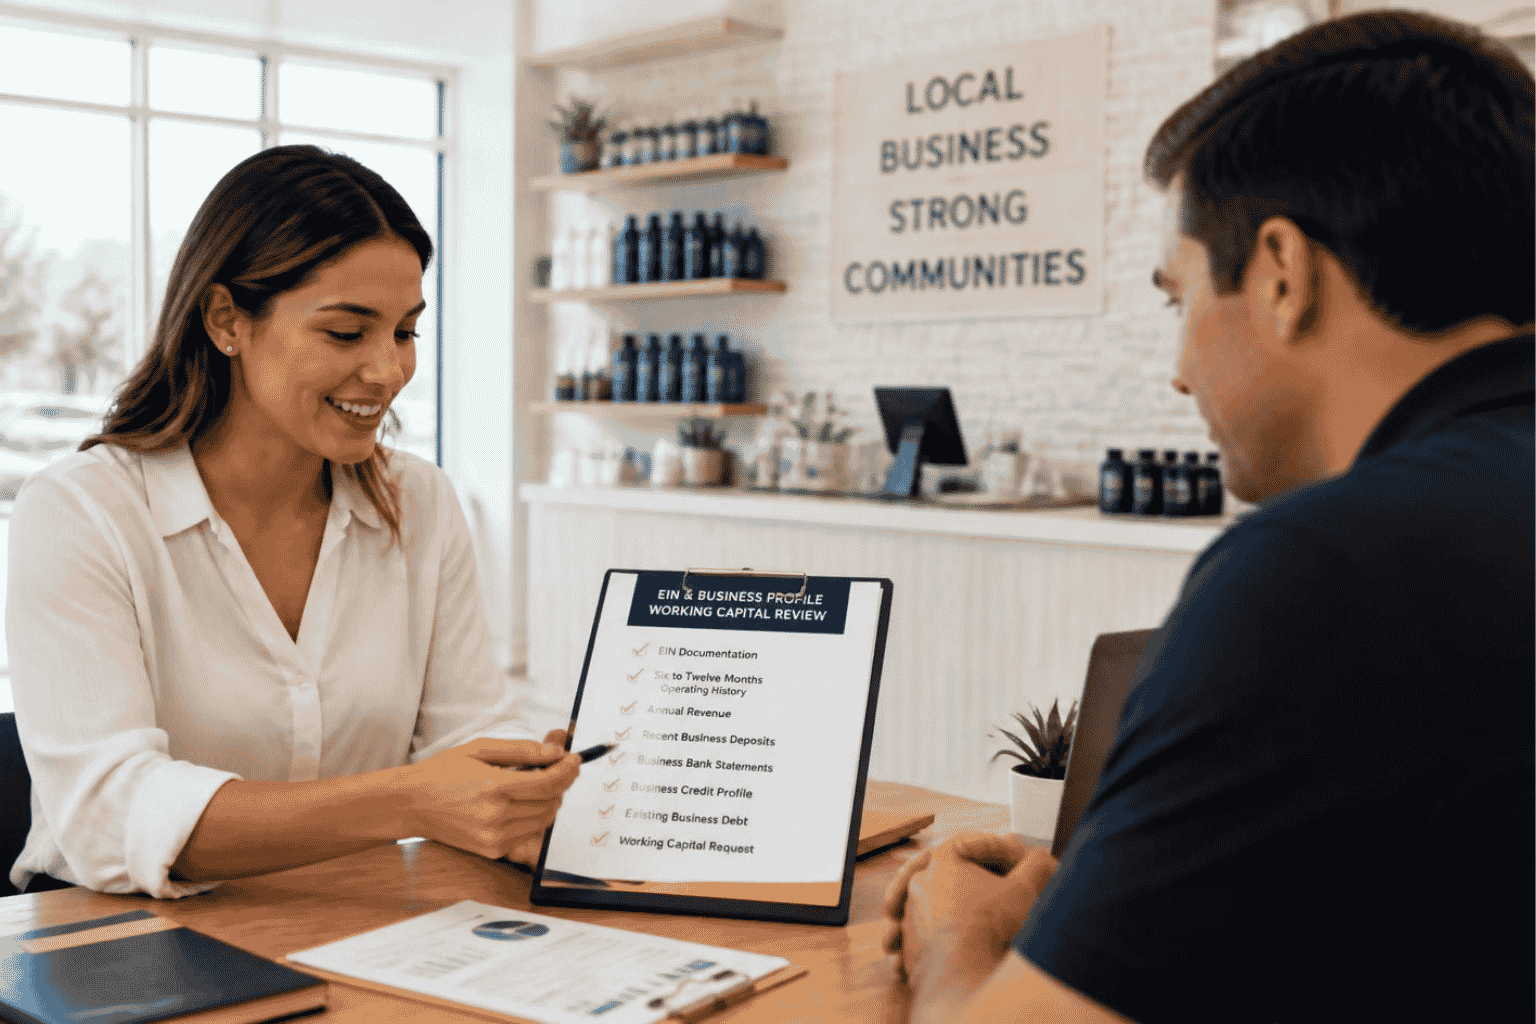 An EIN identifies the business, but working-capital providers may still review credit, revenue, deposits and repayment capacity.