Business Funding Pre-Qualification vs Full Application: What Owners Should Prepare First
Business owners often hesitate to start a funding request because they expect the first step to require a complete loan application, extensive documents and highly sensitive personal information.
That is not always necessary at the beginning. A useful pre-qualification conversation can start with a smaller set of business facts designed to determine which financing categories may be worth exploring.
If your funding need is active now, the EIN Business Funding Quick Lead Pre-Qualification is designed to begin with the business need and current profile rather than assuming every visitor should immediately complete the same full application.
What Is Pre-Qualification?
Pre-qualification is an initial screening step. The purpose is to understand the basic funding need and borrower profile before moving deeper into a specific financing process.
It can help answer whether the business appears closer to a working-capital loan, term loan, equipment financing, line of credit or another funding category.
What Is a Full Funding Application?
A full application generally occurs later, when a specific provider or financing structure requires detailed underwriting information and supporting documents.
The exact information depends on the product and provider.
What Should You Know Before Pre-Qualification?
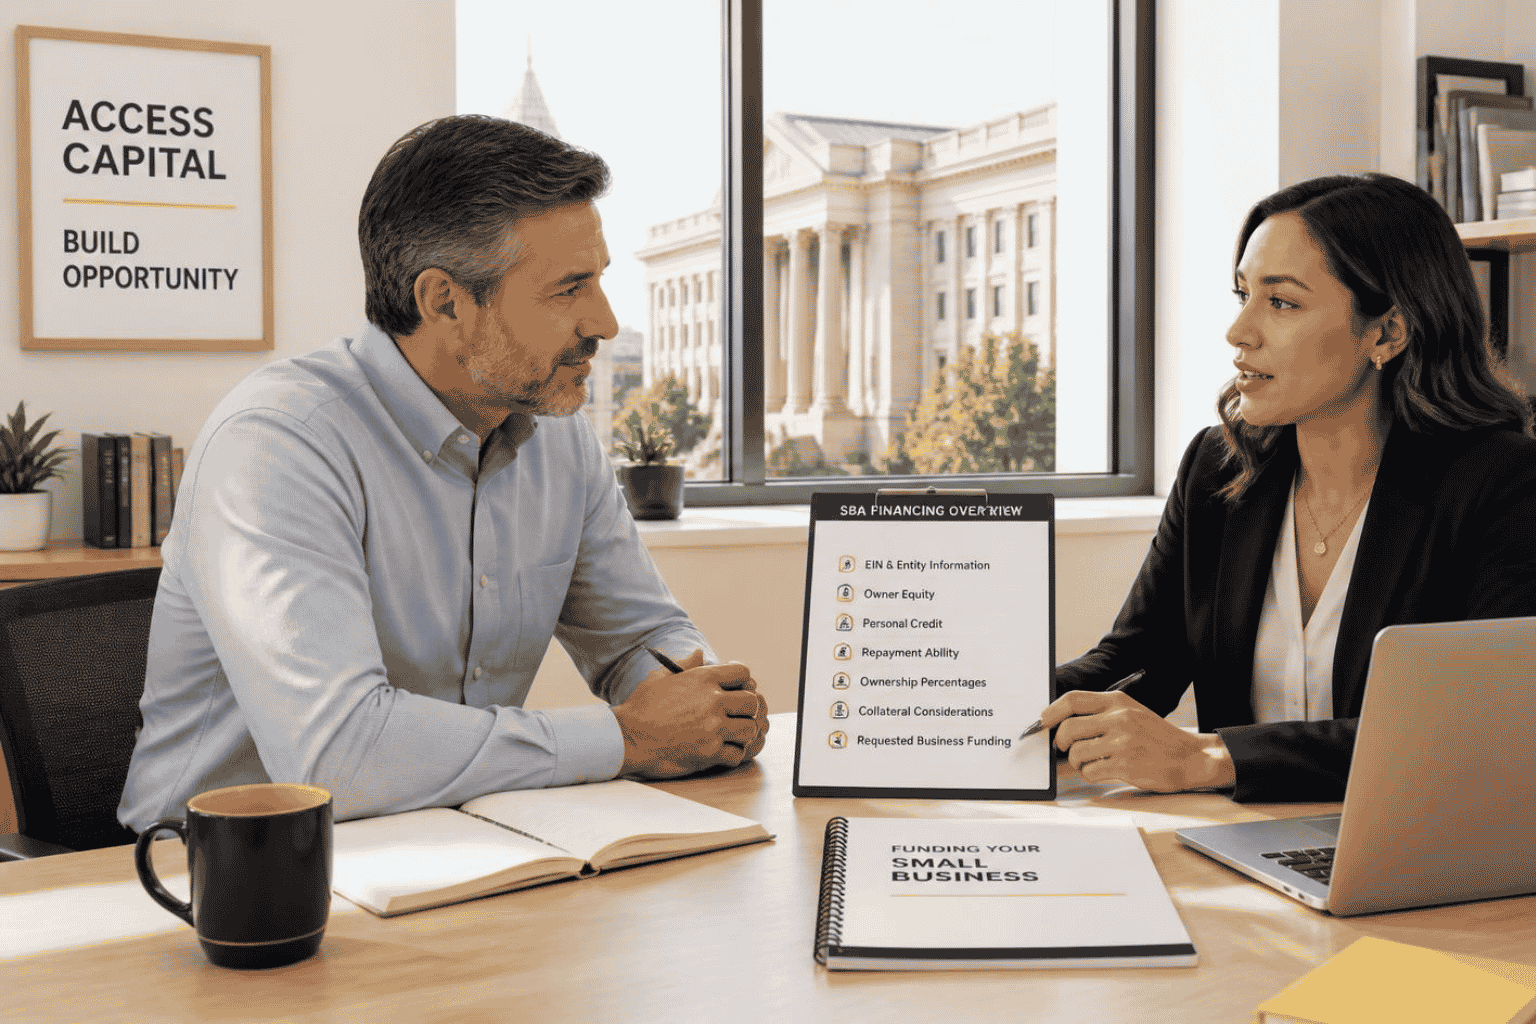
Start with information you should already understand as the business owner:
- Amount of capital needed
- Specific use of funds
- Business formation date
- Entity type and EIN
- Annual business revenue
- Recent business deposits
- Current credit profile
- Existing business loans and credit lines
- Ownership percentage
Why Start With the Use of Funds?
The reason for borrowing can determine which financing paths are relevant.
Buying a machine is different from covering payroll. Purchasing a business is different from replenishing inventory. Financing commercial real estate is different from handling a temporary receivables gap.
Without a clear use of funds, even a strong business profile can be difficult to match to the right financing category.
Why Revenue and Business Age Matter Early
Different funding products use different operating-history and revenue thresholds.
For example, the EIN Business Funding guidance identifies six to twelve months in business and approximately $50,000 to $100,000 in annual revenue as common working-capital benchmarks, while term-loan profiles commonly begin around one year in business and $100,000+ annual revenue.
This is why business age and revenue can be useful during the first screening stage.
Why Credit Should Not Be Guessed
Owners sometimes describe credit simply as “good,” “fair” or “not great.” That can be too vague for funding screening.
Different financing products can use substantially different credit ranges. Knowing the current score can help avoid spending time on financing categories that are clearly mismatched to the borrower profile.
What Existing Debt Should You Know?
Prepare open business credit cards, business lines of credit and business loans, including the lender or card name, applicable limit, balance and open date.
Existing obligations can materially affect the amount of additional financing the business can support.
When Do More Detailed Documents Become Relevant?
Once the financing path becomes more specific, providers may request additional financial or personal information.
Traditional financing can require bank statements, profit and loss statements, tax returns and other supporting documentation. Other financing categories may use different documentation.
Do Not Share Sensitive Information Publicly
Information such as Social Security numbers, dates of birth and private financial records should only be provided through appropriate secure application processes when legitimately required.
A public blog comment, social-media message or ordinary email thread is not the place to post sensitive financial credentials.
Why Pre-Qualification Can Save Time
A business owner with 620 credit, eight months in business and $90,000 in annual revenue should not necessarily begin with the same product search as an owner with 740 credit, five years in business and $1 million in annual revenue.
Pre-qualification helps organize the funding conversation around the profile that actually exists.
What Is the Best First Step?
Know the amount, purpose, business age, revenue, credit and existing debt. Those details create a useful starting point without assuming the company already knows which lender or financing product it needs.
Once the initial profile is clear, deeper documentation can be gathered for the funding path that appears relevant.
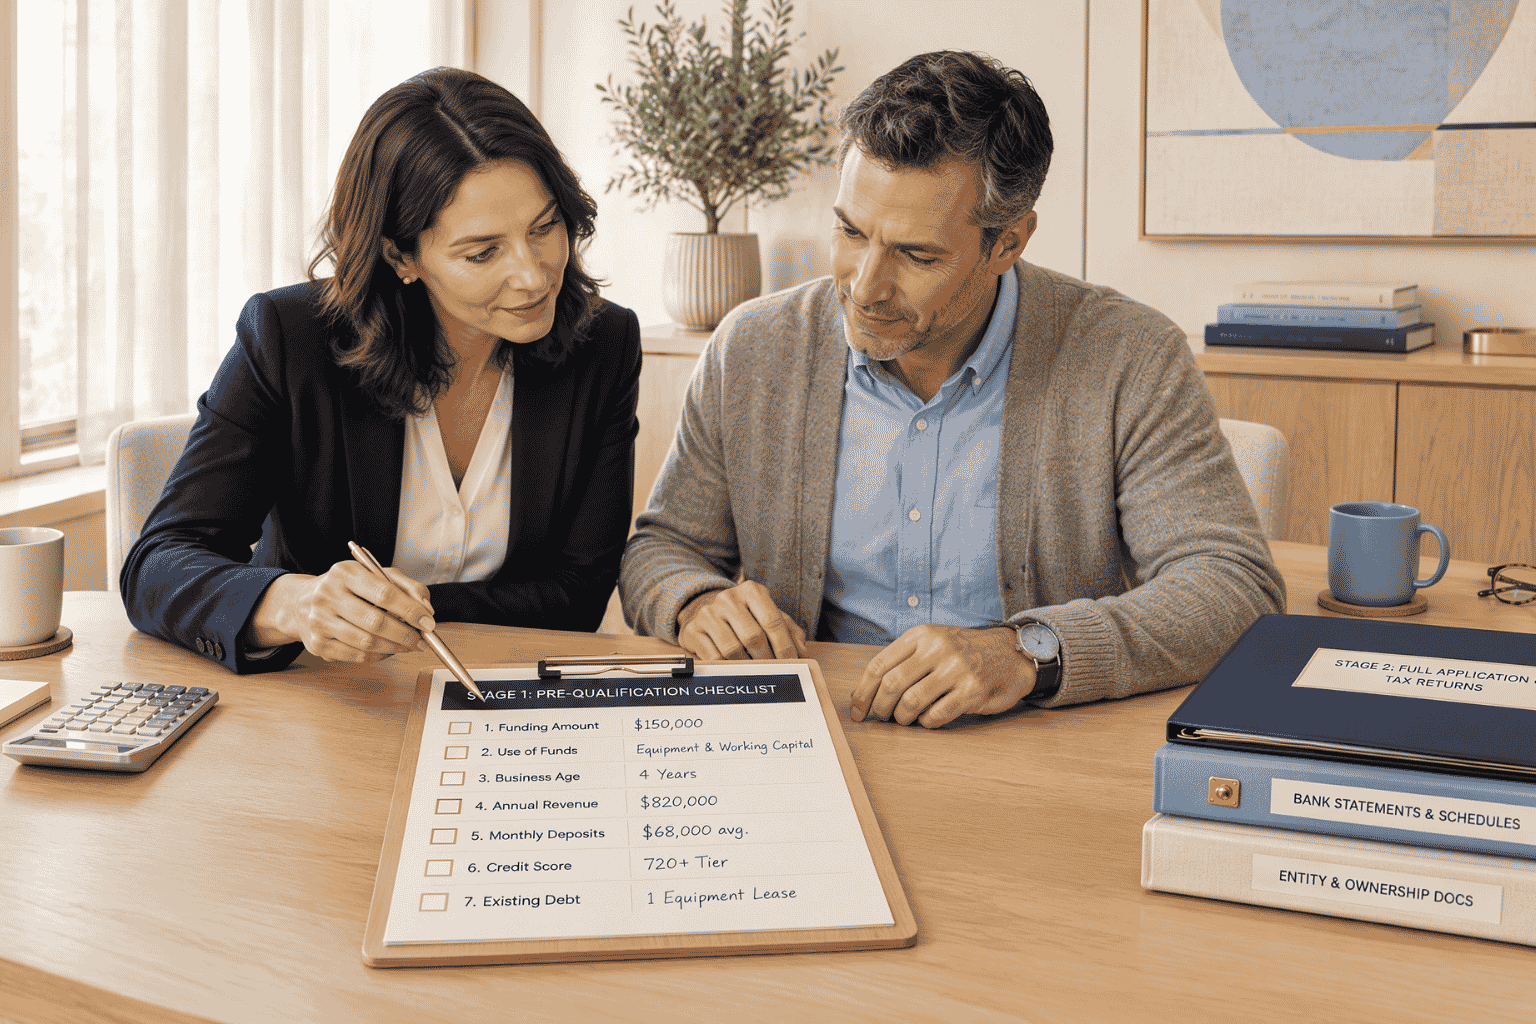 Pre-qualification can begin with core business facts before a specific funding provider requests deeper documentation.